Maharashtra land conversion policy for martyrs families
Source:Indian Express ↗
Why It Matters
Highlights a concrete example of a state government modifying complex land revenue rules (such as Occupancy Class conversions) to deliver targeted social justice and welfare to the families of armed forces personnel. It serves as a good case study for GS-II (Welfare Schemes) and GS-III (Land Reforms).
Summary
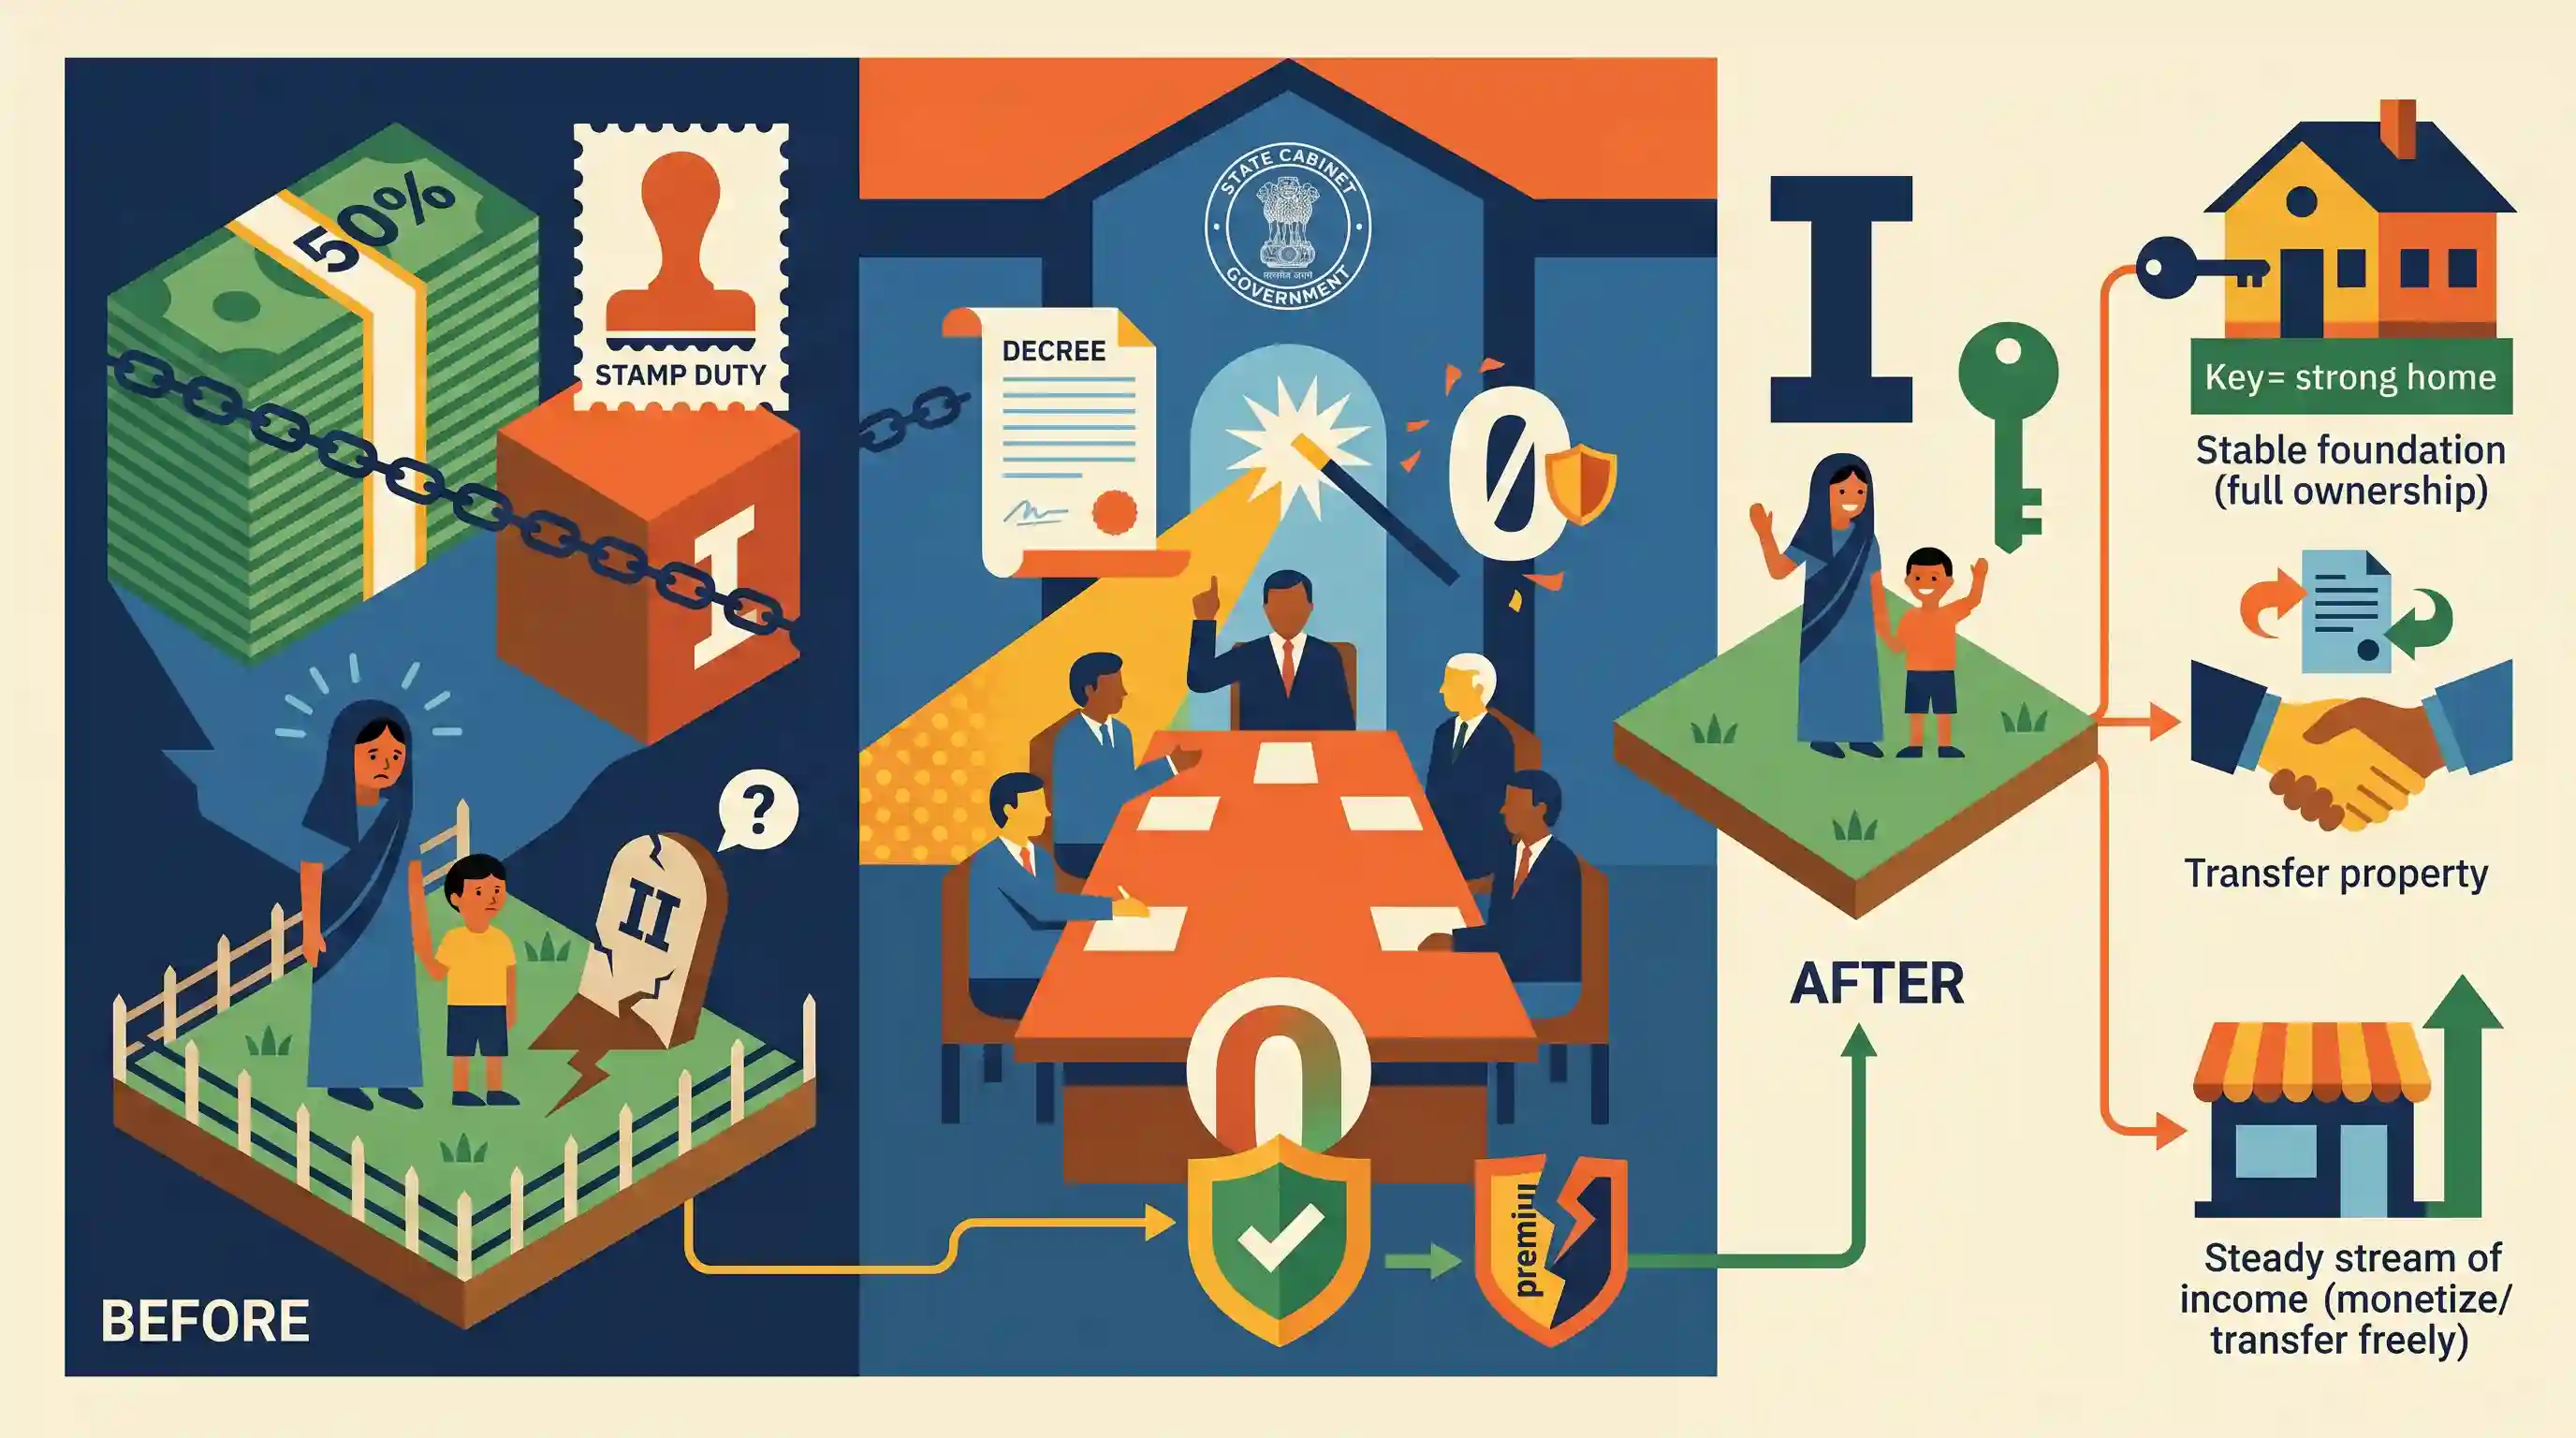
The Maharashtra state cabinet has approved a significant welfare measure allowing the widows of martyred soldiers to convert their allotted agricultural land from Occupancy Class-II to Occupancy Class-I at zero cost. By waiving the hefty conversion premiums (previously 50% of the ready reckoner rate) and stamp duties, the policy grants full, unencumbered ownership rights to these families, alleviating financial burdens and empowering them to monetize or transfer their properties freely.
Key Points
- The Maharashtra government has approved a policy to completely waive the conversion premium and stamp duty on agricultural land allotted to the widows of martyred soldiers.
- The decision allows for the free conversion of such land from Occupancy Class-II (conditional ownership with restrictions on sale or transfer) to Occupancy Class-I (absolute ownership).
- Previously, converting this land required paying a premium equivalent to 50% of the ready reckoner rate (often amounting to ₹15-20 lakh), which was a significant financial hurdle.
- By granting full, unencumbered ownership, the state government aims to provide long-term financial security and ease of property monetization for martyrs' families.
Important Terms
Occupancy Class-I

A category of land ownership in Maharashtra (under the Land Revenue Code) where the holder has full, heritable, and transferable rights without needing prior government permission for sale or mortgage.
UPSC context
Relevant for GS III (Land Reforms); distinguishes freehold rights from restricted tenures in agricultural policy.
Occupancy Class-II
Land granted by the state with restrictions on transfer and use. Any sale or conversion to non-agricultural use requires the District Collector's permission and payment of a premium.
UPSC context
Tests understanding of state-granted conditional land titles and administrative control over land distribution.
Ready Reckoner Rate (RRR)
The government-notified minimum property value used to calculate stamp duty and registration charges for real estate transactions. It acts as a benchmark for assessing land conversion premiums.
UPSC context
Crucial for GS III (Economy/Resource Mobilization) regarding state revenue and real estate transparency.
Conversion Premium
A fee (usually 50% of the Ready Reckoner Rate) paid to the state government to upgrade land status from restricted (Class-II) to full ownership (Class-I).
UPSC context
Relates to GS II (Social Justice) when discussed as a financial barrier to welfare beneficiaries.
Sainik Welfare Department (Maharashtra)
The state nodal agency responsible for implementing welfare programs for ex-servicemen, widows, and their dependents, often coordinating with District Collectors for land allotments.
UPSC context
GS II (Governance/Welfare Schemes); tests knowledge of institutional mechanisms for vulnerable groups.
Maharashtra Land Revenue Code, 1966
The principal legal framework governing land administration, classification of occupants, and revenue collection procedures in the state of Maharashtra.
UPSC context
Essential statutory reference for GS III (Land Reforms) and state-level administrative law questions.
Prelims Trap
"Stamp duty rates on all transactions and property transfers are determined uniformly by the Union Government."
While the Union sets stamp duties for specific financial instruments (Entry 91), stamp duty rates for property transactions fall strictly under the State List (Entry 63).
Static Concepts Connected
How is jurisdiction over stamp duties divided under the Seventh Schedule?
- Union List: Entry 91 covers rates of stamp duty for specific financial instruments like bills of exchange, cheques, and promissory notes.
- State List: Entry 63 covers rates of stamp duty for documents other than those specified in the Union List, granting states authority over property transaction duties.
What distinguishes Occupancy Class-I from Class-II land in Indian revenue systems?
- Class-I Land: Represents absolute freehold ownership, granting the titleholder unrestricted rights to transfer, sell, or monetize the property without seeking state approval.
- Class-II Land: Represents conditional ownership. Any transfer, sale, mortgage, or change in land use requires prior permission and often a premium payment to the Government or District Collector.
Cross-Topic Patterns
Land ownership and gender justice
Upgrading land to absolute ownership directly empowers widows by removing bureaucratic hurdles to monetize assets, aligning with DPSP goals of adequate livelihood and gender parity.
Federalism in veteran rehabilitation
While the Ministry of Defence manages pensions via the Kendriya Sainik Board, physical resettlement relies heavily on States utilizing their exclusive constitutional jurisdiction over land and local stamp duties.

Expect a Schedule VII matching question in Prelims contrasting stamp duty on financial instruments (Union) vs property (State).
Linked PYQs · 2
Linked PYQs · 2
- 2019MainsGS2
Performance of welfare schemes that are implemented for vulnerable sections is not so effective due to absence of their awareness and active involvement at all stages of policy process. Discuss.
- 2016MainsGS3
Discuss the role of land reforms in agricultural development. Identify the factors that were responsible for the success of land reforms in India.
