Uttarakhand High Court GST Refund Natural Justice Violation Ruling
Source:studycafe ↗
Why It Matters
This ruling is vital for understanding the intersection of fiscal administration and constitutional law. It reiterates that tax authorities must adhere to the Principles of Natural Justice (Audi Alteram Partem) and statutory procedural mandates, such as Section 75(4) of the CGST Act, before passing adverse orders. Furthermore, it clarifies the scope of Article 226 writ jurisdiction, establishing that alternative remedies do not preclude high courts from intervening in cases of procedural unfairness.
Summary
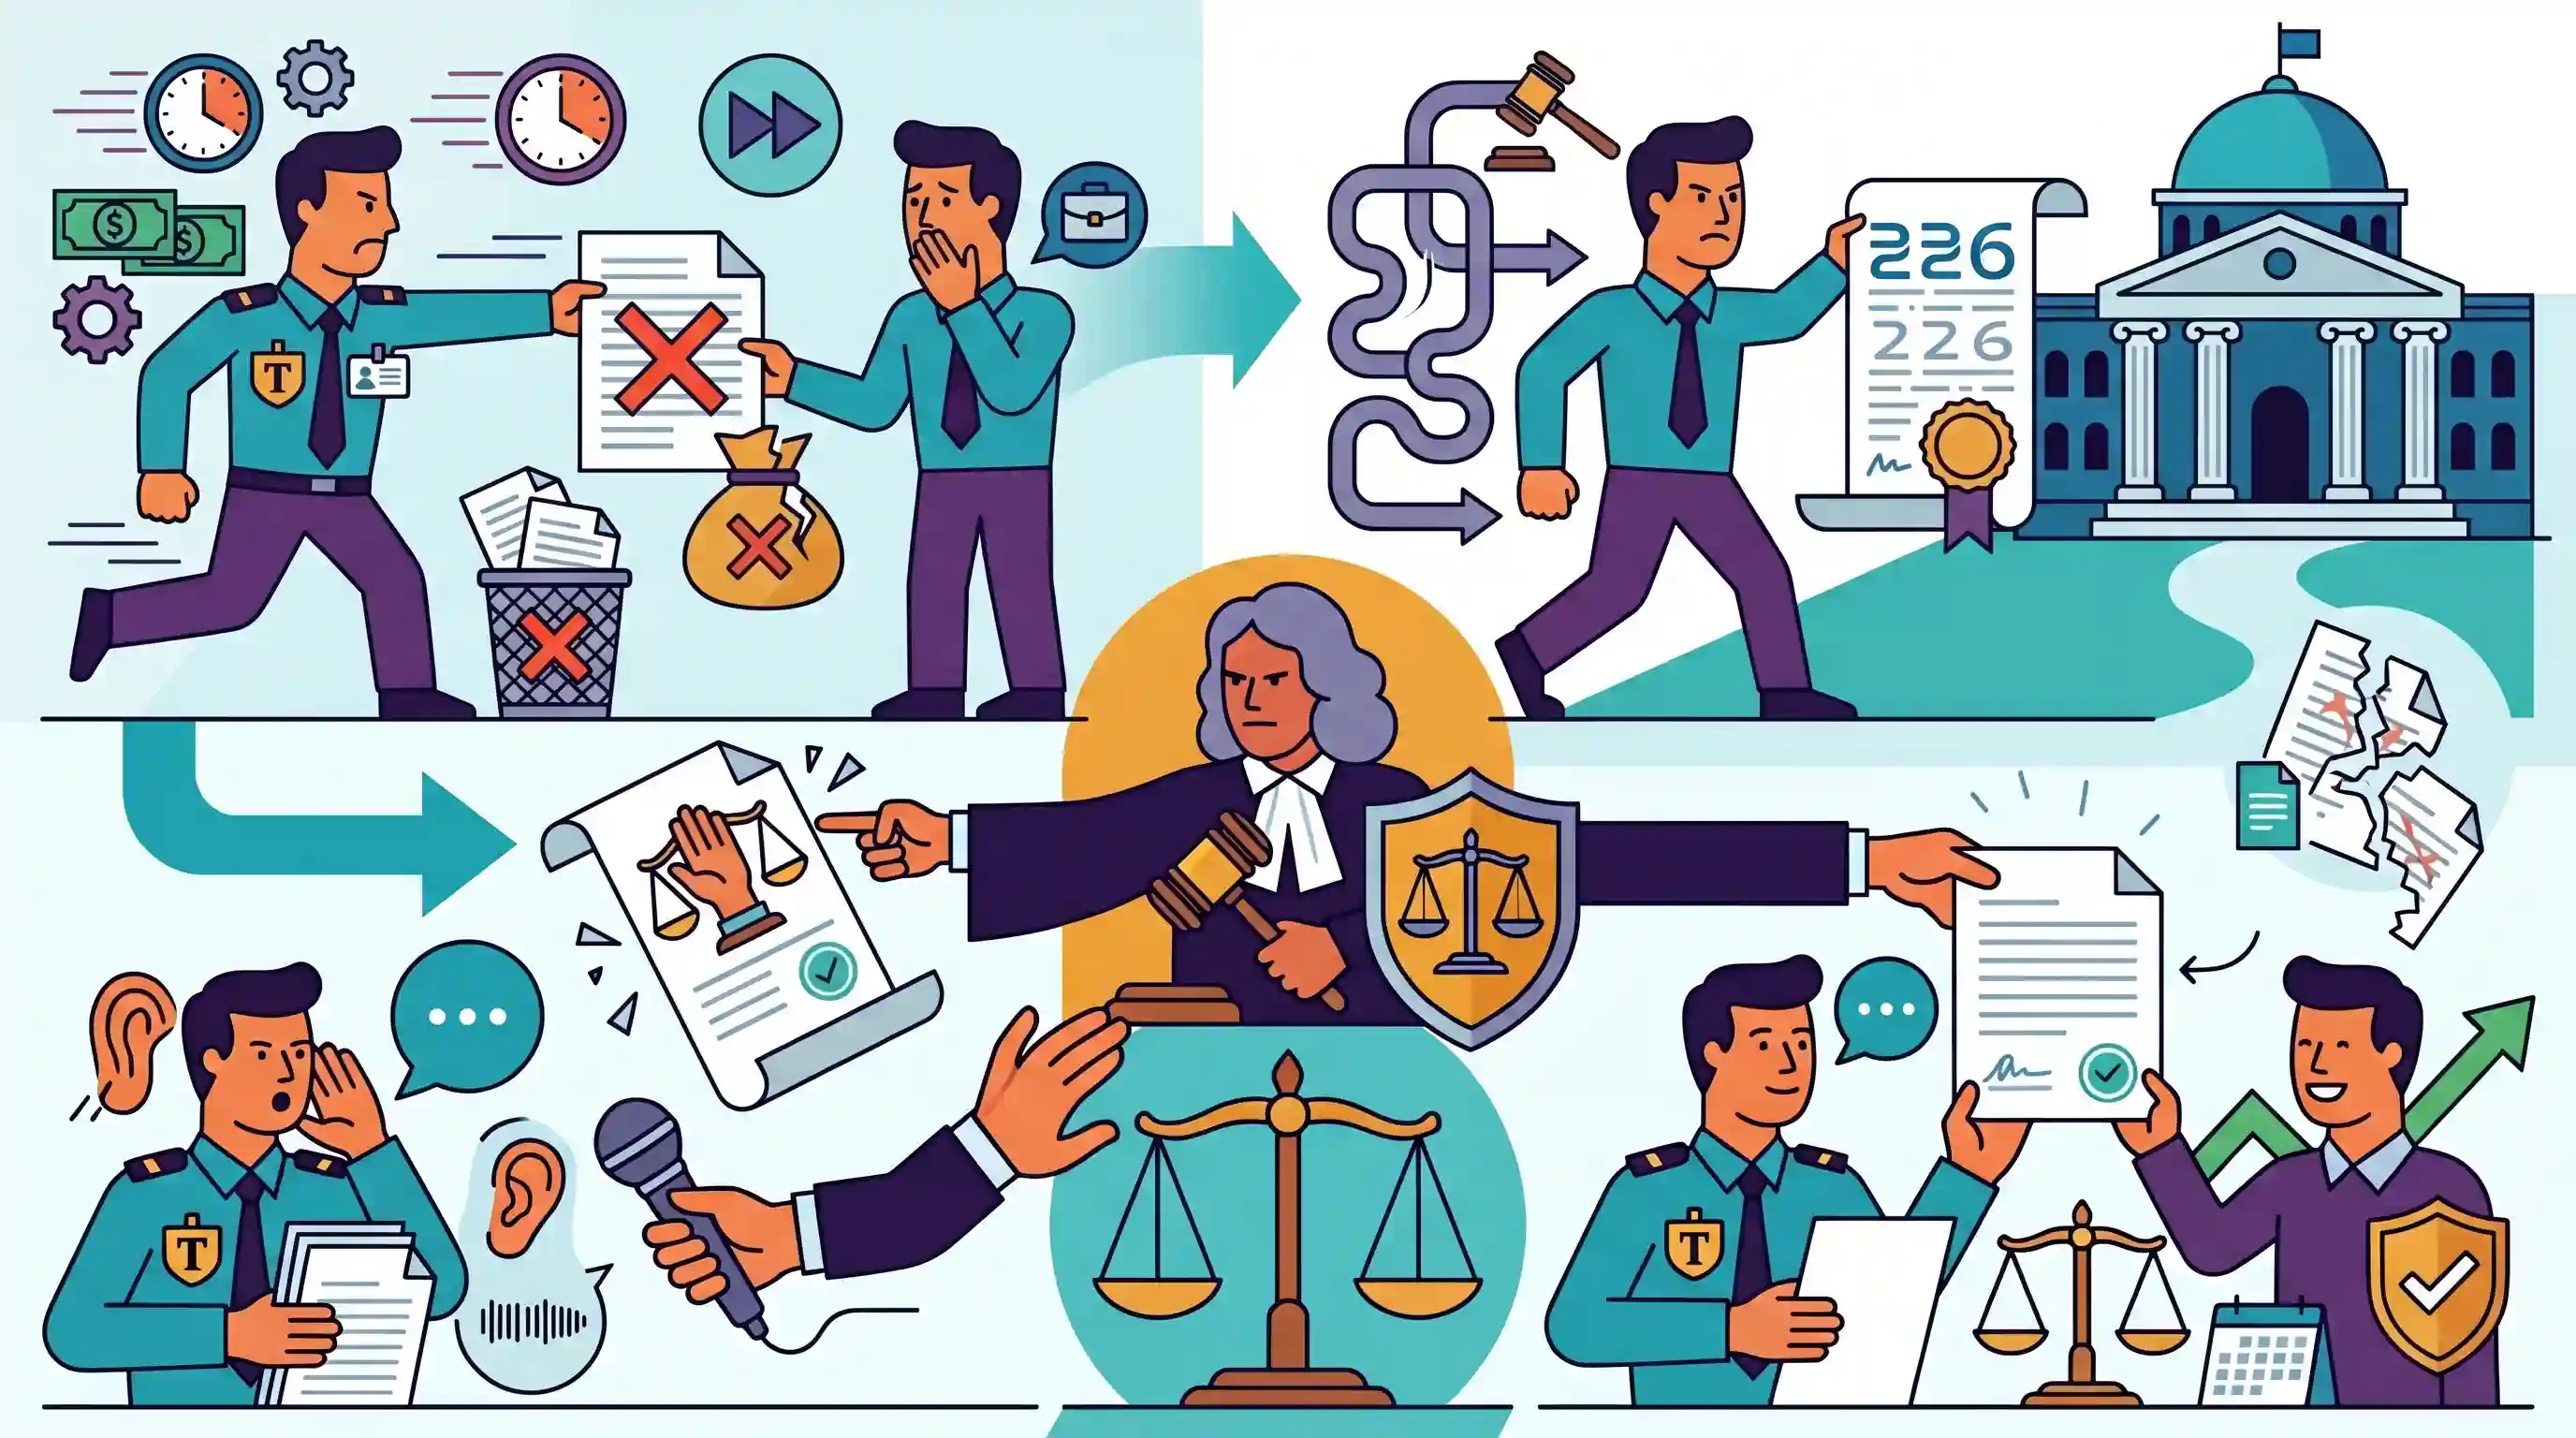
The Uttarakhand High Court quashed a GST refund rejection order passed by the CGST department against Cholayil Private Limited. The Court ruled that the tax authority acted in haste by not considering the taxpayer's reply and failing to provide a personal hearing, thereby violating the Principles of Natural Justice. Despite the availability of an alternative appeal process, the Court exercised its writ jurisdiction under Article 226 to protect the petitioner's rights and remanded the case for fresh adjudication.
Key Points
- The Uttarakhand High Court quashed a GST refund rejection order issued by the Assistant Commissioner of CGST, ruling that it was passed in haste and violated the Principles of Natural Justice.
- The petitioner, Cholayil Private Limited, had filed a refund claim under the CGST Act which was rejected by the tax authorities without considering the detailed reply submitted by the petitioner or granting a personal hearing.
- The Division Bench comprising Justice Manoj Kumar Tiwari and Justice Pankaj Purohit held that a fair opportunity to be heard and the consideration of a taxpayer's reply are essential statutory and constitutional mandates.
- The Court clarified that the existence of an alternative statutory remedy (such as filing an appeal under Section 107 of the CGST Act) does not bar the High Court from exercising its writ jurisdiction under Article 226 of the Constitution if there is a blatant violation of natural justice.
- The matter has been remanded back to the CGST department for fresh adjudication, requiring them to pass a reasoned order after providing a personal hearing to the petitioner.
- Under Section 75(4) of the CGST Act, 2017, an opportunity of hearing is mandatory where an adverse decision is contemplated against the taxpayer.
Important Terms
Constitution of India

The supreme law of India, establishing the political framework, powers of government institutions, and fundamental rights, including constitutional remedies like writ jurisdiction under Articles 32 and 226.
UPSC context
GS Paper II (Polity & Governance); tests fundamental constitutional principles, division of powers, federalism, judicial review, and individual rights.
Central Goods and Services Tax (CGST) Act, 2017
A key parliamentary legislation in India governing the levy, collection, and administration of tax on the intra-state supply of goods and services by the Central Government.
UPSC context
GS Paper III (Indian Economy & Taxation); tests federal fiscal structure, indirect taxation system, and mechanisms like input tax credit.
Uttarakhand High Court
The highest state-level judicial body in Uttarakhand, established in 2000 under the Uttar Pradesh Reorganisation Act, exercising original, appellate, and discretionary writ jurisdiction.
UPSC context
GS Paper II (Indian Judiciary); tests structure, jurisdiction, and power of High Courts, judicial review, and state-level justice administration.
Central Goods and Services Tax (CGST) Department
The executive authority under the Ministry of Finance responsible for administering, collecting, and enforcing the central indirect tax on intra-state supply of goods and services.
UPSC context
GS Paper III (Tax Administration); tests administrative discretion, fiscal policy implementation, and dispute resolution mechanisms in taxation.
Prelims Trap
High Courts are constitutionally barred from entertaining writ petitions under Article 226 if an alternative statutory appeal mechanism exists.
It is a rule of policy, self-imposed limitation, and convenience rather than an absolute constitutional bar on the High Court's powers.
Static Concepts Connected
What is the relation between writ jurisdiction under Article 226 and alternative statutory remedies?
- Self-imposed limit: High Courts usually decline writ petitions if statutory appeals exist, but this is a rule of self-imposed policy and discretion, not constitutional limitation.
- Whirlpool Doctrine: Established that writs are maintainable despite alternative remedies if fundamental rights are violated, natural justice is breached, or proceedings lack jurisdiction.
- Remedial scope: Article 226 is wider than Article 32 because it can be invoked for both fundamental rights and ordinary legal rights.
How are the Principles of Natural Justice situated within the Indian Constitution?
- Core Maxims: Implies the right to a fair hearing ('audi alteram partem') and that no person should judge their own cause ('nemo judex in causa sua').
- Constitutional source: Not explicitly written, but judicially read into Articles 14 and 21 to ensure administrative procedures are just, fair, and reasonable.
- Maneka Gandhi Case: Established that 'procedure established by law' must conform to natural justice, transforming Indian administrative review and protecting citizens from arbitrary state action.
Cross-Topic Patterns
Writ jurisdiction vs Tax administration
Illustrates the tension between rapid revenue mobilization (GST collection targets) and the judiciary's mandate to uphold constitutional procedural safeguards under Article 226.
Codification of Administrative Law
Highlights how uncodified common law doctrines of natural justice are explicitly integrated into modern economic statutes like Section 75(4) of the CGST Act.

UPSC may test the discretionary nature of Article 226 and exceptions to the 'alternative remedy' rule under tax laws in 2026.
Linked PYQs · 2
Linked PYQs · 2
- 2021UKPSC_PRELIMSGS1
Which of the following taxes are abolished by the Goods and Services Tax?
- 2025UKPSC_PRELIMSGS1
101ˢᵗ Constitutional Amendment Act is related with :
