Fiscal federalism friction over borrowing limits and grants
Source:The Hindu ↗
Why It Matters
The article serves as a critical case study for UPSC aspirants on the ongoing friction in Centre-State financial relations, highlighting issues surrounding fiscal federalism, the role of the GST Council, conditional borrowing under Article 293(3), and the withholding of Central grants. Such real-world examples are highly relevant for GS Paper 2 and 3 answers on federal structures and state finances.
Summary
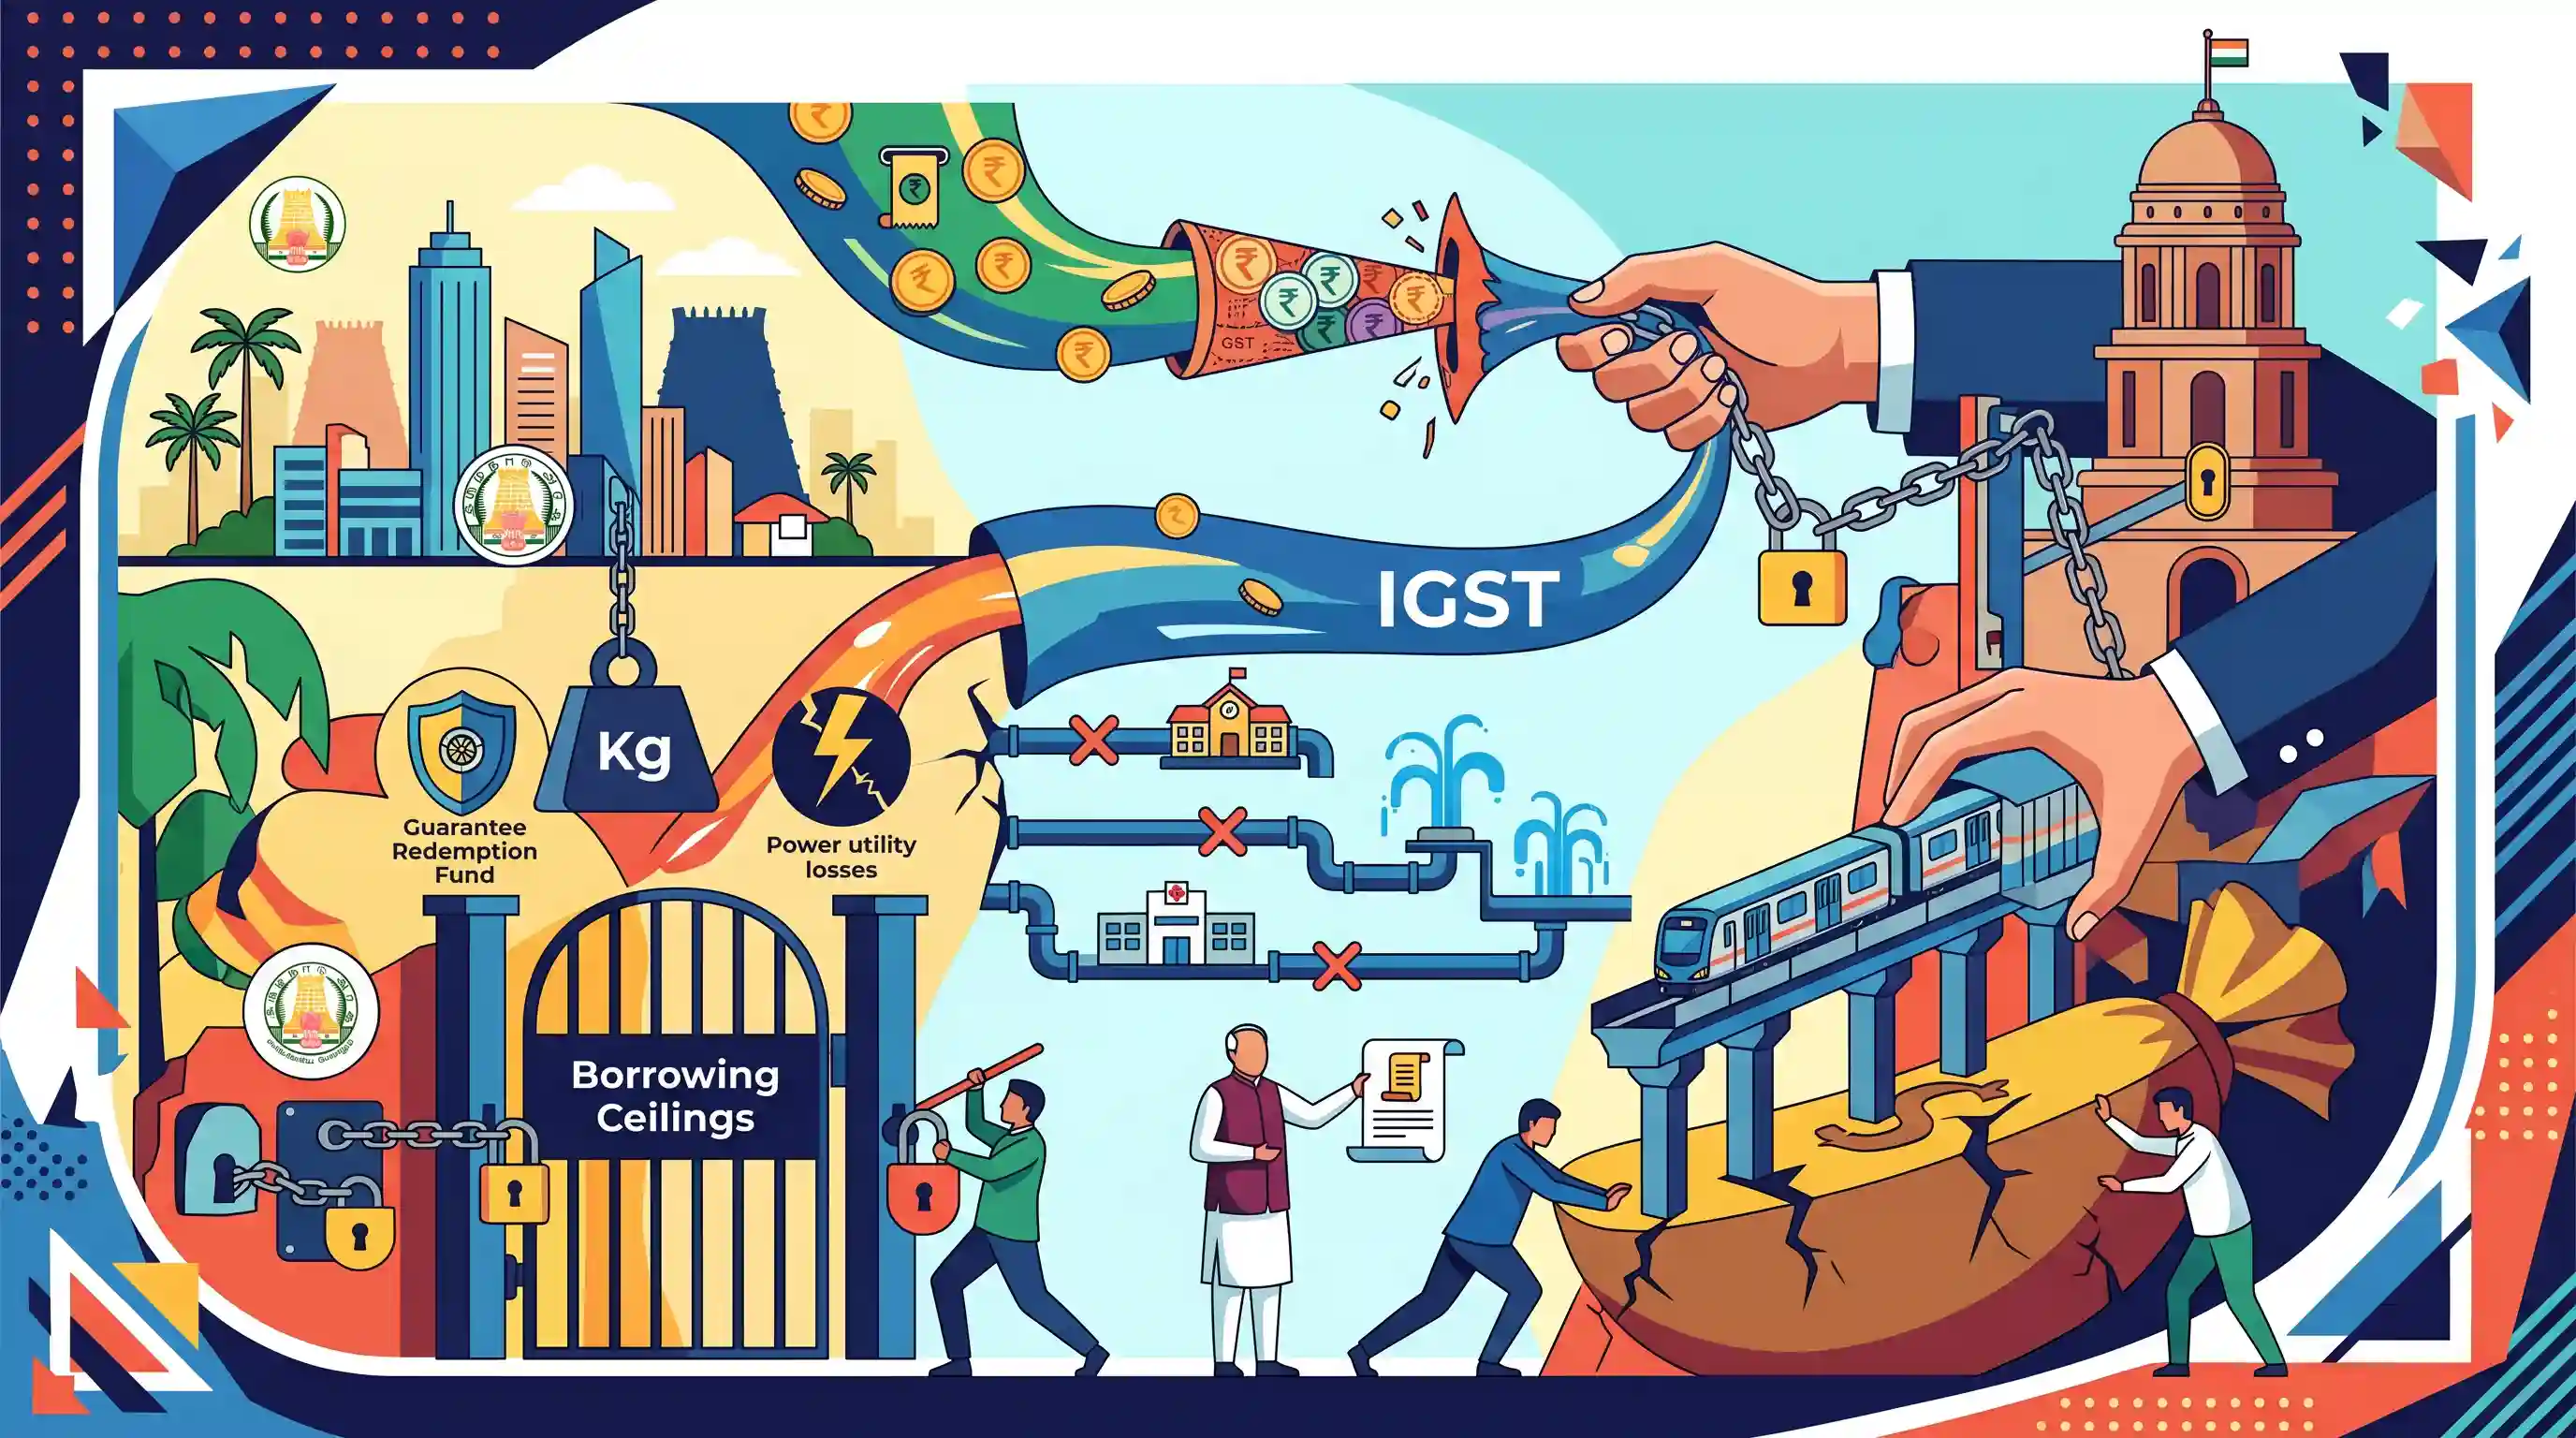
Tamil Nadu Finance Minister Thangam Thennarasu presented the interim budget for 2026-27, heavily criticizing the Union Government for precipitating a fiscal crisis in the state. He outlined multiple instances of friction in Centre-State financial relations, including revenue shortfalls caused by GST rationalizations and direct IGST deductions from the RBI. The Minister highlighted the Center's use of Article 293(3) powers to mandate unbudgeted fiscal provisions—such as the Guarantee Redemption Fund and loss funding for the state power utility—as conditions for maintaining borrowing ceilings. Additionally, the withholding of funds for Centrally Sponsored Schemes and Finance Commission grants, along with the misallocation of Chennai Metro Phase-II expenditures onto the state's debt profile, were cited as major challenges to Tamil Nadu's fiscal federalism and autonomy.
Key Points
- Tamil Nadu's Interim Budget 2026-27 was presented amidst allegations by Finance Minister Thangam Thennarasu that the Union government is 'artificially precipitating' a fiscal crisis in the State.
- The State faced severe revenue shortfalls due to unconsulted GST rate rationalizations (₹9,600 crore loss) and direct deduction of ₹1,709 crore IGST settlement by the Centre from the RBI.
- Under Article 293(3), the Centre mandated unbudgeted contributions of ₹3,087 crore to the Guarantee Redemption Fund and forced the State to absorb ₹16,290 crore in losses from the state power utility to maintain its borrowing ceilings.
- The State reported denial of crucial funds under Centrally Sponsored Schemes, including the Samagra Shiksha Scheme and Jal Jeevan Mission, along with withheld Finance Commission Grants.
- Capital expenditure incurred for the Chennai Metro Rail Phase-II on the Centre's behalf was accounted as the State's outstanding debt, constraining its borrowing capacity and impacting its debt-to-GSDP ratio.
Important Terms
Article 293 of the Constitution

A constitutional provision (Part XII) regulating State borrowing. Clause (3) requires States to obtain Union consent for new loans if previous Central debts are outstanding, allowing the Centre to impose fiscal conditions.
UPSC context
GS Paper II (Polity): Centre-State Relations. Tests understanding of fiscal autonomy versus central oversight in India's federal structure.
Finance Commission
A constitutional body established under Article 280 to recommend the vertical and horizontal distribution of net tax proceeds and determine principles for providing grants-in-aid to States.
UPSC context
GS Paper II/III (Polity/Economy): Constitutional Bodies. Tests knowledge of fiscal devolution and the balancing of financial imbalances in federalism.
GST Council
A constitutional body (Article 279A) chaired by the Union Finance Minister that makes recommendations on GST rates and thresholds, representing a model of cooperative federalism.
UPSC context
GS Paper II/III (Federalism/Economy): Governance. Evaluates understanding of shared tax sovereignty and revenue-sharing disputes between Centre and States.
Samagra Shiksha Scheme
An integrated Centrally Sponsored Scheme (CSS) for school education (Pre-school to Class XII). Funding is typically shared 60:40 between the Centre and States, often subject to implementation conditions.
UPSC context
GS Paper II (Social Justice/Education): Welfare. Relevant for disputes over central funding conditions and the implementation of the National Education Policy.
Guarantee Redemption Fund (GRF)
An RBI-managed fund into which States must contribute reserves (often 0.5% of GSDP) to cover contingent liabilities arising from state-guaranteed loans, impacting their net borrowing ceilings.
UPSC context
GS Paper III (Economy): Government Budgeting. Tests knowledge of contingent liabilities and the impact of reserve mandates on State fiscal health.
Jal Jeevan Mission (JJM)
A flagship Centrally Sponsored Scheme aimed at providing 55 litres of potable water per capita per day to every rural household through Functional Household Tap Connections.
UPSC context
GS Paper II/III (Governance/Infrastructure): Welfare. Tests understanding of large-scale infrastructure execution and Centre-State cost-sharing dynamics.
Fiscal Federalism
The financial architecture governing the distribution of taxation powers, expenditure responsibilities, and revenue-sharing mechanisms between the Union and State governments in a federation.
UPSC context
GS Paper II/III (Polity/Economy): Core Theme. A foundational concept testing the balance of financial power and autonomy in the Indian Union.
Integrated Goods and Services Tax (IGST)
A tax levied on inter-state supplies of goods and services, collected by the Union and apportioned between the Union and States based on recommendations by the GST Council.
UPSC context
GS Paper III (Economy): Taxation. Focuses on the indirect tax framework and the mechanics of revenue distribution among federal units.
Prelims Trap
States require the Centre's consent for any market borrowing under all circumstances.
States only require consent if there is an outstanding loan/guarantee from the Union. While practically true for all states today, it is constitutionally conditional, not absolute.
Static Concepts Connected
How is State borrowing regulated under the Constitution?
- Article 293(1): States can borrow within the territory of India upon the security of their respective Consolidated Funds.
- Article 293(3): Centre's consent is mandatory for new loans if any part of a previous loan from the Union remains outstanding.
- Article 293(4): The Centre can impose conditions when giving such consent (e.g., mandating state power utility loss absorption).
What is the Guarantee Redemption Fund (GRF)?
- Purpose: A reserve mechanism established in the Public Account to meet contingent liabilities arising from government guarantees.
- Administration: Administered by the RBI on behalf of State governments outside their Consolidated Funds.
- Utility: States can use their GRF balances as collateral to avail of the Special Drawing Facility (SDF) from the RBI.
Cross-Topic Patterns
Net Borrowing Ceiling & Power Sector Reforms
The Centre linking extra borrowing space to power sector reforms (UDAY) forces states to absorb DISCOM losses, severely impacting their debt-to-GSDP optics and sparking federal friction.
GST transition + Off-Budget Borrowing rules
The end of the GST compensation era coupled with the Centre strictly accounting off-budget borrowings as direct State debt severely restricts state fiscal maneuverability.

Expect a multi-statement Prelims question on Article 293 conditions, Guarantee Redemption Fund, and state borrowing constitutional limits.
Linked PYQs · 3
Linked PYQs · 3
- 2025MainsGS2
Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?
- 2024MainsGS2
What changes has the Union Government recently introduced in the domain of Centre-State relations ? Suggest measures to be adopted to build the trust between the Centre and the States and for strengthening federalism.
- 2025PrelimsGS1
Which of the following statements with regard to recommendations of the 15th Finance Commission of India are correct? I. It has recommended grants of ₹ 4,800 crores from the year 2022-23 to the year 2025-26 for incentivizing States to enhance educational outcomes. II. 45% of the net proceeds of Union taxes are to be shared with States. III. ₹ 45,000 crores are to be kept as performance-based incentive for all States for carrying out agricultural reforms. IV. It reintroduced tax effort criteria to reward fiscal performance. Select the correct answer using the code given below.
