Supreme Court criticizes banks over small borrower harassment
Source:Indian Express ↗
Why It Matters
The article highlights an ongoing debate relevant to the GS3 Economy syllabus—systemic inequality in credit access and recovery. The stark contrast between handling large corporate NPAs and aggressive recovery from small borrowers touches upon both economic efficiency (NPA crisis) and social equity (financial inclusion and inclusive growth).
Summary
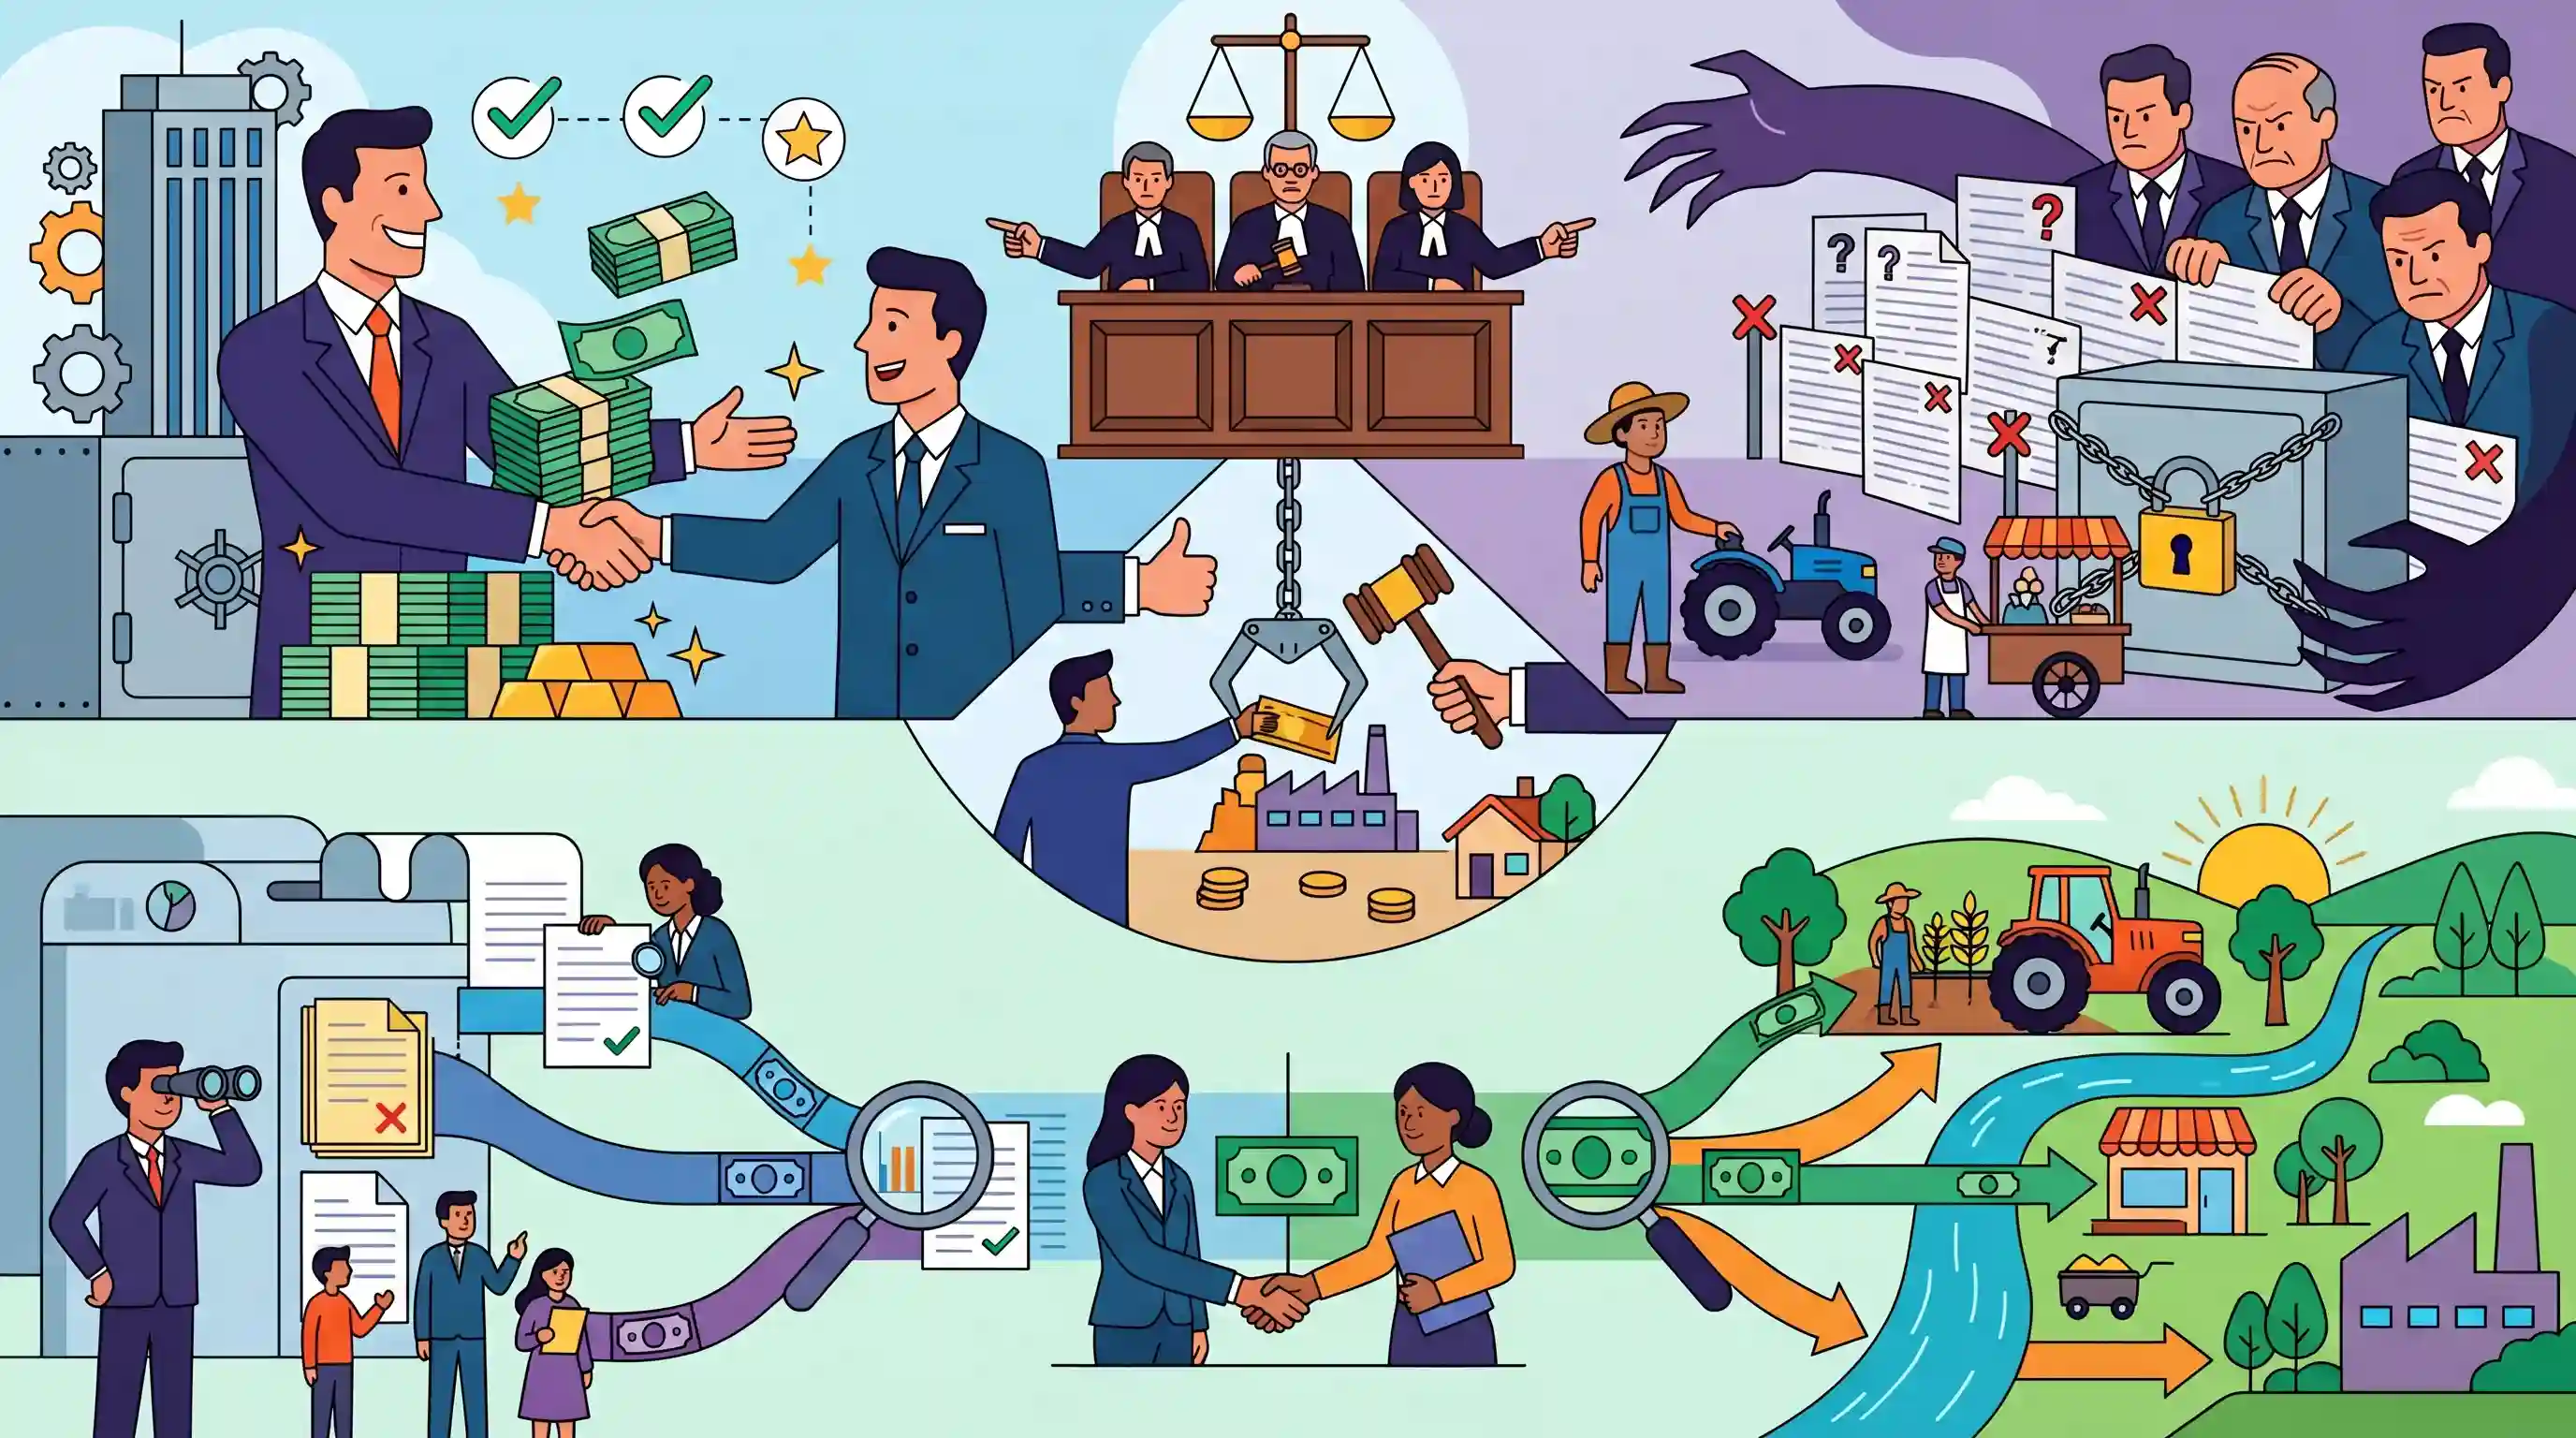
The Supreme Court of India recently highlighted systemic disparities in the banking sector, observing that banks are often "casual" when lending thousands of crores to big business groups but resort to stringent conditions and "borderline harassment" when dealing with small borrowers. The remarks by a bench of Justices Surya Kant and K V Viswanathan came while upholding SBI's recovery proceedings under the SARFAESI Act against a firm that defaulted on a Rs 8-crore loan shortly after it was granted. While affirming the legal recovery process through Debt Recovery Tribunals (DRT), the Court emphasized that banks must properly assess borrowers' repayment capacity at the outset to prevent immediate defaults, and called for fairer, less harassing procedures for retail and agricultural borrowers.
Key Points
- The Supreme Court criticized banks for displaying a casual approach when issuing massive loans to large corporates, while subjecting small borrowers like farmers and retail consumers to borderline harassment.
- The observations were made during a case where SBI invoked the SARFAESI Act to recover a Rs 8-crore loan from a firm that defaulted within months of the loan's sanction.
- The SC upheld the bank's recovery proceedings and the orders of the Debt Recovery Tribunal, emphasizing the need for banks to rigorously assess repayment capacity before sanctioning funds.
- The Court's remarks spotlight a systemic disparity in India's credit recovery mechanisms, pointing to the lenient treatment often afforded to mega-defaulters (NPAs) versus the stringent enforcement faced by small borrowers.
Important Terms
SARFAESI Act, 2002

Enacted in 2002, it empowers banks to recover bad loans by seizing and selling secured assets without court intervention once an account is classified as a Non-Performing Asset (NPA).
UPSC context
GS-III: Indian Economy (Banking & NPAs); tested on legal mechanisms for debt recovery and financial sector reforms.
Debt Recovery Tribunal (DRT)
A quasi-judicial body established under the 1993 RDB Act to provide speedy adjudication and recovery of debts owed to banks and financial institutions for claims exceeding ₹20 lakh.
UPSC context
GS-II/GS-III: Governance and Statutory Bodies; focuses on specialized tribunals vs. civil courts for financial dispute resolution.
Debt Recovery Appellate Tribunal (DRAT)
The designated appellate authority established under the 1993 RDB Act to hear and decide appeals filed against the orders of Debt Recovery Tribunals (DRTs).
UPSC context
GS-II: Judiciary & Statutory Bodies; tests knowledge of hierarchical tribunal structures and procedural requirements like pre-deposits.
Non-Performing Asset (NPA)
A classification for bank loans or advances where the principal or interest payment has remained overdue for a period of 90 days or more.
UPSC context
GS-III: Indian Economy; critical for topics on banking health, credit growth, and fiscal stability.
State Bank of India (SBI)
India's largest public sector bank; it plays a central role in government financial schemes and is frequently the lead respondent in debt recovery litigations.
UPSC context
GS-III: Banking Sector; relevant for discussions on Public Sector Banks (PSBs), financial inclusion, and corporate governance.
Prelims Trap
Banks can invoke the SARFAESI Act to seize and auction agricultural land if a farmer defaults on a loan.
Section 31(i) of the SARFAESI Act explicitly exempts agricultural land. Banks cannot use SARFAESI provisions to confiscate or auction agricultural land to recover defaulted loans.
Static Concepts Connected
What are the key provisions and limitations of the SARFAESI Act, 2002?
- Bypassing Courts: Allows secured creditors (banks/FIs) to take possession of collateral and sell it without the intervention of civil courts.
- Key Exemptions: The Act does not apply to unsecured loans, outstanding loans below ₹1 lakh, or agricultural land.
- Appellate Mechanism: Borrowers aggrieved by bank actions under SARFAESI can appeal to Debt Recovery Tribunals (DRTs) and subsequently to the DRAT.
What is the 'Twin Balance Sheet' problem in the Indian economy?
- Dual Distress: A structural macroeconomic challenge where heavily indebted corporate groups and severely NPA-stressed commercial banks coexist, feeding into each other's distress.
- Credit Stagnation: Stressed bank balance sheets lead to risk aversion, causing credit stagnation for productive sectors while banks simultaneously struggle to recover massive corporate defaults.
Cross-Topic Patterns
IBC haircuts vs SARFAESI recovery
The SC's note on big-ticket leniency highlights a contrast with the Insolvency and Bankruptcy Code (IBC), where banks frequently accept massive 'haircuts' to resolve large corporate insolvencies, unlike strict retail recoveries.
Priority Sector Lending (PSL) friction
Stringent recovery and harassment in small-borrower segments undermine Priority Sector Lending (PSL) goals, risking a reversal of financial inclusion by pushing farmers back to informal moneylenders.

Expect a 2026 Prelims statement question testing SARFAESI exemptions (like agricultural land) mixed with DRT jurisdictions and IBC.
Linked PYQs · 3
Linked PYQs · 3
- 2024PrelimsGS1
Consider the following statements : Statement-I : Syndicated lending spreads the risk of borrower default across multiple lenders. Statement-II : The syndicated loan can be a fixed amount/lump sum of funds, but cannot be a credit line. Which one of the following is correct in respect of the above statements?
- 2022MainsGS3
Is inclusive growth possible under market economy ? State the significance of financial inclusion in achieving economic growth in India.
- 2024PrelimsGS1
With reference to the Pradhan Mantri Jan Dhan Yojana (PMJDY), which of the following statements is/are correct? 1. The scheme aims to open bank accounts for unbanked households. 2. There is a minimum balance requirement for accounts opened under this scheme. 3. Beneficiaries get a Rupay Debit Card with an inbuilt accident insurance cover. Select the correct answer using the code given below.
