Monetary Policy Transmission and Commercial Bank Rate Cuts
Source:The Hindu ↗
Why It Matters
This article is a classic, practical example of 'Monetary Policy Transmission', a recurring theme in UPSC Prelims and Mains. It illustrates how RBI's repo rate cuts (facilitated by controlled CPI inflation) are passed down to retail borrowers via EBLR/MCLR and to savers via deposit rates. It also highlights a critical structural economic issue: the 'financialization of savings' where households shift money from bank deposits to capital markets, which affects banking liquidity and credit growth.
Summary
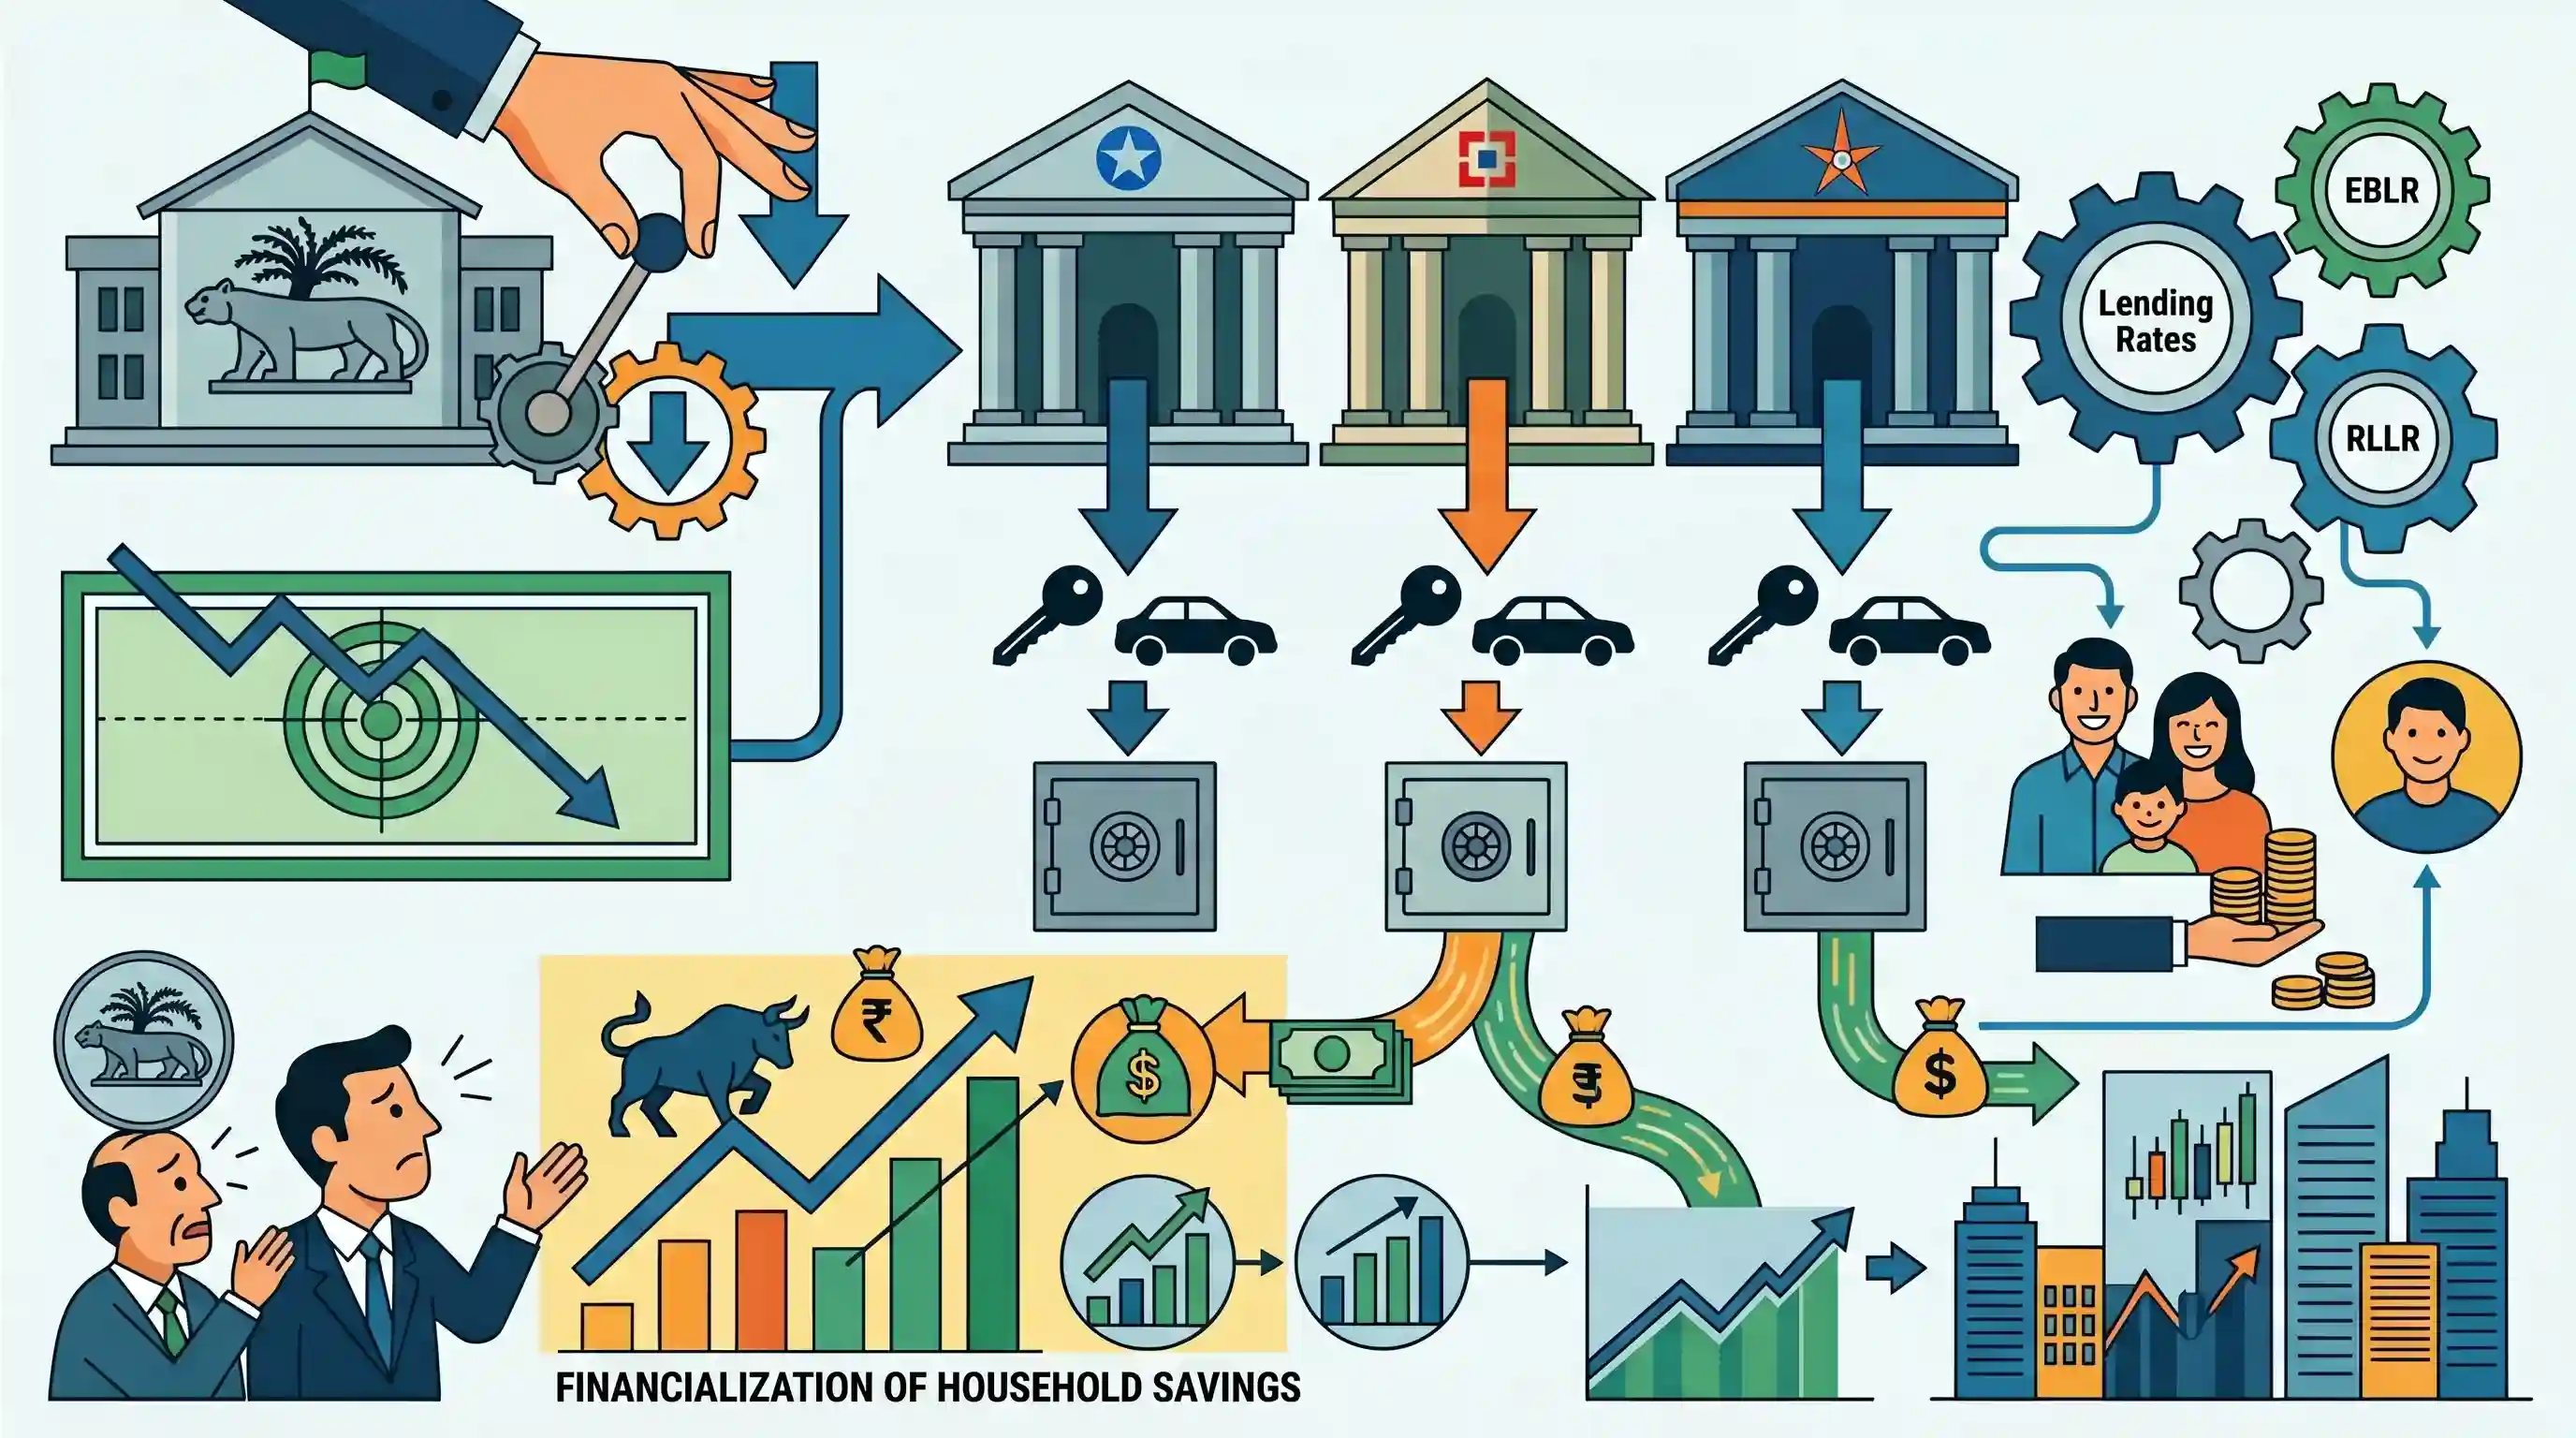
Major Indian banks (SBI, HDFC, Bank of India) have reduced both lending and deposit rates following the RBI's recent 50 basis points cut in the benchmark repo rate. The adjustments include reductions in External Benchmark Lending Rates (EBLR) and Repo-Linked Lending Rates (RLLR), which will successfully transmit monetary easing to borrowers by lowering EMIs. However, the accompanying cut in deposit rates comes at a time when the RBI and Finance Ministry have flagged concerns about a structural shift of household financial savings away from traditional banks towards capital markets and mutual funds. The RBI's consecutive rate cuts were made possible by retail consumer price inflation (CPI) remaining comfortably within its 4% target zone.
Key Points
- Major banks like SBI reduced their External Benchmark Lending Rates (EBLR) and Repo-Linked Lending Rates (RLLR) by 25 basis points, directly lowering borrowing costs and EMIs for retail loans.
- Deposit rates for savings accounts and fixed deposits were also reduced by HDFC Bank, Bank of India, and SBI, impacting overall returns for savers and senior citizens.
- The banking rate adjustments follow the RBI's recent cumulative repo rate cut of 50 basis points (bringing the policy rate down to 6%), facilitated by retail inflation stabilizing within the 4% target area.
- The reduction in bank deposit rates occurs against the backdrop of a structural shift in the Indian economy, where household financial savings are increasingly migrating from traditional bank deposits to market-based instruments like mutual funds.
Important Terms
External Benchmark Lending Rate (EBLR)

A framework introduced by the RBI in 2019 requiring banks to link floating-rate loans to external, market-linked benchmarks (like the repo rate) to ensure transparent and rapid interest rate adjustments.
UPSC context
GS Paper III (Economy): Banking reforms and monetary policy transmission; essential for understanding how RBI rate cuts impact the common man.
Marginal Cost of Funds based Lending Rate (MCLR)
The internal reference rate introduced in 2016, calculated based on a bank’s incremental cost of funds. It is slower than EBLR in transmitting policy rate changes to borrowers.
UPSC context
GS Paper III: Evolution of banking benchmarks; often compared with EBLR in Prelims/Mains to test understanding of monetary policy effectiveness.
Monetary Policy Transmission
The process through which a central bank's policy rate changes (e.g., Repo Rate) are passed through the financial system to influence lending rates, spending, and inflation.
UPSC context
GS Paper III: Central to discussing RBI's role in economic stability and the challenges posed by rigid bank lending structures.
Financialization of Household Savings
A structural shift where household wealth moves from physical assets (gold, real estate) into financial instruments like bank deposits, mutual funds, and equities.
UPSC context
GS Paper III: Key economic trend regarding domestic capital formation and its impact on the banking sector versus capital markets.
Repo-Linked Lending Rate (RLLR)
A specific EBLR where a bank's floating lending rate is directly calculated as the RBI's repo rate plus a fixed margin (spread).
UPSC context
GS Paper III: Applied knowledge of how RBI's repo rate cuts immediately translate to lower EMIs for retail borrowers.
Inflation Targeting Framework
A policy framework where the RBI prioritizes maintaining headline inflation (CPI) within a target range (4% ±2%) to ensure price stability while supporting growth.
UPSC context
GS Paper III: Mandate of the Monetary Policy Committee (MPC); frequently tested in the context of RBI’s dual mandate of growth and stability.
Prelims Trap
RBI mandates commercial banks to link both floating-rate loans and term deposits to an external benchmark.
RBI mandated EBLR only for floating rate retail and MSME loans. Deposit rates are fully deregulated and set by individual bank boards, not legally tied to external benchmarks.
Static Concepts Connected
What is the External Benchmark Lending Rate (EBLR) framework?
- Objective: Introduced in 2019 to replace the internal MCLR system, ensuring faster and more transparent transmission of RBI's policy rate changes directly to borrowers.
- Applicability: It is mandatory for all new floating-rate personal or retail loans (e.g., home, auto) and floating-rate loans to Micro, Small and Medium Enterprises (MSMEs).
- Allowed benchmarks: Banks can link loans to the RBI Repo rate, or the 3-month/6-month Treasury Bill yields published by the Financial Benchmarks India Private Ltd (FBIL).
What drives the 'Financialization of Household Savings'?
- Definition: It is the structural macroeconomic shift of household savings moving from physical assets (like gold and real estate) into formal financial instruments.
- Current shift: Within financial assets, savers are now actively shifting away from traditional bank fixed deposits towards market-linked instruments like mutual funds, equities, and SIPs.
- Banking impact: This migration deprives commercial banks of cheap low-cost CASA deposits, creating a mismatch between robust credit growth and sluggish deposit mobilization.
Cross-Topic Patterns
Monetary transmission vs Bank Liquidity
As household savings migrate to mutual funds, banks face structural liquidity pressure. This forces them to hike deposit rates to attract funds, sometimes conflicting with RBI's repo rate cut transmission goals.
Financialization and Real Interest Rates
When RBI cuts rates, the real interest rate on fixed deposits shrinks. This naturally pushes retail investors toward capital markets for inflation-beating returns, accelerating the financialization of savings.

Expect a 2026 prelims question linking EBLR transmission mandates with the ongoing structural decline in Net Household Financial Savings.
Linked PYQs · 3
Linked PYQs · 3
- 2016PrelimsGS1
What is/are the purpose/purposes of the 'Marginal Cost of Funds based Lending Rate (MCLR)' announced by RBI? 1. These guidelines help improve the transparency in the methodology followed by banks for determining the interest rates on advances. 2. These guidelines help ensure availability of bank credit at interest rates which are fair to the borrowers as well as the banks. Select the correct answer using the code given below.
- 2017PrelimsGS1
Which of the following statements is/are correct regarding the Monetary Policy Committee (MPC)? 1. It decides the RBI's benchmark interest rates. 2. It is a 12-member body including the Governor of RBI and is reconstituted every year. 3. It functions under the chairmanship of the Union Finance Minister. Select the correct answer using the code given below:
- 2020PrelimsGS1
Consider the following statements: 1. The weightage of food in Consumer Price Index (CPI) is higher than that in Wholesale Price Index (WPI). 2. The WPI does not capture changes in the prices of services, which CPI does. 3. Reserve Bank of India has now adopted WPI as its key measure of inflation and to decide on changing the key policy rates. Which of the statements given above is/are correct?
