Legal and regulatory status of socio-cultural organizations
Source:The Hindu ↗
Why It Matters
The article highlights the legal nuances of organizational structures in India, specifically the 'body of individuals' status versus formal registration under acts like the Societies Registration Act. It is relevant for understanding the governance framework, tax exemptions for socio-cultural groups, and the historical context of organizations established during the British era.
Summary
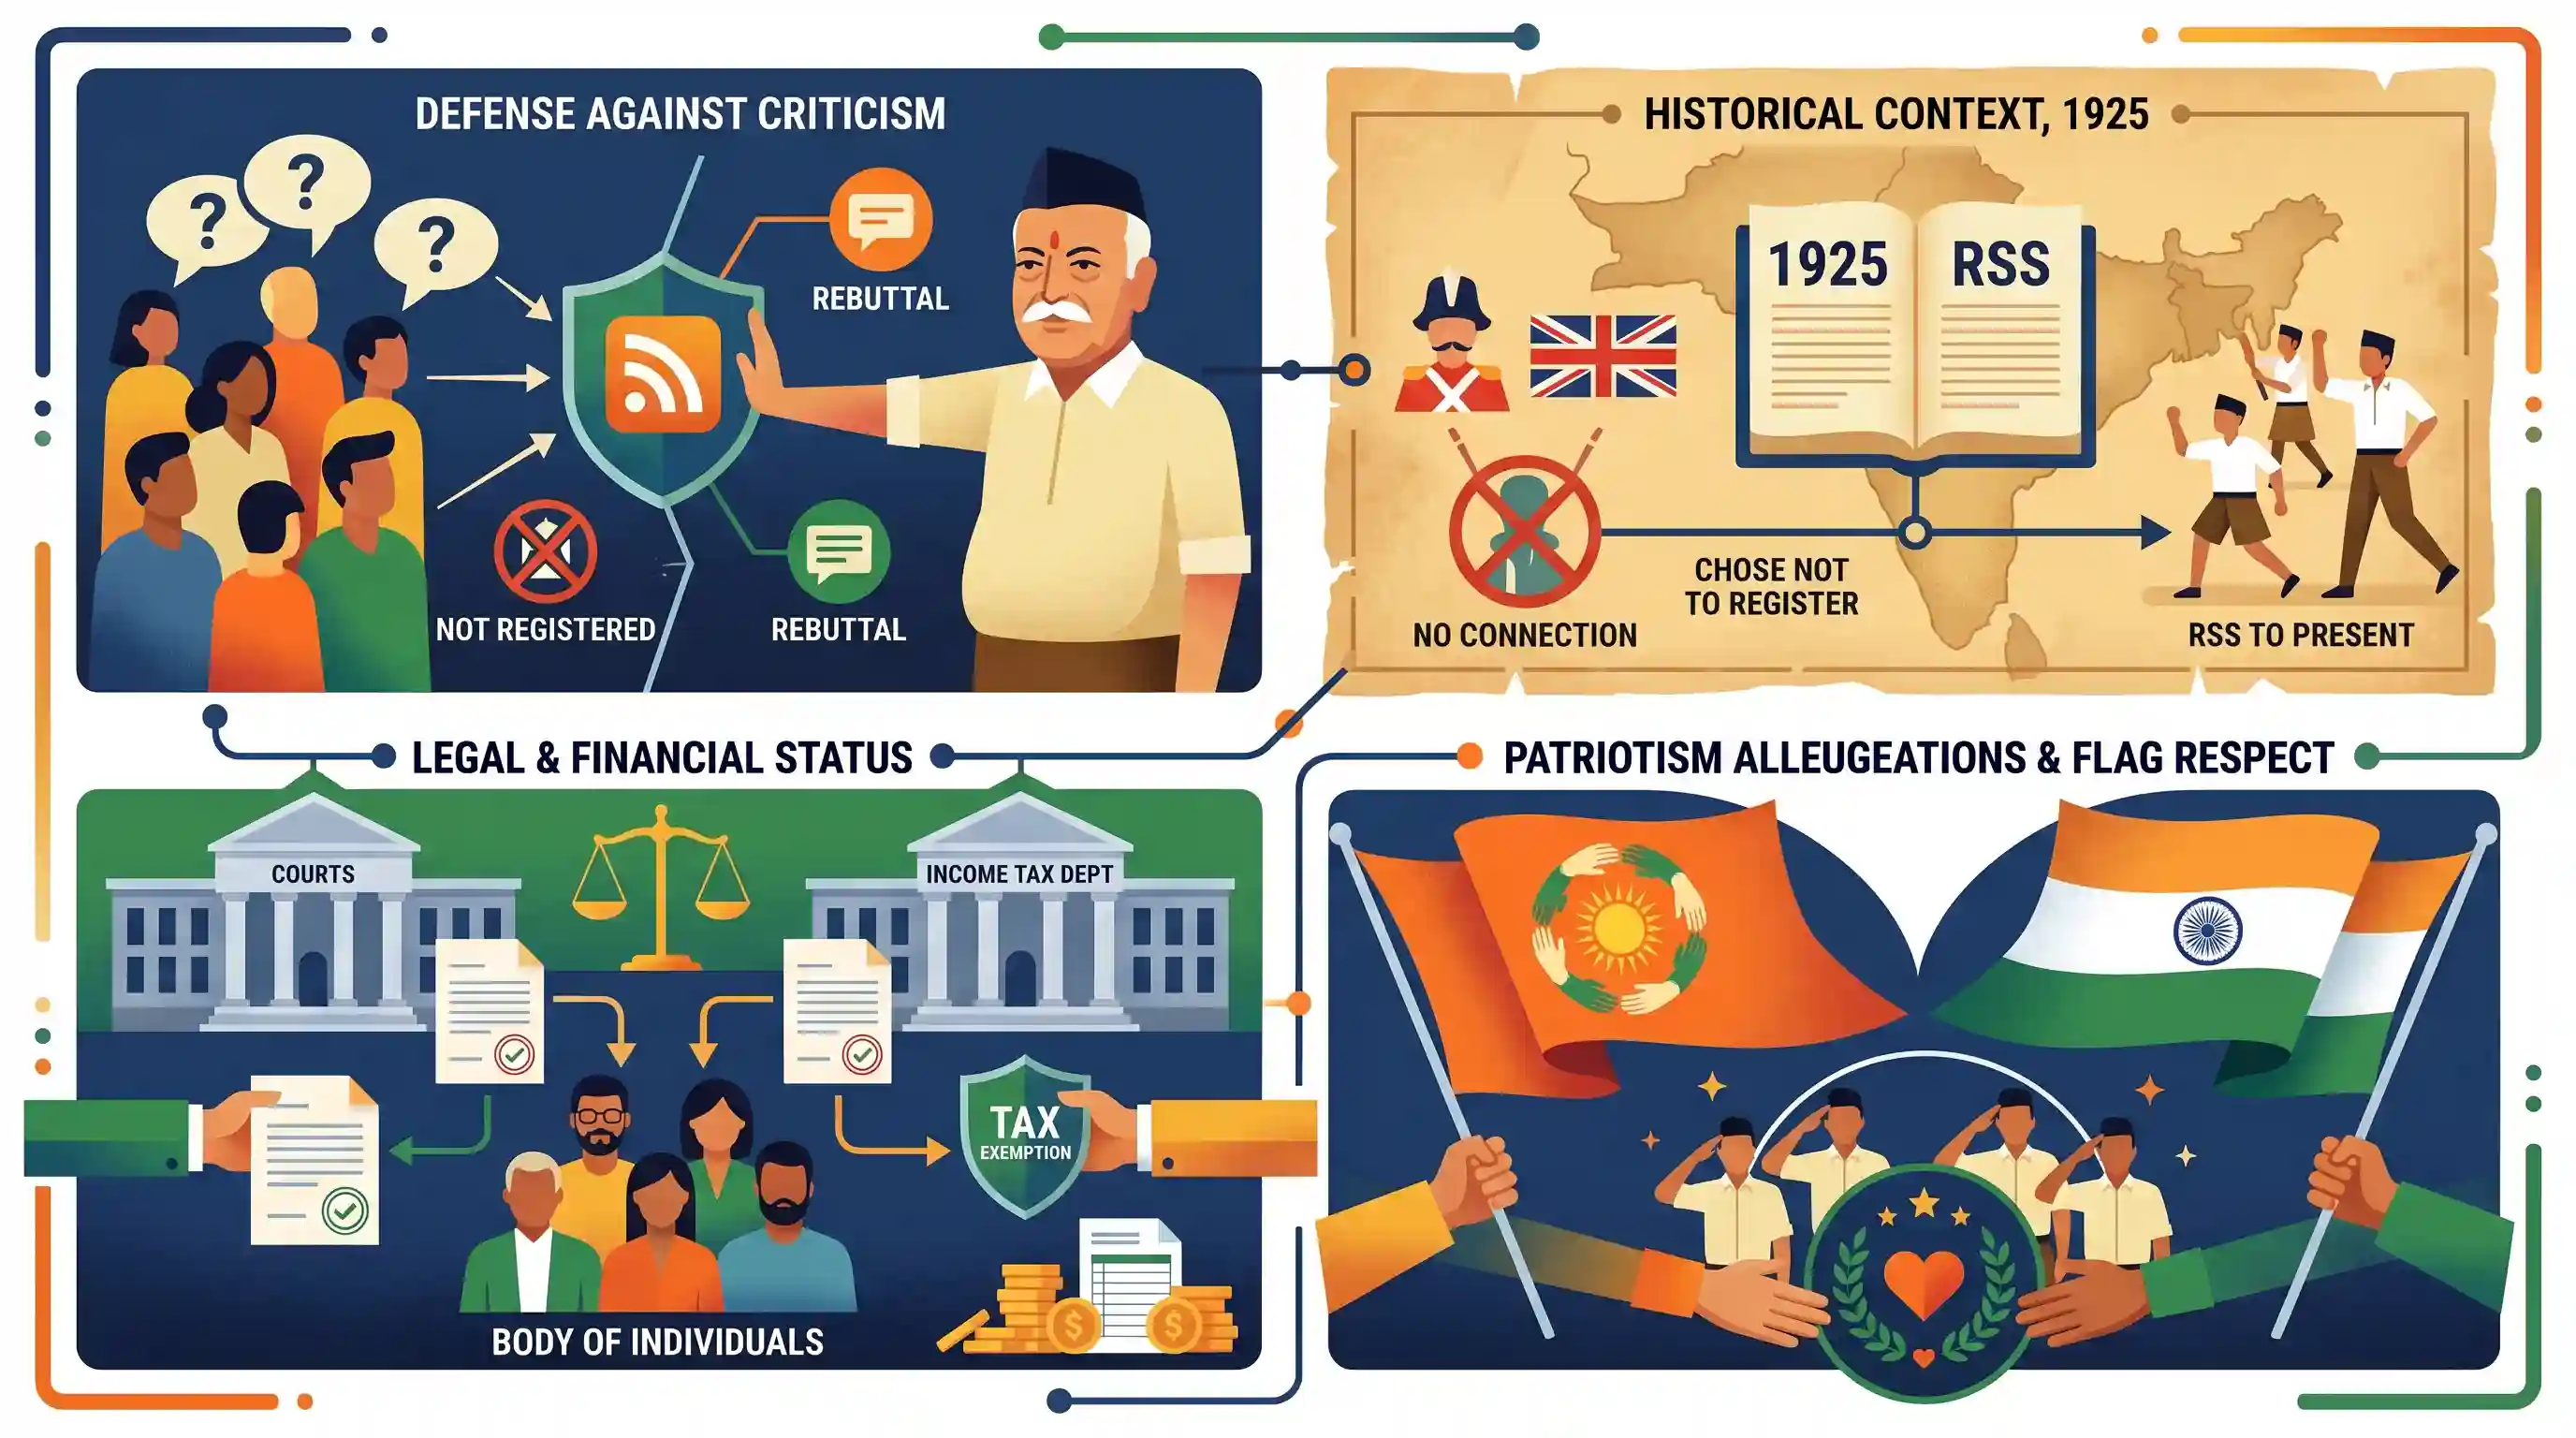
RSS Chief Mohan Bhagwat defended the organization against criticism from Congress leaders who questioned its lack of formal registration. Bhagwat clarified that since its inception in 1925, the RSS chose not to register with the British government. However, it is legally recognized by the courts and the Income Tax Department as a 'body of individuals' and is granted income tax exemption. He also rebutted allegations regarding the RSS's patriotism by emphasizing its respect for the national tricolour alongside the saffron flag.
Key Points
- RSS Chief Mohan Bhagwat addressed criticism regarding the organization's lack of formal registration.
- He stated that the RSS is legally recognized by courts and the Income Tax Department as a 'body of individuals' and is exempt from income tax.
- Founded in 1925, the RSS intentionally avoided registration under the British colonial government.
- Bhagwat also countered claims that the RSS only honors the saffron flag, asserting its deep respect for the Indian tricolour.
Important Terms
Body of Individuals (BOI)

A group of individuals who come together for a common purpose or to earn income. It is recognized as a 'person' under Indian tax law.
UPSC context
GS Paper III (Economy/Taxation); GS Paper II (Polity). Tests knowledge of legal personhood and assessable entities under tax laws.
Societies Registration Act, 1860
An 1860 law allowing the registration of literary, scientific, and charitable societies to give them legal standing and enable government oversight.
UPSC context
GS Paper II (Governance). Crucial for understanding the regulatory framework of Civil Society Organizations and NGOs in India.
Income Tax Act, 1961
The comprehensive law governing the levy, administration, and collection of income tax in India, defining various taxable entities and exemptions.
UPSC context
GS Paper III (Economy). Tests understanding of fiscal policy, tax exemptions, and the statutory classification of different organizations.
Section 2(31) of the Income Tax Act
The specific clause of the Income Tax Act that defines a 'person' to include individuals, HUFs, companies, firms, AOPs, and Bodies of Individuals.
UPSC context
GS Paper III (Economy). Important for technical questions on tax jurisdiction and the legal definitions of taxpayers.
Association of Persons (AOP)
An organization consisting of two or more individuals (natural or artificial) working toward a common goal, often with a profit motive.
UPSC context
GS Paper III (Economy). Frequently contrasted with BOI; tests precise knowledge of organizational forms in Indian business and tax law.
Rashtriya Swayamsevak Sangh (RSS)
A right-wing, Hindu nationalist volunteer organization founded in 1925, which operates as a 'body of individuals' rather than a registered society.
UPSC context
GS Paper I (Modern Indian History) & GS Paper II (Polity). Relevant for studying social organizations and ideological movements in India.
Prelims Trap
An organization must be formally registered under the Societies Registration Act to be assessed for income tax.
The Income Tax Act, 1961 recognizes unregistered entities, assessing them legally as an 'Association of Persons' or 'Body of Individuals' without formal incorporation.
Static Concepts Connected
What differentiates a Body of Individuals (BOI) from an Association of Persons (AOP)?
- BOI composition: Exclusively comprises individuals (natural persons) grouped together, not necessarily through a formal contract or common will.
- AOP composition: Can include non-individuals (companies, firms, trusts) joining voluntarily for a common purpose to produce income.
- Tax recognition: Both are defined as a "person" under Section 2(31) of the Income Tax Act without needing formal incorporation.
What are the legal protections and rights concerning the Indian National Flag?
- Fundamental Duty: Article 51A(a) mandates citizens to respect the National Flag and the National Anthem.
- Fundamental Right: In 2004, the Supreme Court declared that hoisting the flag with dignity is a protected freedom of speech right under Article 19(1)(a).
- Statutory Penalties: The Prevention of Insults to National Honour Act, 1971 criminalizes intentional disrespect or desecration of the flag.
Cross-Topic Patterns
Civil society structures and taxation
UPSC regularly tests the legal definitions of NGOs (Trusts, Societies, Section 8 companies) and how these structures interact with state-level laws, FCRA restrictions, and Income Tax exemptions.
Colonial-era laws governing modern NGOs
The reliance on the Societies Registration Act, 1860 highlights how pre-independence regulatory frameworks still govern the majority of India's non-profit and civil society sector today.

A Prelims statement distinguishing between formal NGO registration and statutory tax recognition via 'Body of Individuals' is highly likely.
Linked PYQs · 3
Linked PYQs · 3
- 2025MainsGS2
Civil Society Organizations are often perceived as being anti-State actors than non-State actors. Do you agree? Justify.
- 2021MainsGS2
Can Civil Society and Non-Governmental Organizations present an alternative model of public service delivery to benefit the common citizen? Discuss the challenges of this alternative model.
- 2023MainsGS2
Discuss the contribution of civil society groups for women's effective and meaningful participation and representation in state legislatures in India.
