Finance Act Retrospective Taxation and Constitutional Validity Issues
Source:The Hindu ↗
Why It Matters
The issue highlights the critical friction between legislative intent regarding taxation (retrospective amendments) and constitutional safeguards (separation of powers, basic structure, and Seventh Schedule lists). It is highly relevant for GS Paper 2 (Constitutional provisions, basic structure, distribution of powers) and GS Paper 3 (Taxation policies).
Summary
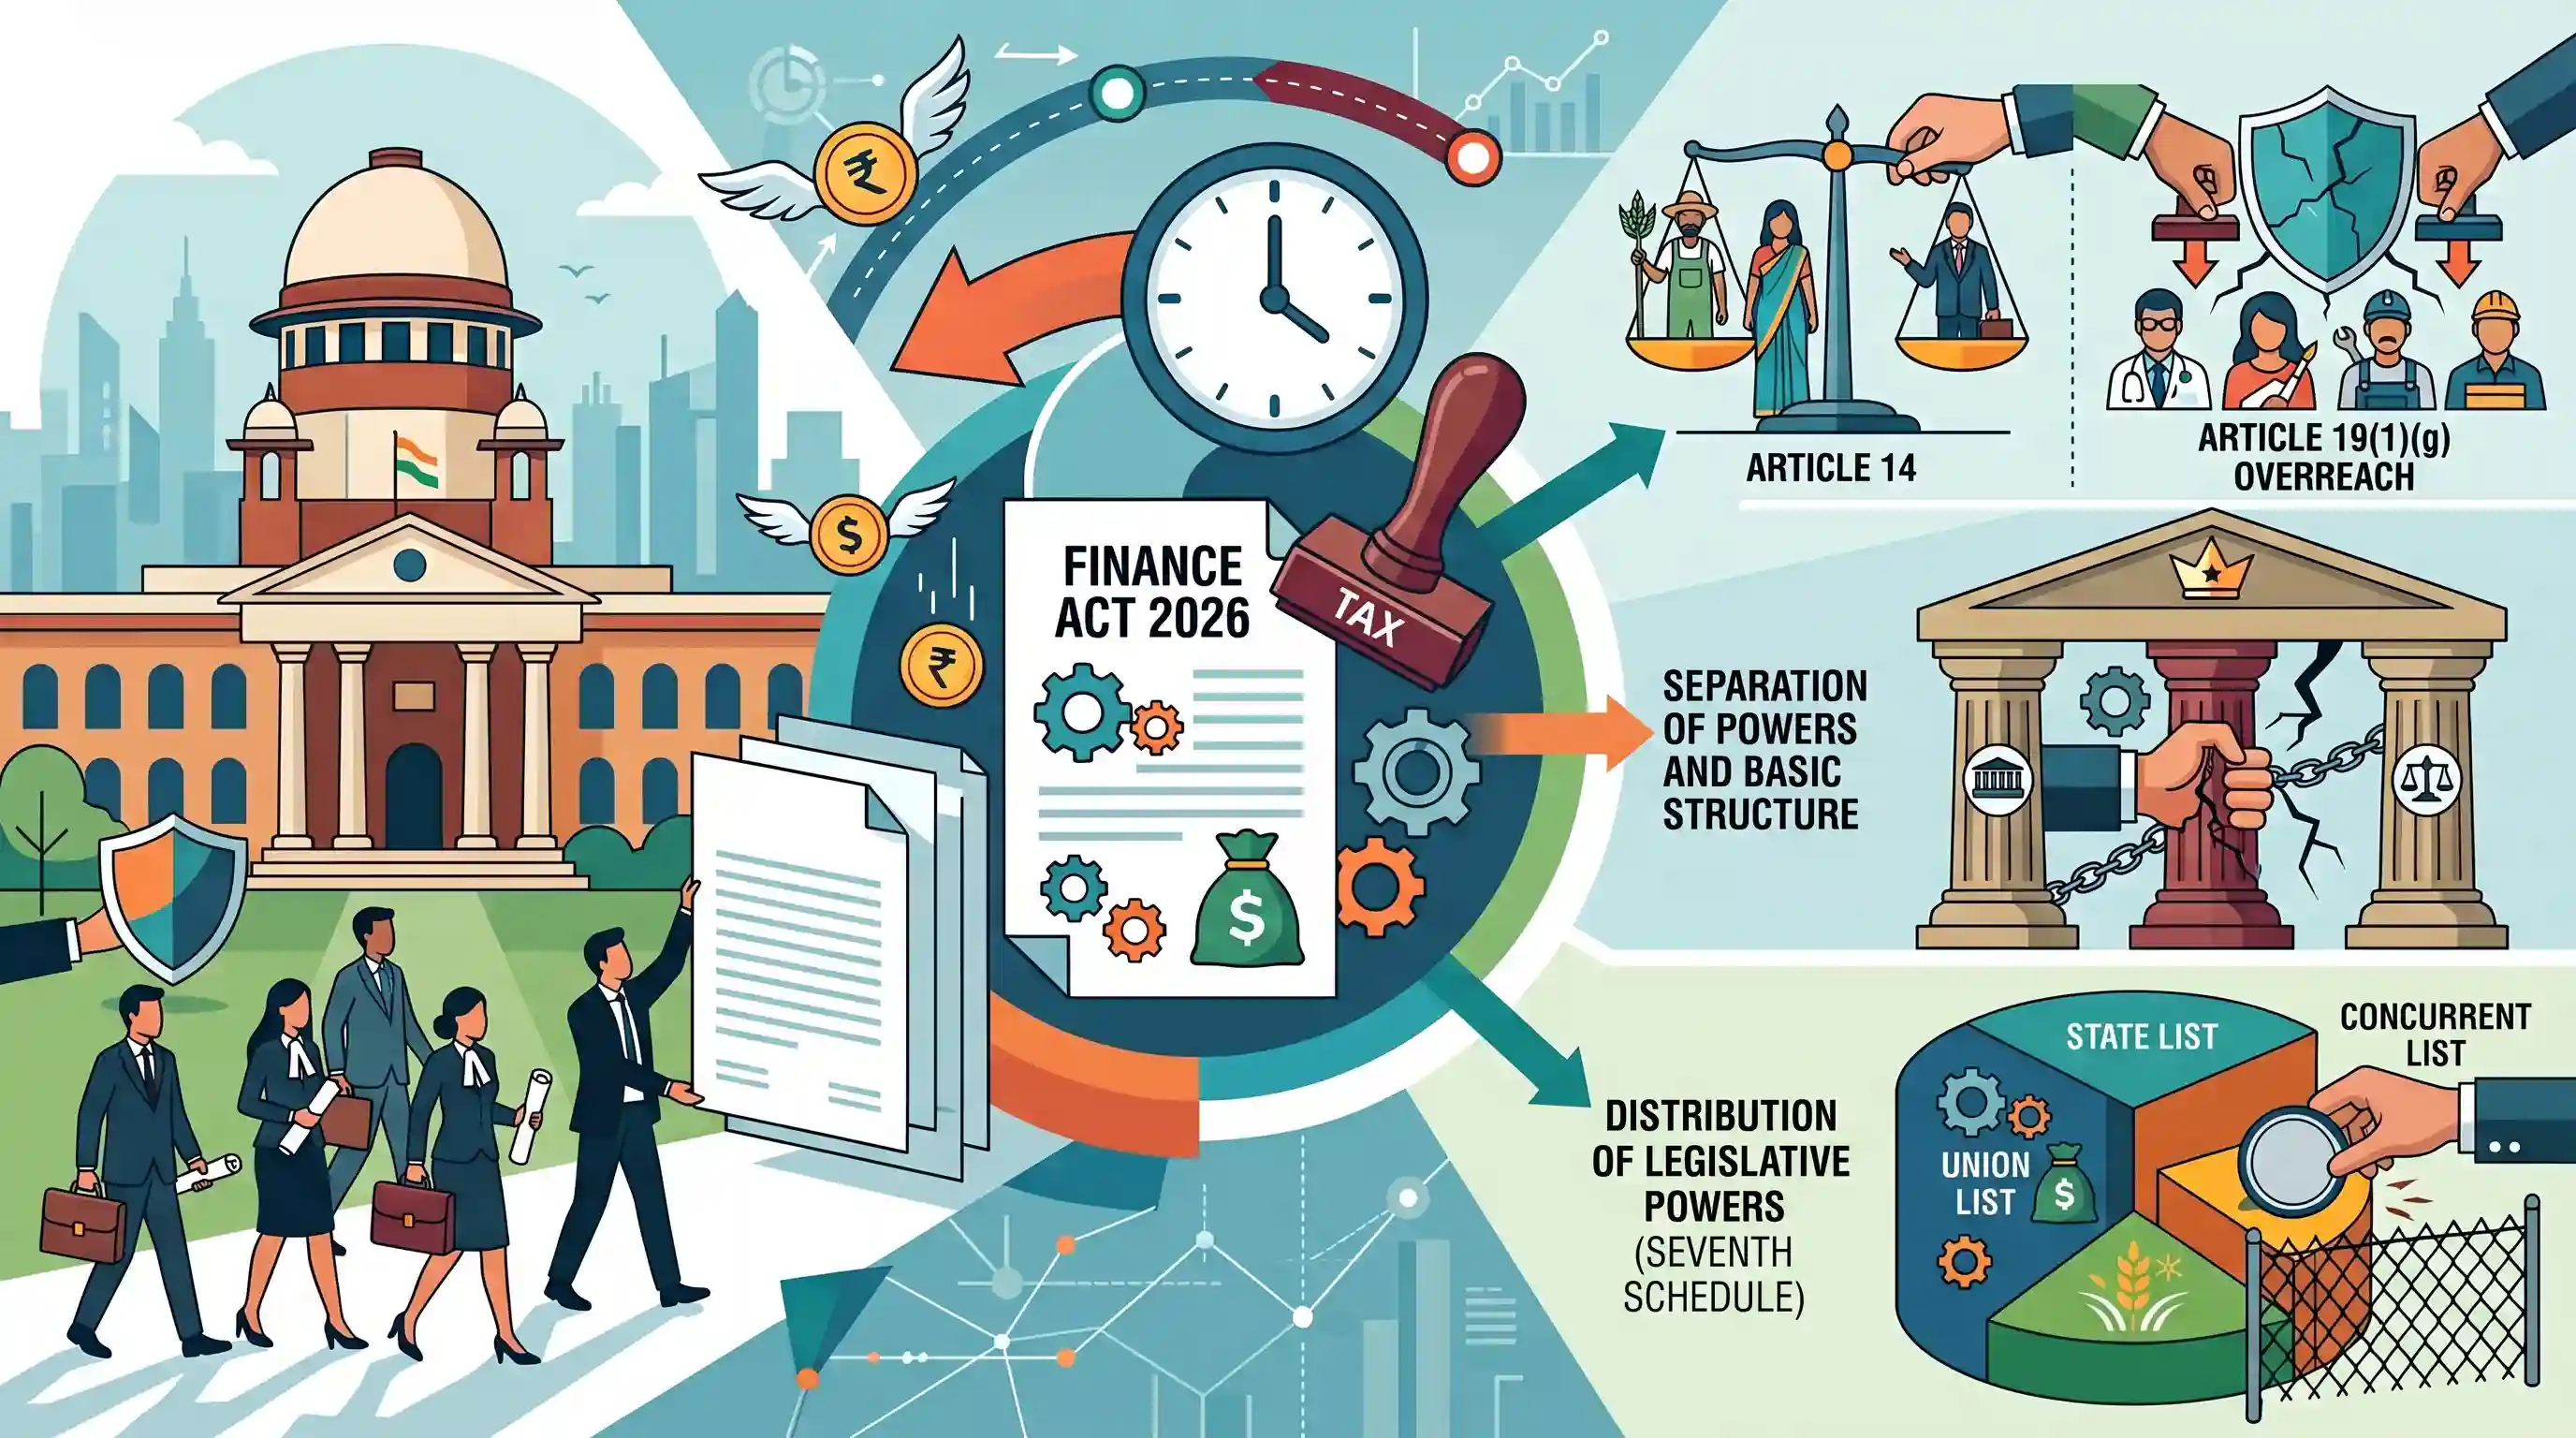
The Revenue Bar Association in Chennai has challenged the constitutional validity of several provisions introduced by the Finance Act, 2026 into the Income Tax Act, 1961. The petition filed in the Madras High Court argues that these provisions, which enforce retrospective taxation from April 1, 2025, violate the basic structure of the Constitution, the separation of powers, and Fundamental Rights under Articles 14 and 19(1)(g). Furthermore, the petitioners claim the amendments transgress legislative boundaries laid out in Articles 245 and 246, specifically conflicting with Entry 82 of the Union List concerning the taxation of agricultural income.
Key Points
- The Revenue Bar Association (RBA) in Chennai has filed a petition challenging the constitutional validity of multiple provisions of the Finance Act, 2026.
- The petition contests retrospective amendments made to the Income Tax Act, 1961, which came into effect from April 1, 2025.
- The RBA contends that the provisions violate the basic structure of the Constitution, the doctrine of separation of powers, and Fundamental Rights under Articles 14 and 19(1)(g).
- The amendments are also challenged for allegedly transgressing legislative powers under Articles 245 and 246, specifically overstepping into domains restricted by Entry 82 of List I (taxes on agricultural income).
Important Terms
Finance Act

An annual legislation that gives effect to the financial proposals of the Central Government, including changes in tax rates and administrative provisions for the upcoming fiscal year.
UPSC context
GS Paper III (Economy/Budgeting); tests understanding of the legislative process for implementing fiscal policy and taxation changes.
Revenue Bar Association (RBA)
A professional body of advocates specializing in tax and revenue law, often acting as a stakeholder in legal challenges against fiscal regulations and procedural tax amendments.
UPSC context
GS Paper II (Governance); relevant for understanding the role of professional associations and civil society in judicial review.
Retrospective Taxation
The application of tax laws to transactions or income generated in the past, effectively changing the tax liability for periods prior to the law's enactment.
UPSC context
GS Paper III (Economy); tests knowledge of tax certainty, investor confidence, and the government's power to nullify judicial rulings.
Entry 82, Union List
A provision in the Seventh Schedule of the Indian Constitution granting Parliament the power to levy taxes on income other than agricultural income.
UPSC context
GS Paper II (Polity/Federalism); crucial for understanding the distribution of legislative and taxing powers between the Union and States.
Separation of Powers
A constitutional principle where the legislative, executive, and judicial branches have distinct powers and provide checks and balances to prevent any single organ from overreaching.
UPSC context
GS Paper II (Constitution); essential for analyzing the validity of laws that attempt to override judicial verdicts retrospectively.
Basic Structure Doctrine
A judicial principle establishing that Parliament cannot amend certain fundamental features of the Constitution, such as the rule of law and judicial review.
UPSC context
GS Paper II (Constitution); the ultimate standard for judicial review of constitutional amendments and legislative provisions.
Prelims Trap
Parliament has no constitutional power to enact retrospective taxation laws under any circumstances.
Parliament has plenary power to enact retrospective tax laws. However, they must survive Article 14 scrutiny and cannot simply overrule a court judgment without curing the underlying statutory defect.
Static Concepts Connected
How is the taxation of agricultural income divided under the Seventh Schedule?
- Union List (Entry 82): Empowers the Union government to levy taxes on income, strictly excluding agricultural income.
- State List (Entry 46): Grants State Legislatures the exclusive power to levy taxes on agricultural income.
- Definitional control: Parliament defines what constitutes 'agricultural income' under the Income Tax Act, thereby indirectly influencing the scope of the State's taxing power.
What are the constitutional limits on Parliament's retrospective taxation powers?
- Article 14 scrutiny: Retrospective tax laws are not immune to Fundamental Rights and can be struck down if deemed 'manifestly arbitrary' or discriminatory.
- Curing legal defects: The legislature can retrospectively amend a statute to cure legal defects pointed out by courts, known as 'validating acts'.
- Separation of powers: A legislature violates this basic structure doctrine if it merely declares a court judgment invalid without altering the underlying statutory text.
Cross-Topic Patterns
Retrospective Tax & BIT Arbitrations
Retrospective tax disputes (e.g., Vodafone, Cairn) previously triggered international arbitration under Bilateral Investment Treaties (BITs), linking domestic Article 14 constitutional limitations directly to international economic diplomacy.
Agriculture Tax & Fiscal Federalism
Debates on broadening India's tax base frequently collide with the 7th Schedule. Entry 82 restricts Union taxation on agricultural income, serving as a friction point in Centre-State fiscal federalism.

A multi-statement Prelims question merging 7th Schedule tax entries (Entry 82 vs 46) and the limits of retrospective taxation is highly likely.
Linked PYQs · 3
Linked PYQs · 3
- 2020MainsGS2
Judicial Legislation is antithetical to the doctrine of separation of powers as envisaged in the Indian Constitution. In this context justify the filing of large number of public interest petitions praying for issuing guidelines to executive authorities.
- 2025PrelimsGS1
Consider the following statements : Statement I: In India, income from allied agricultural activities like poultry farming and wool rearing in rural areas is exempted from any tax. Statement II: In India, rural agricultural land is not considered a capital asset under the provisions of the Income-tax Act, 1961. Which one of the following is correct in respect of the above statements?
- 2025MainsGS2
"Constitutional morality is the fulcrum which acts as an essential check upon the high functionaries and citizens alike...." In view of the above observation of the Supreme Court, explain the concept of constitutional morality and its application to ensure balance between judicial independence and judicial accountability in India.
