RBI Stress Tests and Projected Gross NPA Trends in Banks
Source:Indian Express ↗
Why It Matters
The health of the banking sector is a recurring theme in UPSC GS-3 (Indian Economy). Understanding the concepts of NPAs, stress testing, and the RBI's role in maintaining financial stability is crucial for addressing both Prelims conceptual questions and Mains analytical questions regarding economic resilience.
Summary
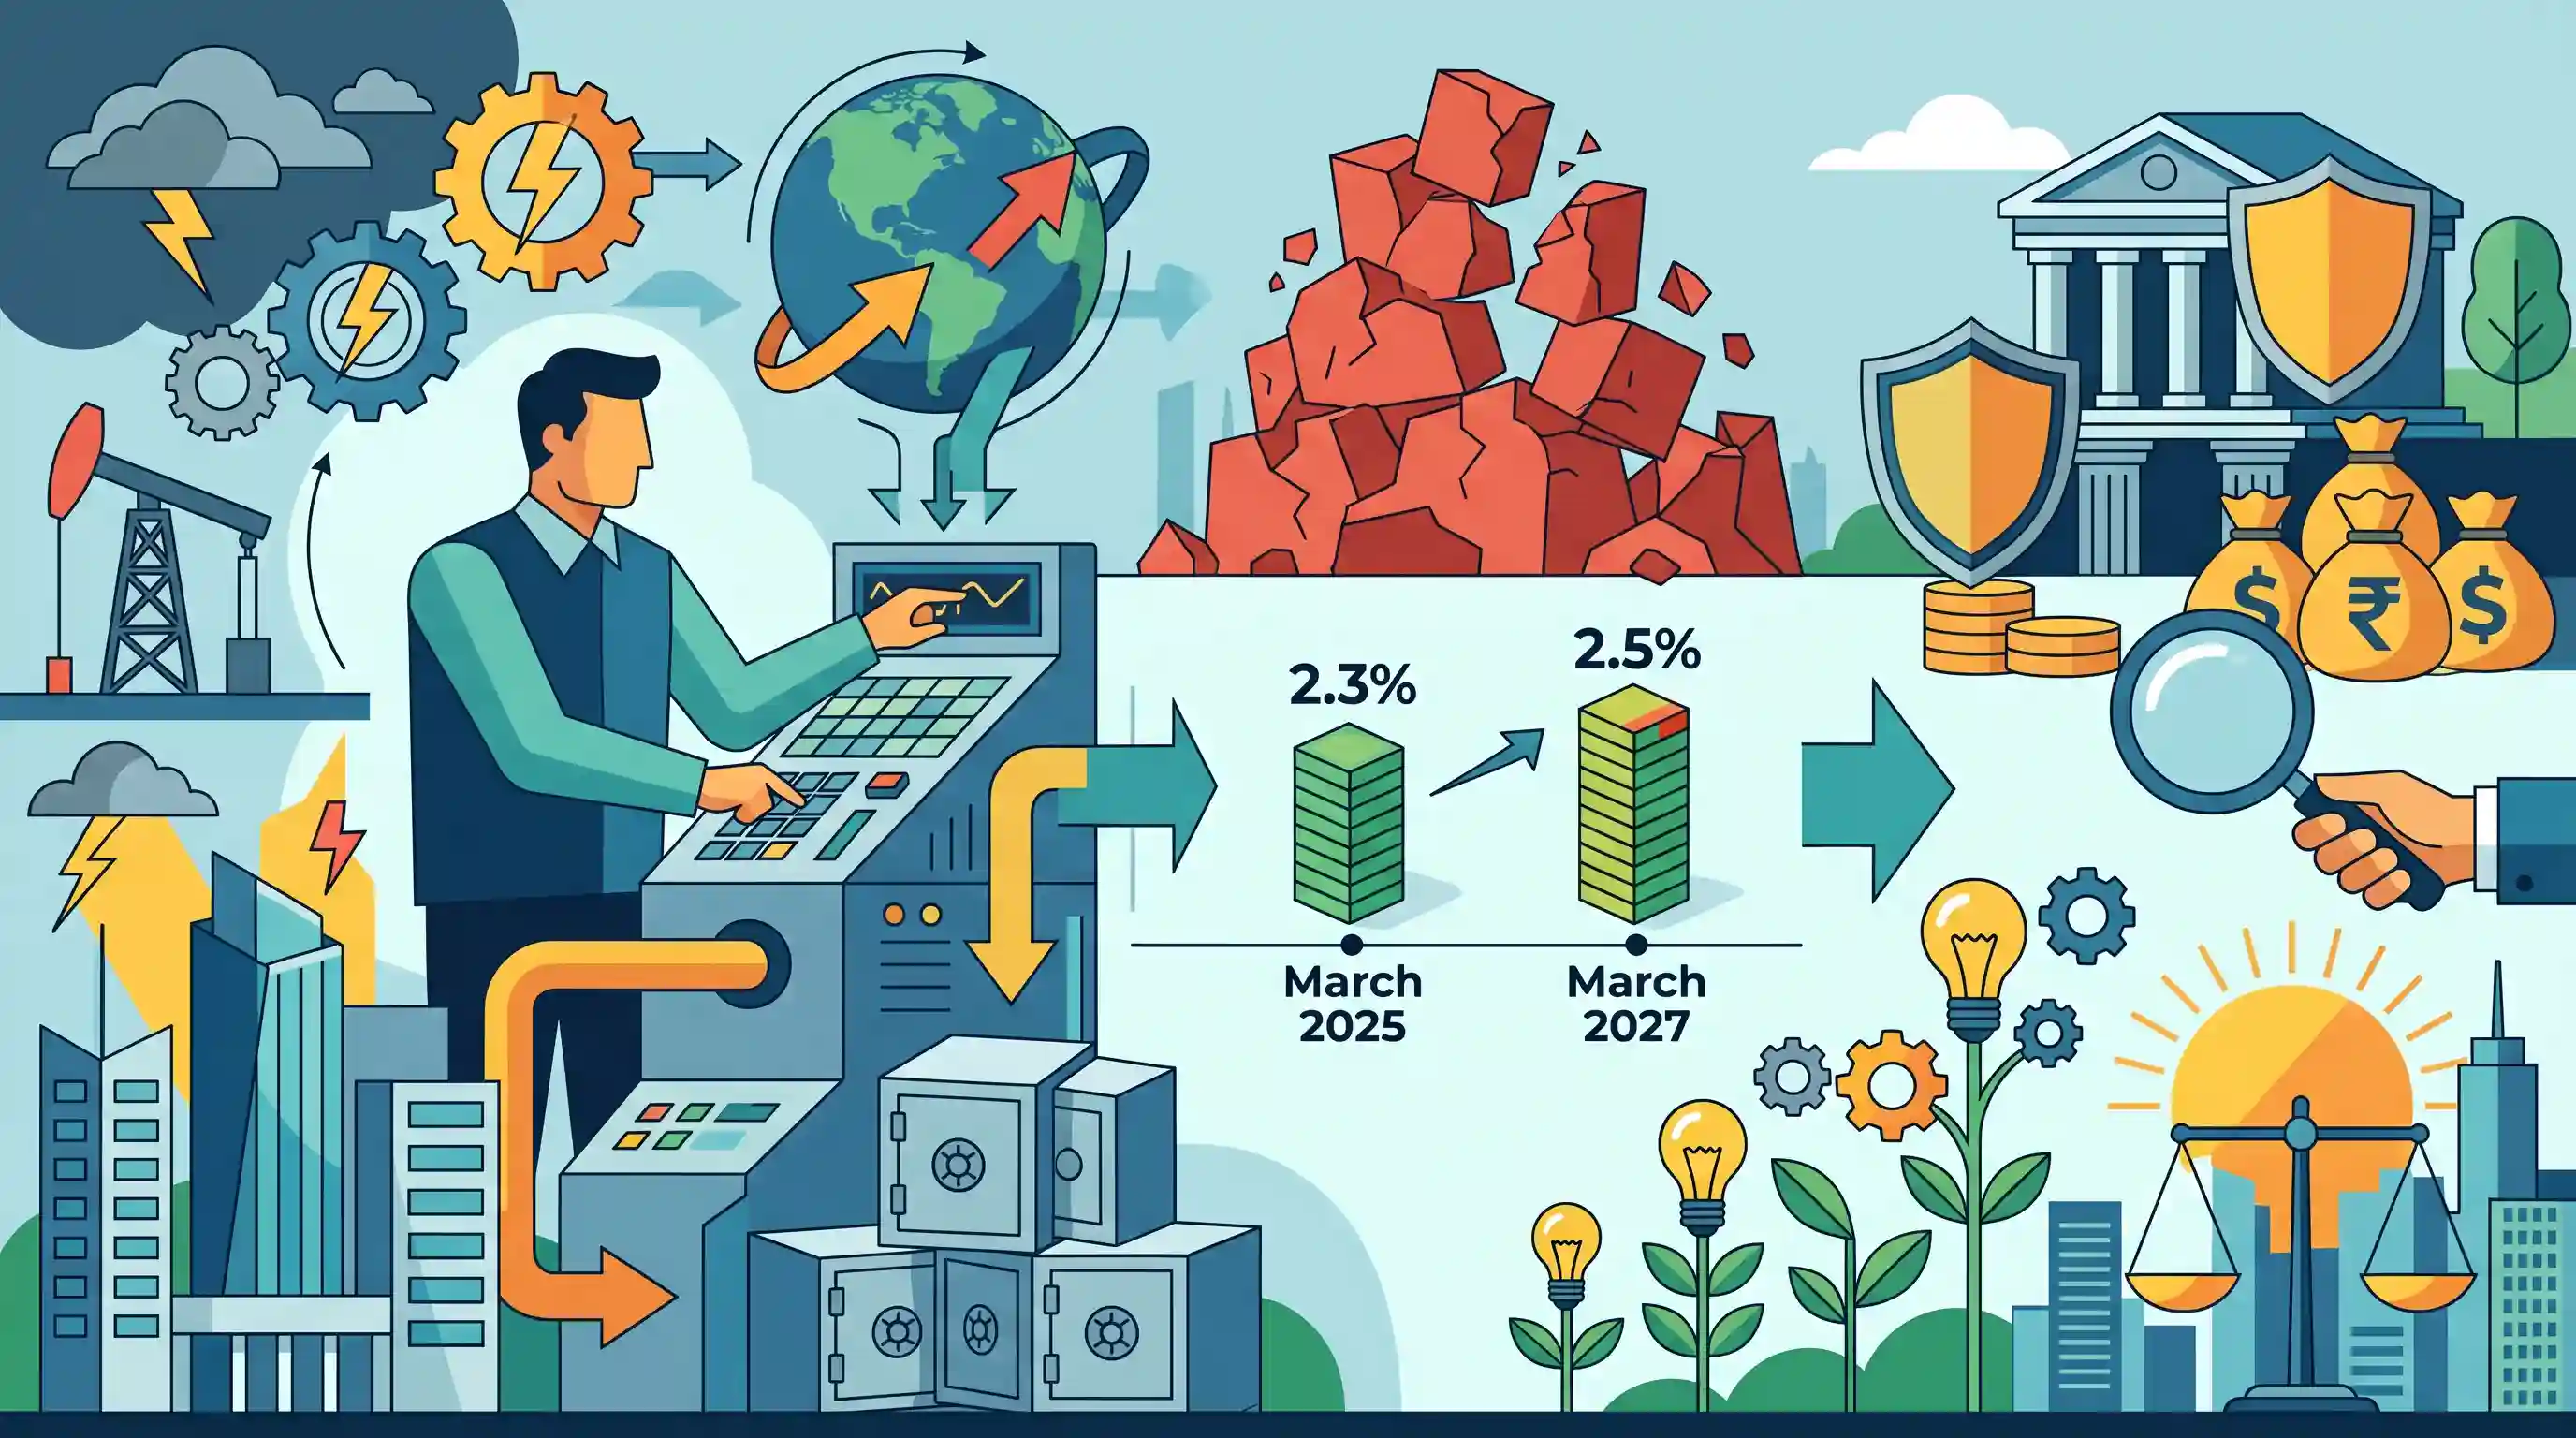
Recent stress tests conducted by the Reserve Bank of India (RBI) indicate that the gross non-performing assets (GNPA) ratio of Indian banks is projected to increase slightly from 2.3% in March 2025 to 2.5% by March 2027 under the baseline scenario. These stress tests are a critical risk management tool used to assess the resilience of the banking sector to potential macroeconomic vulnerabilities and credit risks. Although the projected rise is marginal and remains well below historical highs, it underscores the importance of proactive risk monitoring, adequate capital provisioning, and maintaining overall financial stability in the economy.
Key Points
- The Reserve Bank of India (RBI) conducted stress tests projecting that the Gross Non-Performing Assets (GNPA) of banks may rise from 2.3% in March 2025 to 2.5% by March 2027 under a baseline scenario.
- Stress tests evaluate the resilience of the banking sector by measuring how asset quality and capital buffers respond to hypothetical adverse macroeconomic shocks.
- While the projected increase in GNPA is slight, it flags the need for banks to maintain vigilant credit monitoring and provisioning to absorb potential losses.
- Such assessments are central to the RBI's mandate of ensuring macroeconomic resilience and are typically published in its periodic Financial Stability Report.
Important Terms
Gross Non-Performing Assets (GNPA)

The total value of loans defaulted or delayed by 90+ days before deducting provisions. It indicates the raw magnitude of bad loans in a bank's portfolio.
UPSC context
GS Paper 3: Indian Economy. Key metric for assessing banking sector health and asset quality reforms.
Stress Tests
A simulation exercise used by the RBI to assess the banking system's resilience against hypothetical adverse economic shocks like GDP contraction or inflation spikes.
UPSC context
GS Paper 3: Banking and Financial Stability. Tests systemic resilience to macroeconomic vulnerabilities.
Financial Stability Report (FSR)
A bi-annual RBI publication that assesses the health and resilience of the Indian financial system, incorporating inputs from all financial sector regulators.
UPSC context
GS Paper 3: Economy. A primary source for official data on banking risks and systemic stability.
Capital to Risk-Weighted Assets Ratio (CRAR)
A metric comparing a bank's capital to its risk-weighted assets to ensure it can absorb a reasonable amount of loss before becoming insolvent.
UPSC context
GS Paper 3: Banking reforms and Basel III norms. Measures a bank's solvency and depositor protection.
Baseline Scenario
The 'business-as-usual' projection in a stress test, derived from current macroeconomic forecasts like GDP growth and inflation, assuming no extreme shocks occur.
UPSC context
GS Paper 3: Economic modeling. Used to compare standard growth paths against adverse stress conditions.
Reserve Bank of India (RBI)
India’s central bank and regulatory authority for the banking system, responsible for monetary policy and maintaining overall financial stability.
UPSC context
GS Paper 3: Statutory bodies. Its regulatory role is central to any discussion on Indian banking.
Prelims Trap
The Financial Stability Report, which details bank stress tests, is published annually by the Ministry of Finance.
The Financial Stability Report (FSR) is published bi-annually by the RBI, not the Ministry of Finance. Aspirants often confuse macroeconomic reporting bodies.
Static Concepts Connected
What is the Capital Adequacy Ratio (CAR)?
- Definition: The ratio of a bank's core capital to its risk-weighted assets and current liabilities.
- Purpose: It acts as a financial cushion, ensuring banks have enough capital to absorb a reasonable amount of losses before becoming insolvent during macroeconomic shocks.
- Basel & RBI Norms: While Basel III norms recommend a minimum CAR of 8%, the RBI mandates a stricter 9% for scheduled commercial banks in India.
How are Non-Performing Assets (NPAs) classified in India?
- Sub-standard Assets: NPAs that have remained overdue for less than or equal to 12 months.
- Doubtful Assets: NPAs that have remained in the sub-standard category for a continuous period of 12 months.
- Loss Assets: Assets where an uncollectible loss has been identified by the bank or auditors, but the amount has not yet been fully written off.
Cross-Topic Patterns
Twin Balance Sheet Problem to Advantage
Economic Surveys recently highlighted India's shift from a 'Twin Balance Sheet problem' to a 'Twin Balance Sheet advantage' as both corporate deleveraging and banking sector health (historically low GNPAs) improved post-2020.
IBC and Asset Reconstruction Efficacy
The ability to maintain low GNPAs in stress tests relies heavily on resolution frameworks. UPSC often links bank health metrics with the efficacy of the Insolvency and Bankruptcy Code (IBC) and NARCL.

Expect a multi-statement Prelims question in 2026 on RBI's macro-stress testing framework, testing FSR publication and CAR norms.
Linked PYQs · 4
Linked PYQs · 4
- 2024PrelimsGS1
Consider the following statements : 1. In India, Non-Banking Financial Companies can access the Liquidity Adjustment Facility window of the Reserve Bank of India. 2. In India, Foreign Institutional Investors can hold the Government Securities (G-Secs). 3. In India, Stock Exchanges can offer separate trading platforms for debts. Which of the statements given above is/are correct?
- 2023PrelimsGS1
Which one of the following activities of the Reserve Bank of India is considered to be part of 'sterilization'?
- 2025PrelimsGS1
Which of the following are the sources of income for the Reserve Bank of India? I. Buying and selling Government bonds II. Buying and selling foreign currency III. Pension fund management IV. Lending to private companies V. Printing and distributing currency notes Select the correct answer using the code given below.
- 2022MainsGS3
Is inclusive growth possible under market economy ? State the significance of financial inclusion in achieving economic growth in India.
