Monetary Policy Transmission and Credit Growth Challenges
Source:The Hindu ↗
Why It Matters
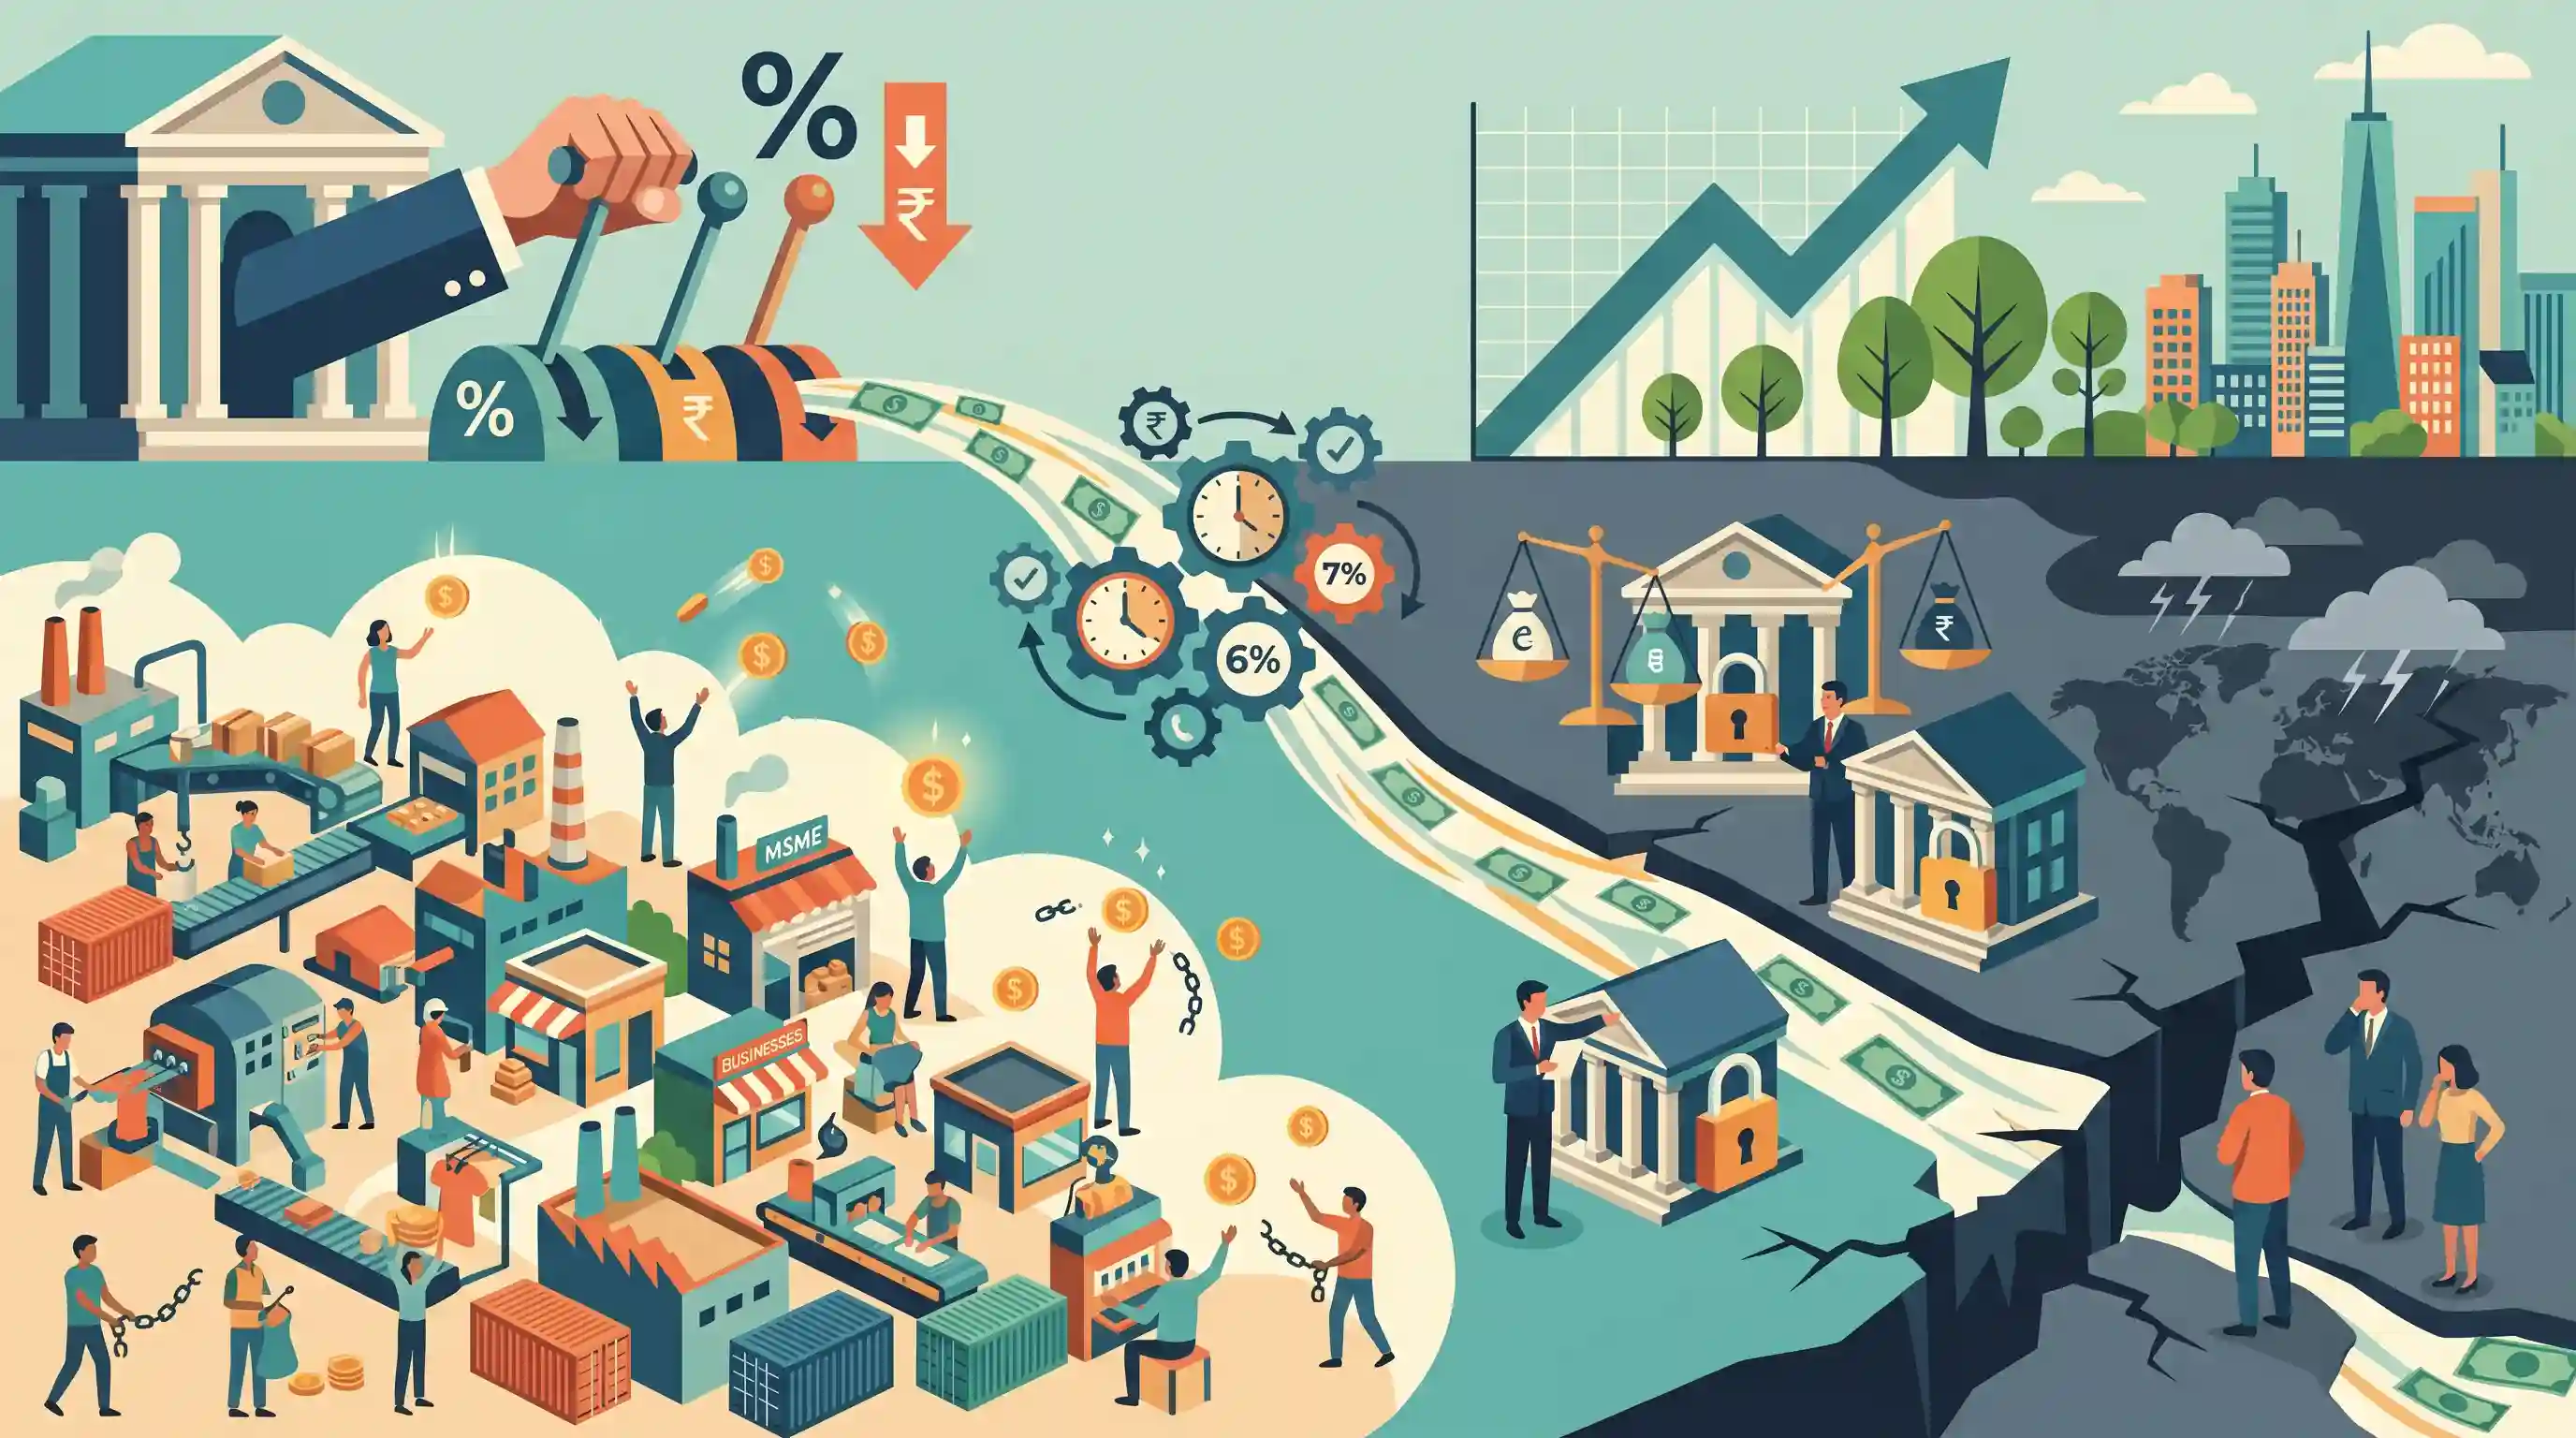
Highlights the practical challenges of monetary transmission and credit flow in the Indian economy, emphasizing the disconnect between policy rate cuts and actual lending to critical sectors like MSMEs.
Summary
The Reserve Bank of India (RBI) has implemented aggressive monetary easing, including a 50 bps cut in the repo rate and a 100 bps cut in the cash reserve ratio (CRR), aiming to revitalize tepid urban consumption and private investment. A primary target is the MSME sector, which forms the backbone of India's employment and exports but suffers from restricted credit access. Because 80% of retail and SME loans are linked to external benchmarks, borrowers will experience immediate relief in interest costs. However, the ultimate success of this stimulus depends on banks overcoming their risk aversions regarding SMEs and managing their credit-deposit ratios, as well as the willingness of businesses and consumers to increase borrowing amid global uncertainties.
Key Points
- The RBI aggressively eased monetary policy by cutting the repo rate by 50 basis points and the CRR by 100 basis points.
- The easing is primarily aimed at reviving urban consumption and private investment, with a specific focus on the MSME sector.
- MSMEs contribute 29% to India's GDP and employ 60% of the workforce, but currently receive only 16% of total bank credit.
- Nearly 80% of retail and SME loans are linked to external benchmarks, ensuring almost immediate transmission of the lower interest rates to borrowers.
- The success of the RBI's policy pivot depends heavily on the willingness of banks to lend and the appetite of consumers and SMEs to take on more debt.
Important Terms
Repo Rate

The interest rate at which the RBI lends money to commercial banks for short-term needs against government securities. It is the primary tool for managing inflation and liquidity.
UPSC context
GS-3 Economy; tests understanding of monetary policy instruments, inflation targeting, and liquidity management.
Cash Reserve Ratio (CRR)
The mandatory percentage of a bank's total deposits (NDTL) that must be held as cash with the RBI. It regulates the money supply and ensures banking stability.
UPSC context
GS-3 Economy; fundamental for topics on quantitative credit control tools and bank lending capacity.
External Benchmark Lending Rate (EBLR)
A framework where bank lending rates are linked to external indicators like the Repo Rate. It ensures faster, more transparent adjustments for retail and MSME borrowers.
UPSC context
GS-3 Economy; relevant for banking reforms, transparency in lending, and policy transmission efficiency.
Monetary Policy Transmission
The process through which a central bank's policy actions, such as rate changes, influence market interest rates, credit availability, and ultimately economic growth and inflation.
UPSC context
GS-3 Economy; examines structural bottlenecks in banking and the efficacy of stimulus measures.
MSME Sector
Enterprises classified by investment and turnover that form India's industrial backbone. They contribute roughly 30% to GDP and are critical for employment and exports.
UPSC context
GS-3 Economy; core topic for inclusive growth, industrial policy, and employment generation.
Reserve Bank of India (RBI)
India's central bank and regulatory authority responsible for formulating monetary policy, supervising the financial system, and maintaining price stability and foreign exchange reserves.
UPSC context
GS-3 Economy; essential for institutional frameworks of economic governance and regulatory oversight.
Prelims Trap
All bank loans are mandated by the RBI to be linked to the External Benchmark Lending Rate (EBLR).
The RBI mandated EBLR only for retail, personal, and MSME loans starting in 2019. Corporate loans are still largely priced using the internal MCLR system, which experiences lagged transmission.
Static Concepts Connected
What is the External Benchmark Lending Rate (EBLR) regime?
- Replaced MCLR: Introduced in 2019 to replace the internal Marginal Cost of Funds Based Lending Rate (MCLR) to improve transparency and policy transmission.
- External Indicators: Interest rates must be linked to external benchmarks such as the RBI Repo Rate or Government of India Treasury Bill yields.
- Targeted Mandate: EBLR is mandatory specifically for retail, personal, and MSME loans. This ensures that RBI rate cuts are immediately passed on to these borrowers.
How does the Cash Reserve Ratio (CRR) affect the money multiplier?
- Inverse Relationship: The money multiplier is inversely proportional to reserve requirements. A CRR cut reduces the denominator, directly increasing the multiplier.
- Credit Creation: By reducing the CRR, the RBI leaves commercial banks with more loanable funds, exponentially expanding the banking system's capacity to create credit.
- NDTL Percentage: CRR is the mandatory fraction of a bank's Net Demand and Time Liabilities (NDTL) kept as unencumbered cash balances with the RBI.
Cross-Topic Patterns
Monetary transmission vs structural MSME hurdles
Cheaper credit via rate cuts often fails to reach MSMEs because banks practice risk-aversion due to informal accounting and lack of collateral, creating a breakdown in the money multiplier.
CD Ratio dynamics and liquidity constraints
A high Credit-Deposit (CD) ratio limits a bank's ability to transmit RBI rate cuts, as over-leveraged banks prioritize mobilizing deposits over issuing new loans to maintain financial stability.

Expect a 2026 Prelims multi-statement question combining EBLR applicability (MSME vs Corporate) with Money Multiplier dynamics.
Linked PYQs · 3
Linked PYQs · 3
- 2021PrelimsGS1
The money multiplier in an economy increases with which one of the following?
- 2023MainsGS3
Faster economic growth requires increased share of the manufacturing sector in GDP, particularly of MSMEs. Comment on the present policies of the Government in this regard.
- 2016PrelimsGS1
What is/are the purpose/purposes of the 'Marginal Cost of Funds based Lending Rate (MCLR)' announced by RBI? 1. These guidelines help improve the transparency in the methodology followed by banks for determining the interest rates on advances. 2. These guidelines help ensure availability of bank credit at interest rates which are fair to the borrowers as well as the banks. Select the correct answer using the code given below.
