RBI Issues Revised Lead Bank Scheme Guidelines for Rural Credit
Source:The Hindu ↗
Why It Matters
The Lead Bank Scheme is a foundational element of India's rural credit and financial inclusion architecture, directly appearing in past UPSC Prelims. Understanding its core philosophy (service area approach, district-level coordination) and modern revisions is crucial for GS3 answers on banking, rural development, and inclusive growth.
Summary
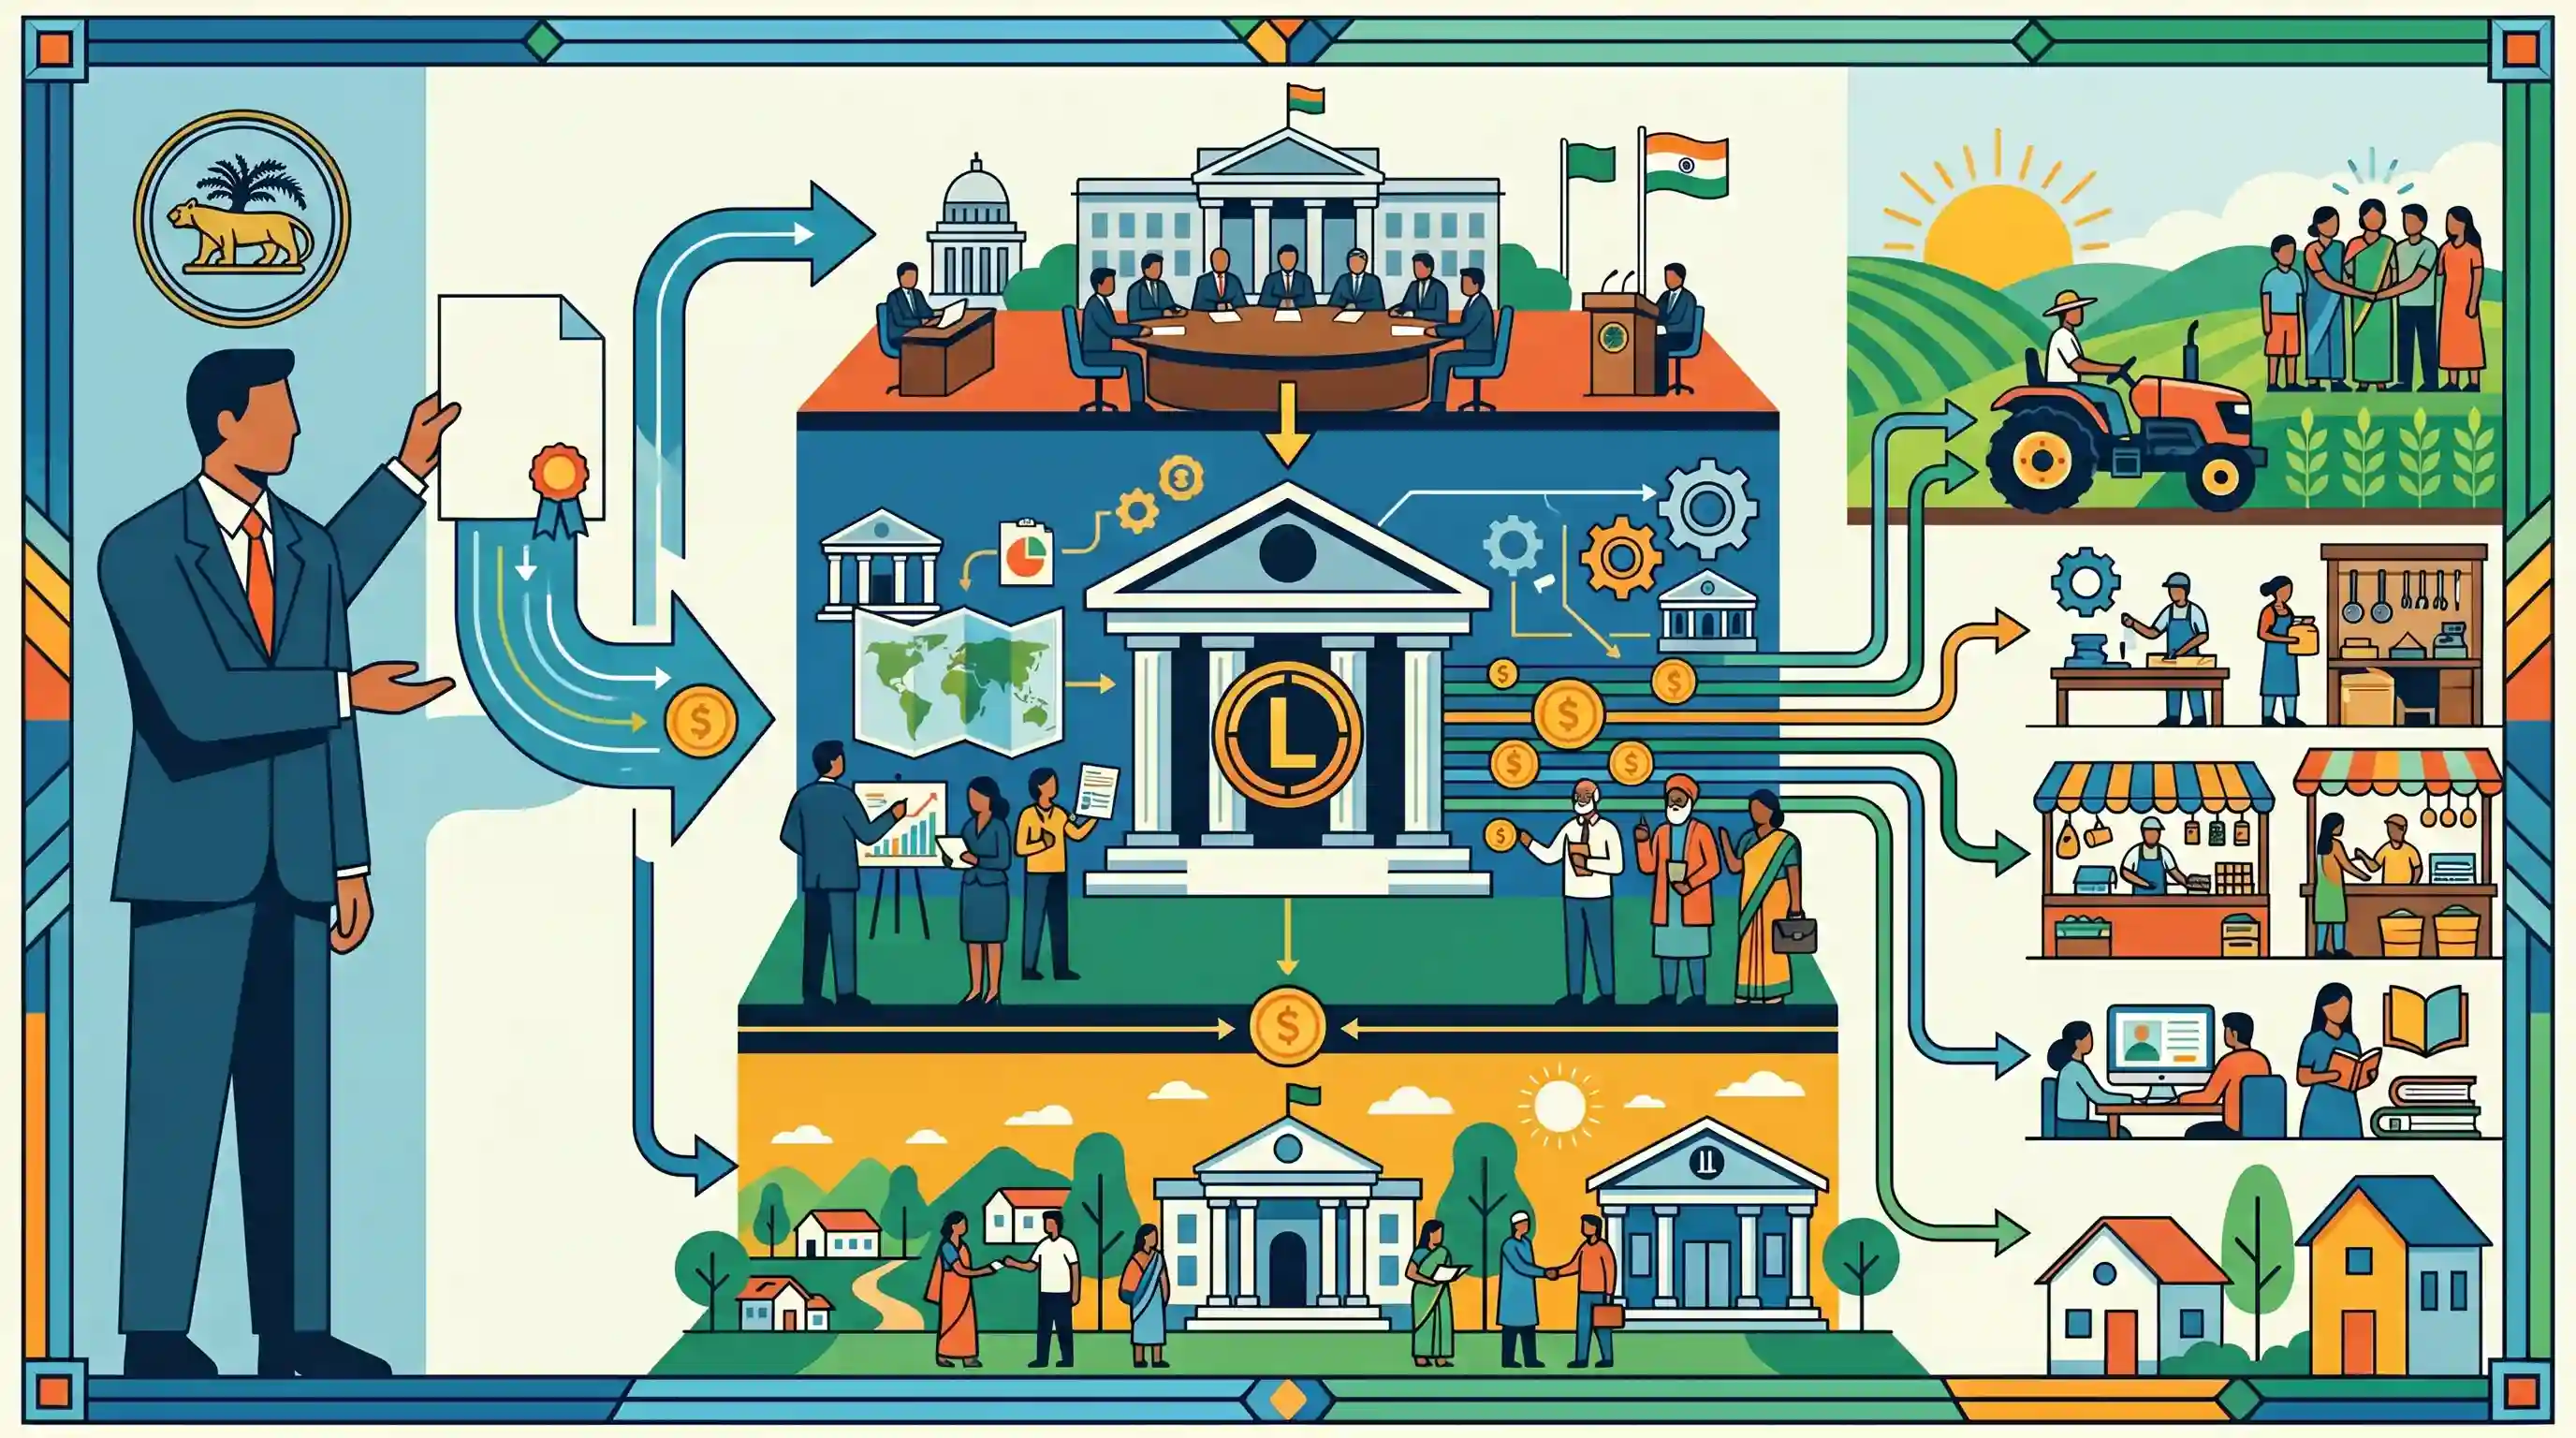
The Reserve Bank of India (RBI) has released draft guidelines to revise the Lead Bank Scheme (LBS) to enhance credit flow to priority sectors and strengthen financial inclusion at the district level. Introduced in 1969, the LBS was designed to coordinate development efforts among banks, government bodies, and agencies. The revised framework delineates roles and establishes a clear three-tier structure—Block Level, District Level, and State Level committees. A designated commercial bank in each district acts as the Lead Bank, responsible for steering credit planning and resolving operational issues to achieve inclusive economic growth.
Key Points
- The RBI issued draft revised guidelines for the Lead Bank Scheme (LBS) to finetune its objectives and structural frameworks.
- Originally introduced in 1969, the LBS aims to coordinate district-level developmental activities between credit institutions and government agencies.
- A commercial bank is designated as the 'Lead Bank' in each district to spearhead credit flow to priority sectors and promote financial inclusion.
- The framework relies on a three-tier institutional structure: BLBC at the block level, DCC/DLRC at the district level, and SLBC at the state apex level.
- SLBC Convenor Banks will coordinate state-wide banking efforts and collaborate with State governments to resolve operational issues in priority sector lending.
Important Terms
Lead Bank Scheme (LBS)

Introduced in 1969, this scheme assigns a specific commercial bank to each district to coordinate credit planning and financial inclusion efforts among banks and government agencies.
UPSC context
GS-3 (Economy); important for banking sector reforms, rural credit, and the historical evolution of social banking in India.
State Level Bankers' Committee (SLBC)
The apex inter-institutional forum at the state level that coordinates banking activities and aligns them with state government policies to enhance credit flow and financial inclusion.
UPSC context
GS-3 (Economy); tests knowledge of institutional frameworks for regional development and state-level financial coordination.
District Consultative Committee (DCC)
A district-level forum chaired by the District Collector where banks and government departments review the progress of the Annual Credit Plan (ACP) and developmental schemes.
UPSC context
GS-3 (Economy); critical for understanding decentralized planning and the role of district administration in economic governance.
District Level Review Committee (DLRC)
A quarterly forum at the district level involving elected representatives (MPs/MLAs) to monitor bank performance and quality of program implementation under the Lead Bank Scheme.
UPSC context
GS-2 (Governance) and GS-3 (Economy); relates to transparency and legislative oversight in financial development programs.
Block Level Banker's Committee (BLBC)
The grassroots coordination forum chaired by the Lead District Manager, focused on ensuring that individual bank branches meet the credit needs of their local service areas.
UPSC context
GS-3 (Economy); essential for the 'Service Area Approach' and field-level implementation of financial inclusion.
Lead District Manager (LDM)
A designated officer from the Lead Bank responsible for coordinating district-level banking activities, convening committee meetings, and serving as a link between banks and administration.
UPSC context
GS-3 (Economy); tests understanding of administrative roles responsible for rural banking and ground-level credit delivery.
Prelims Trap
"The Lead Bank has exclusive rights to disburse priority sector loans and regulates other banks in its district."
The Lead Bank is merely a consortium leader and coordinator for credit planning. It has neither exclusive lending rights nor regulatory authority over other commercial banks.
Static Concepts Connected
What are the historical origins and structure of the Lead Bank Scheme (LBS)?
- Origins: Introduced in 1969 based on the recommendations of the Gadgil Study Group and Nariman Committee following the nationalization of banks.
- Core Function: Acts as a consortium leader coordinating district-level credit planning between financial institutions and government development agencies.
- Three-Tier Setup: Executes its mandate via Block Level (BLBC), District Level (DCC/DLRC), and State Level Bankers' Committees (SLBC).
How does Priority Sector Lending (PSL) function in India?
- PSL Targets: Domestic scheduled commercial banks and foreign banks with 20+ branches must allocate 40% of their Adjusted Net Bank Credit (ANBC) to priority sectors.
- Key Categories: Categories include Agriculture, MSMEs, Export Credit, Education, Housing, Social Infrastructure, and Renewable Energy.
- Compliance Tool: Banks can buy or sell Priority Sector Lending Certificates (PSLCs) on the e-Kuber portal to cover shortfalls in their PSL targets.
Cross-Topic Patterns
LBS + Direct Benefit Transfers (DBT)
The Lead Bank Scheme's district-level coordination (DCC) is critical for resolving grassroots banking bottlenecks and ensuring last-mile delivery for DBT schemes like PM-KISAN and PMJDY.
Decentralized Credit Planning + PRIs
LBS integrates banking sector targets with grassroots developmental planning, often requiring coordination with Panchayati Raj Institutions (PRIs) to prepare viable, localized rural credit plans under the Service Area Approach.

Expect a 2026 Prelims multi-statement question pairing Lead Bank Scheme's 1969 origins with its modern role in PSL and PMJDY coordination.
Linked PYQs · 4
Linked PYQs · 4
- 2012PrelimsGS1
The basic aim of Lead Bank Scheme is that
- 2019PrelimsGS1
The Service Area Approach was implemented under the purview of
- 2013PrelimsGS1
Priority Sector Lending by banks in India constitutes the lending to
- 2022MainsGS3
Is inclusive growth possible under market economy ? State the significance of financial inclusion in achieving economic growth in India.
