RBI Issues Revised Draft Rules to Curb Regulated Entities Evergreening
Source:The Hindu ↗
Why It Matters
Understanding how financial instruments like AIFs can be exploited for regulatory arbitrage (like evergreening loans) and how regulators (RBI and SEBI) intervene is crucial for UPSC candidates, given the recurring emphasis on banking sector health, NPAs, and capital market regulations in both Prelims and Mains (GS3).
Summary
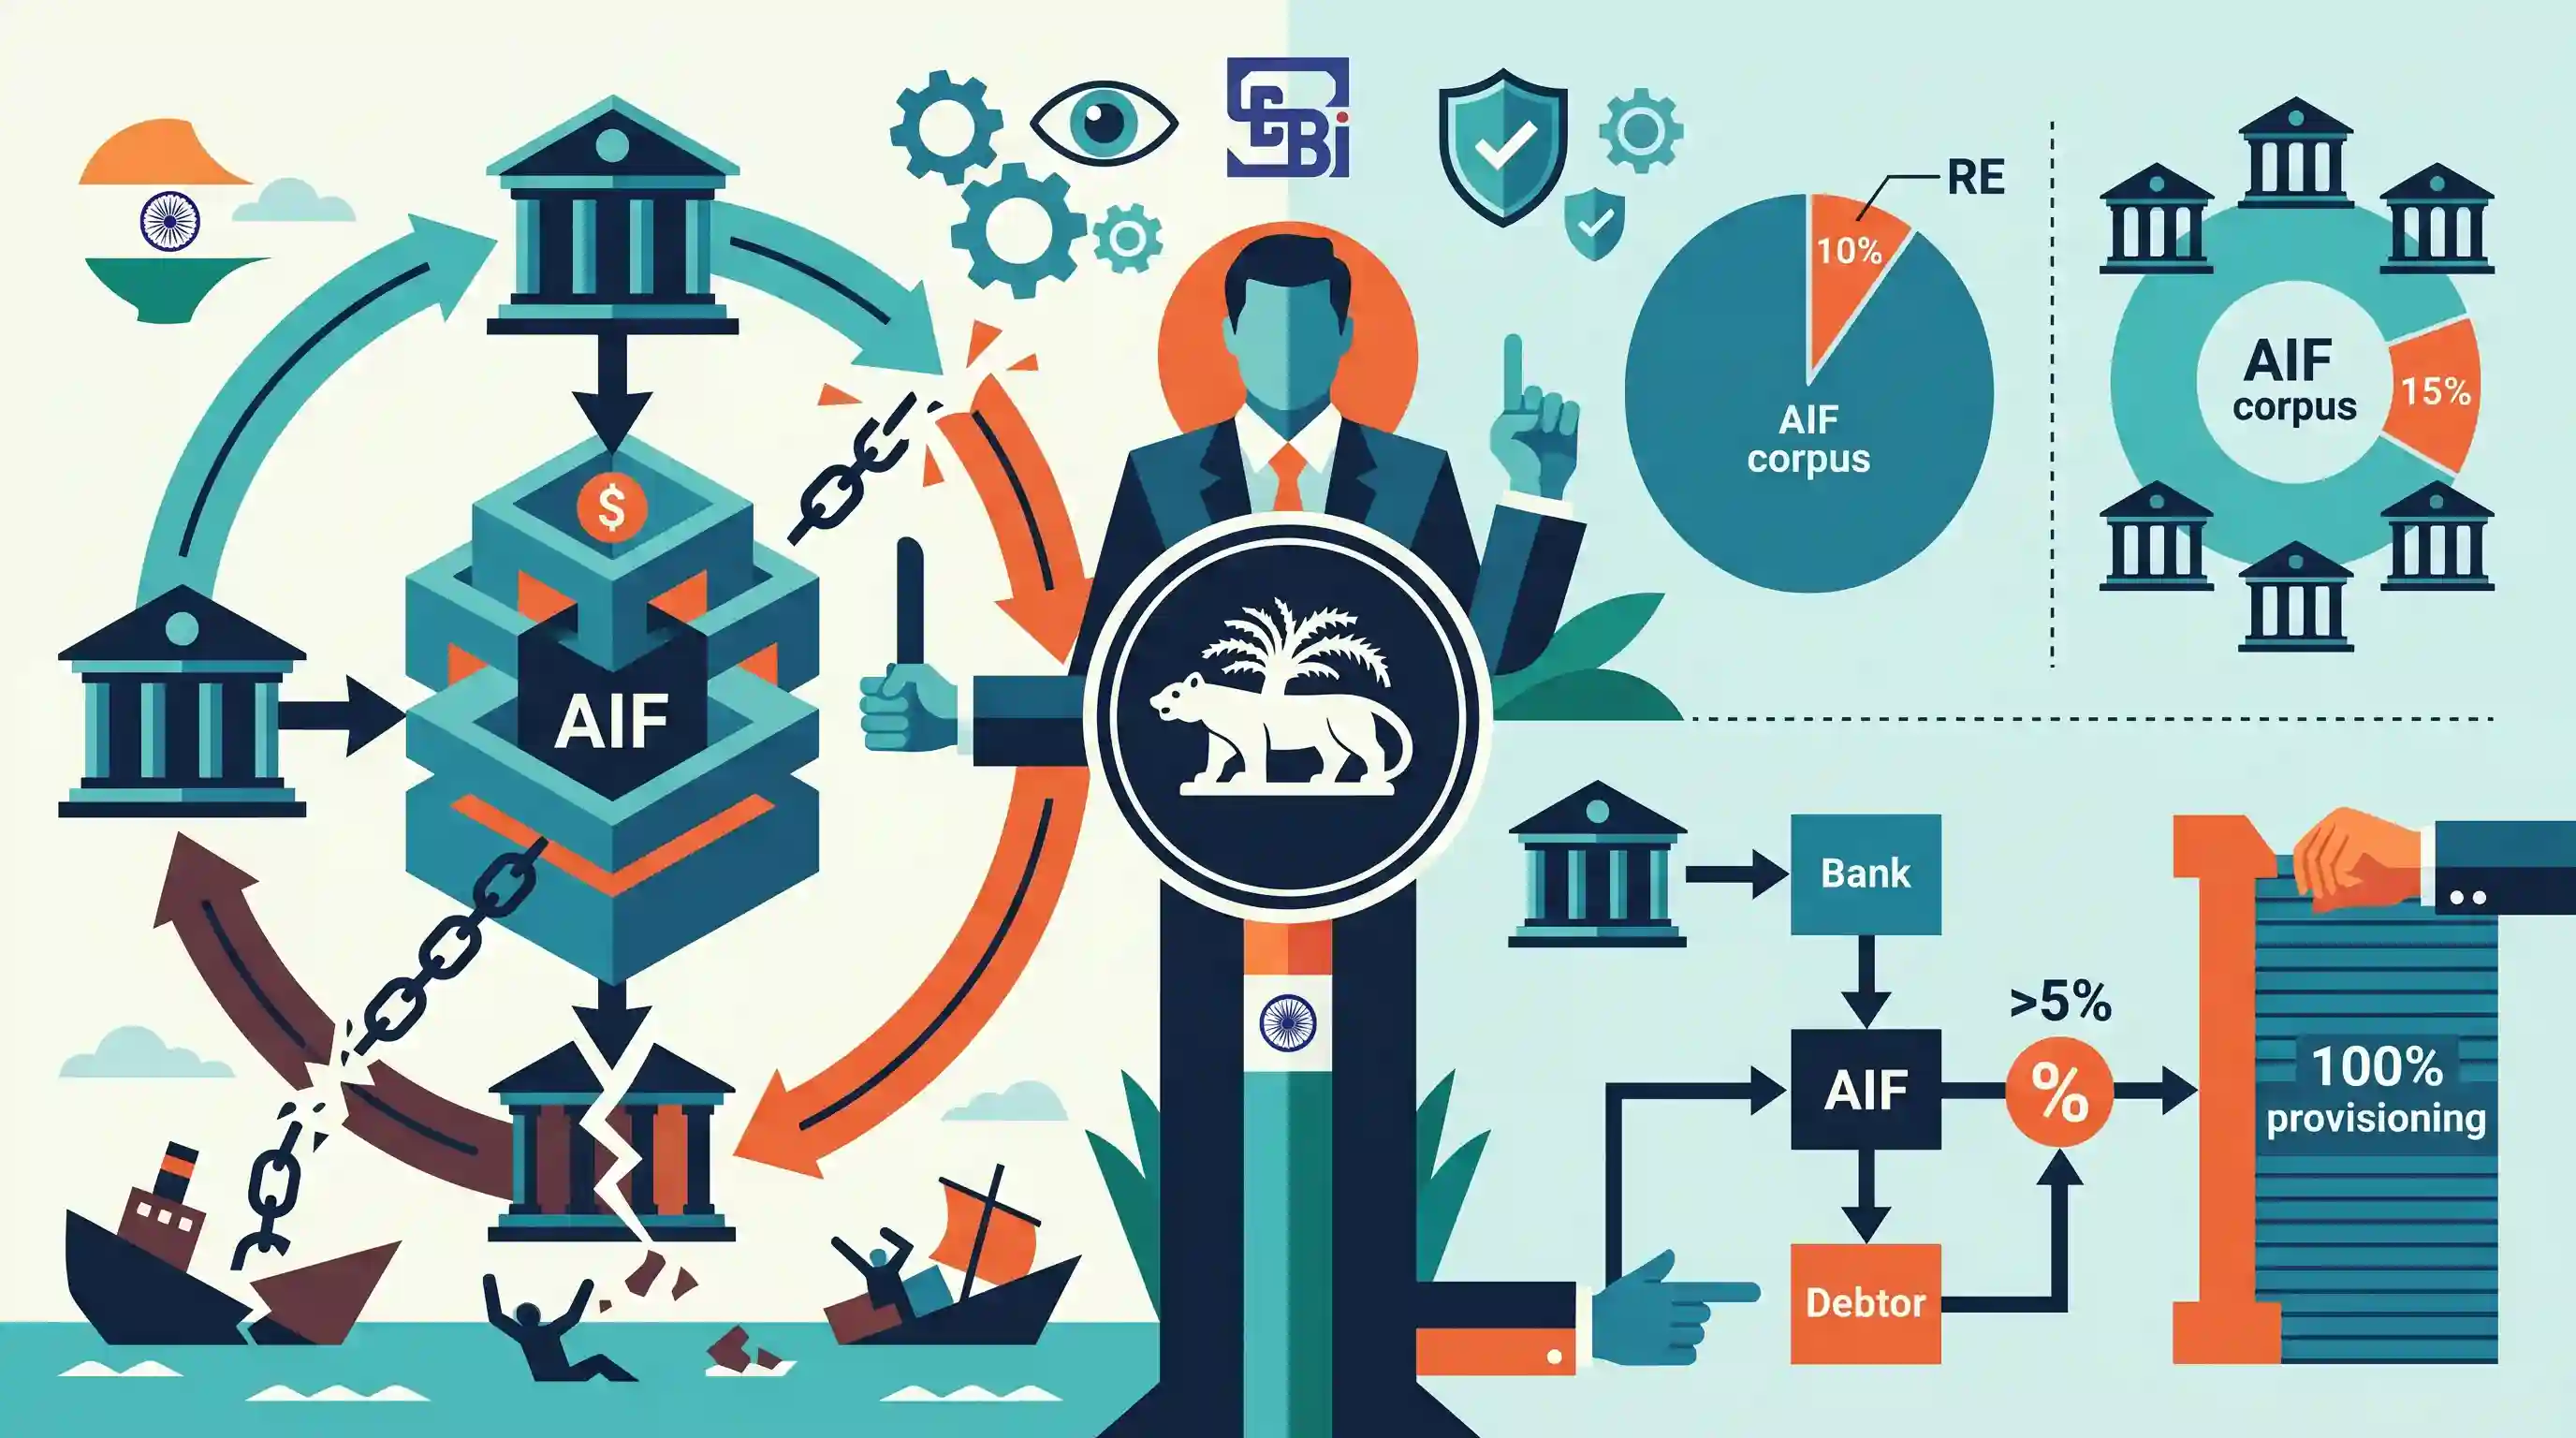
The Reserve Bank of India (RBI) has issued revised draft guidelines restricting how Regulated Entities (REs), such as banks and NBFCs, can invest in Alternative Investment Funds (AIFs). The move is primarily designed to prevent financial institutions from 'evergreening' bad loans—a practice where entities mask non-performing assets (NPAs) by using AIF investments to indirectly channel funds back to defaulting borrowers. The new draft proposes strict limits: capping a single RE's investment at 10% of an AIF scheme's corpus and introducing a collective limit of 15% for all REs. Furthermore, if an RE holds more than 5% in an AIF scheme that invests in the RE's debtor, it will trigger a 100% provisioning requirement, ensuring stronger financial discipline and complementing parallel efforts by SEBI.
Key Points
- The RBI released revised draft directions to regulate investments by Regulated Entities (REs) in Alternative Investment Funds (AIFs).
- The regulations aim to prevent the circumvention of regulatory frameworks, particularly the 'evergreening' of bad loans through AIF structures.
- A single RE's contribution is capped at 10% of an AIF scheme's corpus, with a collective 15% ceiling for all REs combined in a single scheme.
- Investments by an RE exceeding 5% of an AIF scheme will require 100% provisioning if the scheme makes downstream debt investments in a debtor company of the RE.
- SEBI has collaborated by issuing concurrent guidelines requiring specific due diligence for AIFs to prevent such regulatory arbitrage.
Important Terms
Alternative Investment Funds (AIFs)

Privately pooled investment vehicles that collect funds from sophisticated investors for non-traditional assets like startups, private equity, or real estate; regulated by SEBI under 2012 regulations.
UPSC context
GS Paper 3: Investment models; crucial for understanding non-banking financial intermediation and startup ecosystem financing.
Evergreening (of Loans)
The unethical practice of providing fresh loans to a defaulting borrower to help them repay old debt, thereby hiding actual financial stress and avoiding NPA classification.
UPSC context
GS Paper 3: Banking sector reforms; tests knowledge of financial stability risks and bank-led misgovernance.
Regulated Entities (REs)
Financial institutions directly supervised by the RBI, including commercial banks, NBFCs, and cooperative banks, which must adhere to specific prudential and operational guidelines.
UPSC context
GS Paper 3: Indian Economy; refers to the universe of institutions implementing RBI's monetary and credit policies.
Provisioning Norms
Mandatory capital set aside by banks to cover potential losses from bad loans; stricter provisioning is required as asset quality deteriorates.
UPSC context
GS Paper 3: Banking; tests understanding of "Expected Credit Loss" (ECL) and financial resilience mechanisms.
Non-Performing Assets (NPAs)
Loans or advances for which the principal or interest payment remains overdue for a period of 90 days or more, indicating credit stress.
UPSC context
GS Paper 3: Economic Development; a recurring theme in banking health, balance sheet stress, and economic recovery.
Securities and Exchange Board of India (SEBI)
A statutory regulatory body established in 1992 to protect investor interests and regulate the securities, commodity, and capital markets in India.
UPSC context
GS Paper 3: Regulatory bodies; essential for understanding capital market oversight and corporate governance.
Prelims Trap
"Alternative Investment Funds (AIFs) operate under the regulatory oversight of the Reserve Bank of India."
AIFs are regulated by SEBI. RBI is only regulating the investments made by its Regulated Entities (banks/NBFCs) into these SEBI-registered AIFs, not the AIFs themselves.
Static Concepts Connected
What is the "Evergreening" of loans?
- Definition: Extending fresh credit to a stressed borrower specifically to enable them to repay an existing defaulting loan.
- Impact: It masks the true extent of Non-Performing Assets (NPAs), delaying structural resolution and impairing balance sheet transparency.
- Governance Context: The PJ Nayak Committee heavily criticized the practice, highlighting it as a major governance failure in Indian banking.
What are Alternative Investment Funds (AIFs)?
- Definition: Privately pooled investment vehicles incorporated in India (excluding mutual funds) that gather capital from sophisticated domestic or foreign investors.
- Categories: They are divided into Category I (Startups, SMEs, Social ventures), Category II (Private Equity, Debt funds), and Category III (Hedge funds).
- Regulator: They are registered and primarily regulated by the Securities and Exchange Board of India (SEBI).
Cross-Topic Patterns
Regulatory arbitrage across RBI & SEBI domains
Entities often use capital market instruments (AIFs/SEBI) to bypass banking norms (NPAs/RBI). Joint regulations highlight the shift towards inter-regulatory synchronization, reflecting the mandate of the FSDC.
Evolution of the Twin Balance Sheet Problem
While headline Gross NPAs have dropped, RBI's crackdown on evergreening via AIFs indicates concealed stress still exists, evolving the classic 'Twin Balance Sheet' problem into more complex off-balance-sheet structures.

A multi-statement Prelims question testing 'evergreening' mechanics alongside SEBI's categorization of AIFs is highly probable for 2026.
Linked PYQs · 2
Linked PYQs · 2
- 2025PrelimsGS1
With reference to investments, consider the following: I. Bonds II. Hedge Funds III. Stocks IV. Venture Capital How many of the above are treated as Alternative Investment Funds?
- 2024PrelimsGS1
Consider the following statements : 1. In India, Non-Banking Financial Companies can access the Liquidity Adjustment Facility window of the Reserve Bank of India. 2. In India, Foreign Institutional Investors can hold the Government Securities (G-Secs). 3. In India, Stock Exchanges can offer separate trading platforms for debts. Which of the statements given above is/are correct?
