FY27 Disinvestment Target Set at Rs 80000 Crore
Source:Indian Express ↗
Why It Matters
RBI dividends and disinvestment proceeds are critical levers of fiscal policy. They directly impact the government's ability to finance expenditures and manage the fiscal deficit. Questions frequently appear in Prelims (budget components, RBI functions) and Mains GS3 (resource mobilization, government budgeting).
Summary
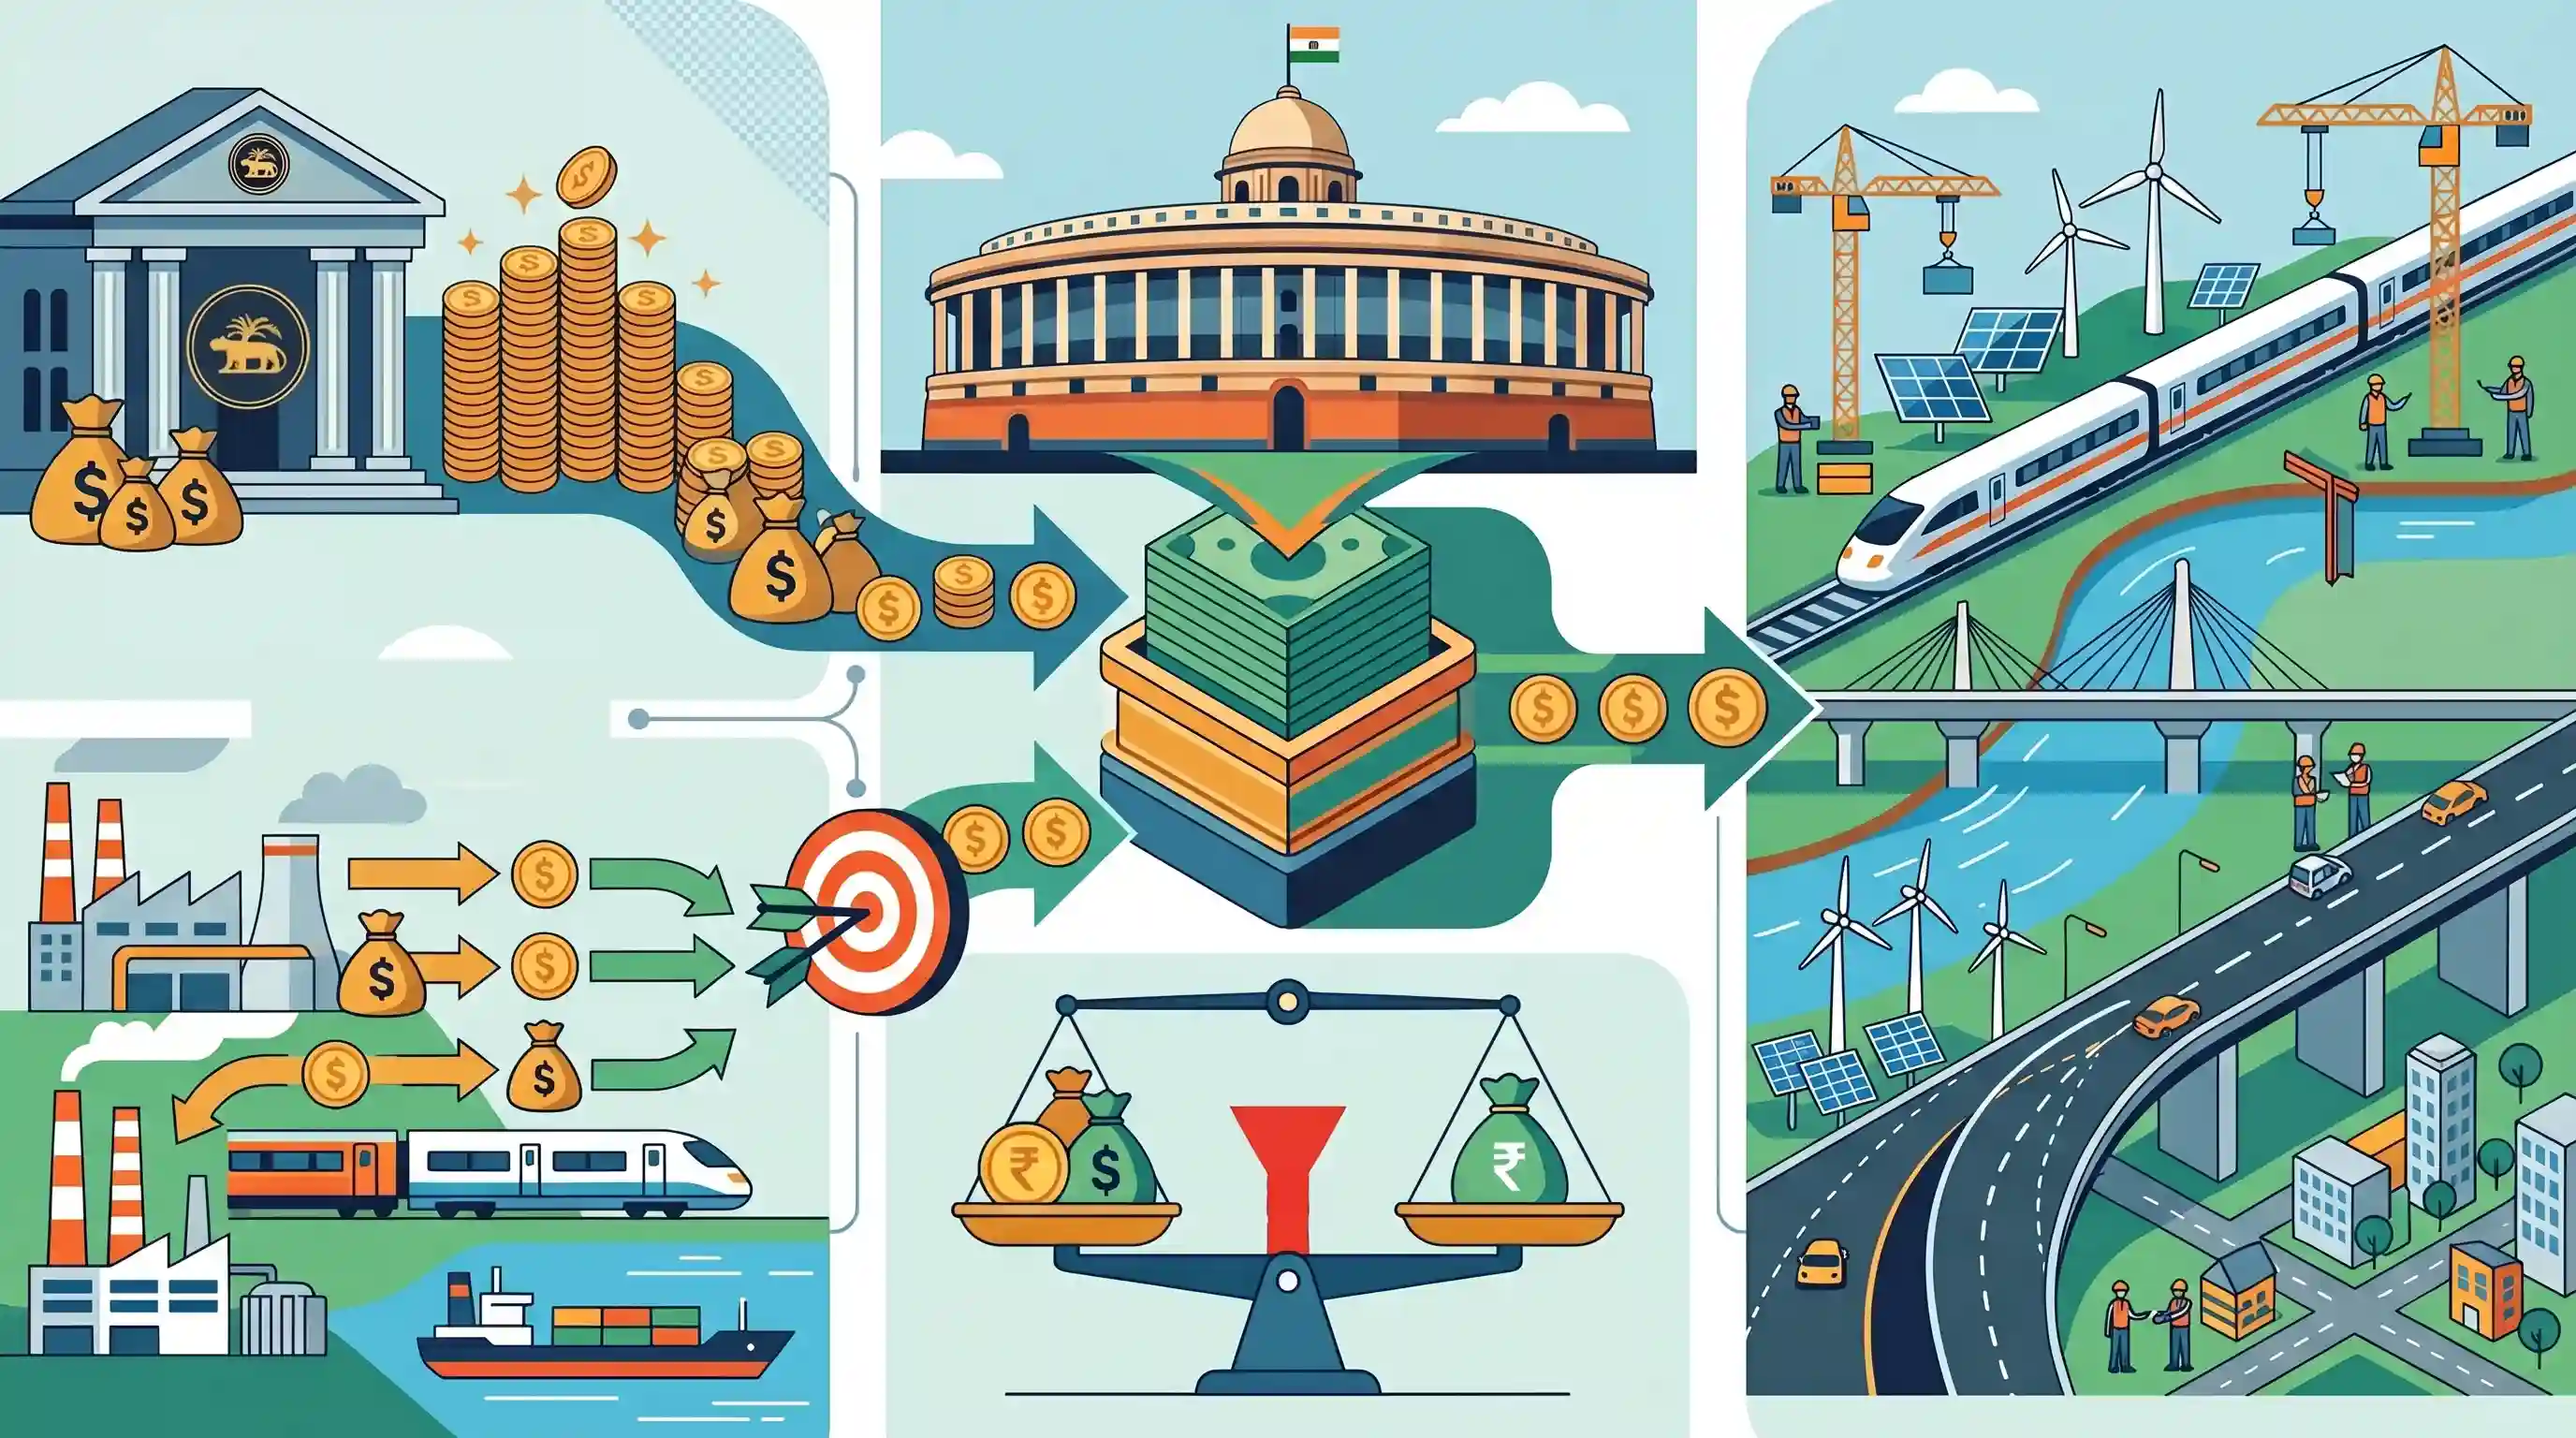
The Reserve Bank of India is expected to transfer another bumper dividend to the central government in FY27, complementing an estimated Rs 80,000 crore target for disinvestments. These inflows are crucial components of the government's non-tax revenue and non-debt capital receipts, providing necessary fiscal space to fund capital infrastructure projects without widening the fiscal deficit. Such financial management aligns with the long-term objective of prudent public expenditure and fiscal consolidation.
Key Points
- The Government of India is anticipated to receive another significant surplus transfer (dividend) from the RBI in FY27, boosting the Centre's non-tax revenue.
- Disinvestment targets for the upcoming financial year are expected to be set at approximately Rs 80,000 crore, reflecting the government's strategy of asset monetization.
- High non-tax revenues and non-debt capital receipts provide the government with a fiscal cushion to sustain capital expenditure while adhering to the fiscal consolidation glide path.
Important Terms
RBI Surplus Transfer

The transfer of the RBI's net profit (income minus expenditure and risk provisions) to the central government under Section 47 of the RBI Act, 1934.
UPSC context
GS Paper III: Indian Economy; tests understanding of non-tax revenue sources and the Economic Capital Framework (Jalan Committee).
Disinvestment
The sale or liquidation of government-owned assets, typically shares in Central Public Sector Enterprises (CPSEs), to raise resources without creating debt.
UPSC context
GS Paper III: Resource Mobilization; critical for discussing PSU reforms and non-debt capital receipts.
Fiscal Deficit
The difference between the government's total expenditure and its total revenue (excluding borrowings), indicating the total amount the government needs to borrow.
UPSC context
GS Paper III: Budgeting; a key indicator of fiscal health and macroeconomic stability frequently tested in Prelims and Mains.
Fiscal Consolidation
A strategy involving policy measures to reduce government deficits and the accumulation of public debt, aiming for a sustainable debt-to-GDP ratio.
UPSC context
GS Paper III: Government Budgeting; involves the FRBM Act and targets for sustainable public finance management.
Non-Tax Revenue
Recurring income earned by the government from sources other than taxes, such as interest receipts, dividends from PSUs, and fees for services.
UPSC context
GS Paper III: Budgeting; tests classification of receipts and their impact on the revenue deficit.
Non-Debt Capital Receipts
Capital receipts that do not increase the government's future repayment liabilities, primarily consisting of disinvestment proceeds and the recovery of loans.
UPSC context
GS Paper III: Budgeting; essential for understanding how the government funds capital expenditure without increasing debt.
Prelims Trap
"Disinvestment proceeds and RBI dividends both form part of the Central Government's non-tax revenue."
RBI dividends are Revenue Receipts (non-tax), but disinvestment proceeds are Non-Debt Capital Receipts (NDCR). Disinvestment reduces government assets, moving it strictly into the capital account.
Static Concepts Connected
How are RBI dividends and disinvestment proceeds classified in the Union Budget?
- RBI Dividend: Classified as a non-tax Revenue Receipt because it neither creates a liability nor reduces any government assets.
- Disinvestment Proceeds: Classified as a Non-Debt Capital Receipt (NDCR) since it involves liquidating government assets (PSU equity).
What is the Economic Capital Framework governing RBI surplus transfers?
- Origin: Formulated based on the recommendations of the Bimal Jalan Committee (2018) to balance surplus distribution and RBI's financial resilience.
- Risk Buffer: Mandates the RBI to maintain a Contingency Risk Buffer (CRB) between 5.5% and 6.5% of its balance sheet.
- Statutory Backing: Section 47 of the RBI Act, 1934 legally governs the transfer of this excess operating surplus to the government.
Cross-Topic Patterns
Forex operations driving RBI surplus
RBI interventions in the currency market (selling dollars to defend the rupee) yield significant realization gains, directly boosting the surplus available for transfer to the government.
Fiscal consolidation and sovereign ratings
Bumper non-tax revenues allow the government to sustain infrastructure capex without breaching fiscal deficit targets—a critical macroeconomic indicator closely monitored by sovereign credit rating agencies.

Expect a 2026 question mixing Bimal Jalan ECF limits (CRB 5.5-6.5%) with Budget receipt classifications (NDCR vs. Revenue).
Linked PYQs · 4
Linked PYQs · 4
- 2025PrelimsGS1
Which of the following are the sources of income for the Reserve Bank of India? I. Buying and selling Government bonds II. Buying and selling foreign currency III. Pension fund management IV. Lending to private companies V. Printing and distributing currency notes Select the correct answer using the code given below.
- 2025PrelimsGS1
Suppose the revenue expenditure is ₹ 80,000 crores and the revenue receipts of the Government are ₹60,000 crores. The Government budget also shows borrowings of ₹ 10,000 crores and interest payments of ₹ 6,000 crores. Which of the following statements are correct? I. Revenue deficit is ₹ 20,000 crores. II. Fiscal deficit is ₹ 10,000 crores. III. Primary deficit is ₹ 4,000 crores. Select the correct answer using the code given below.
- 2021MainsGS3
Distinguish between Capital Budget and Revenue Budget. Explain the components of both these Budgets.
- 2019MainsGS3
The public expenditure management is a challenge to the Government of India in the context of budget making during the post-liberalization period. Clarify it.
