RBI Financial Stability Report highlights banking sector resilience
Source:Indian Express ↗
Why It Matters
The Financial Stability Report is the premier official assessment of India's banking and economic health. Its findings on NPA trends, NBFC performance, and macroeconomic resilience are highly testable in both UPSC Prelims (conceptual questions on banking/inflation) and Mains (evaluating asset quality, central bank mandates, and systemic risks).
Summary
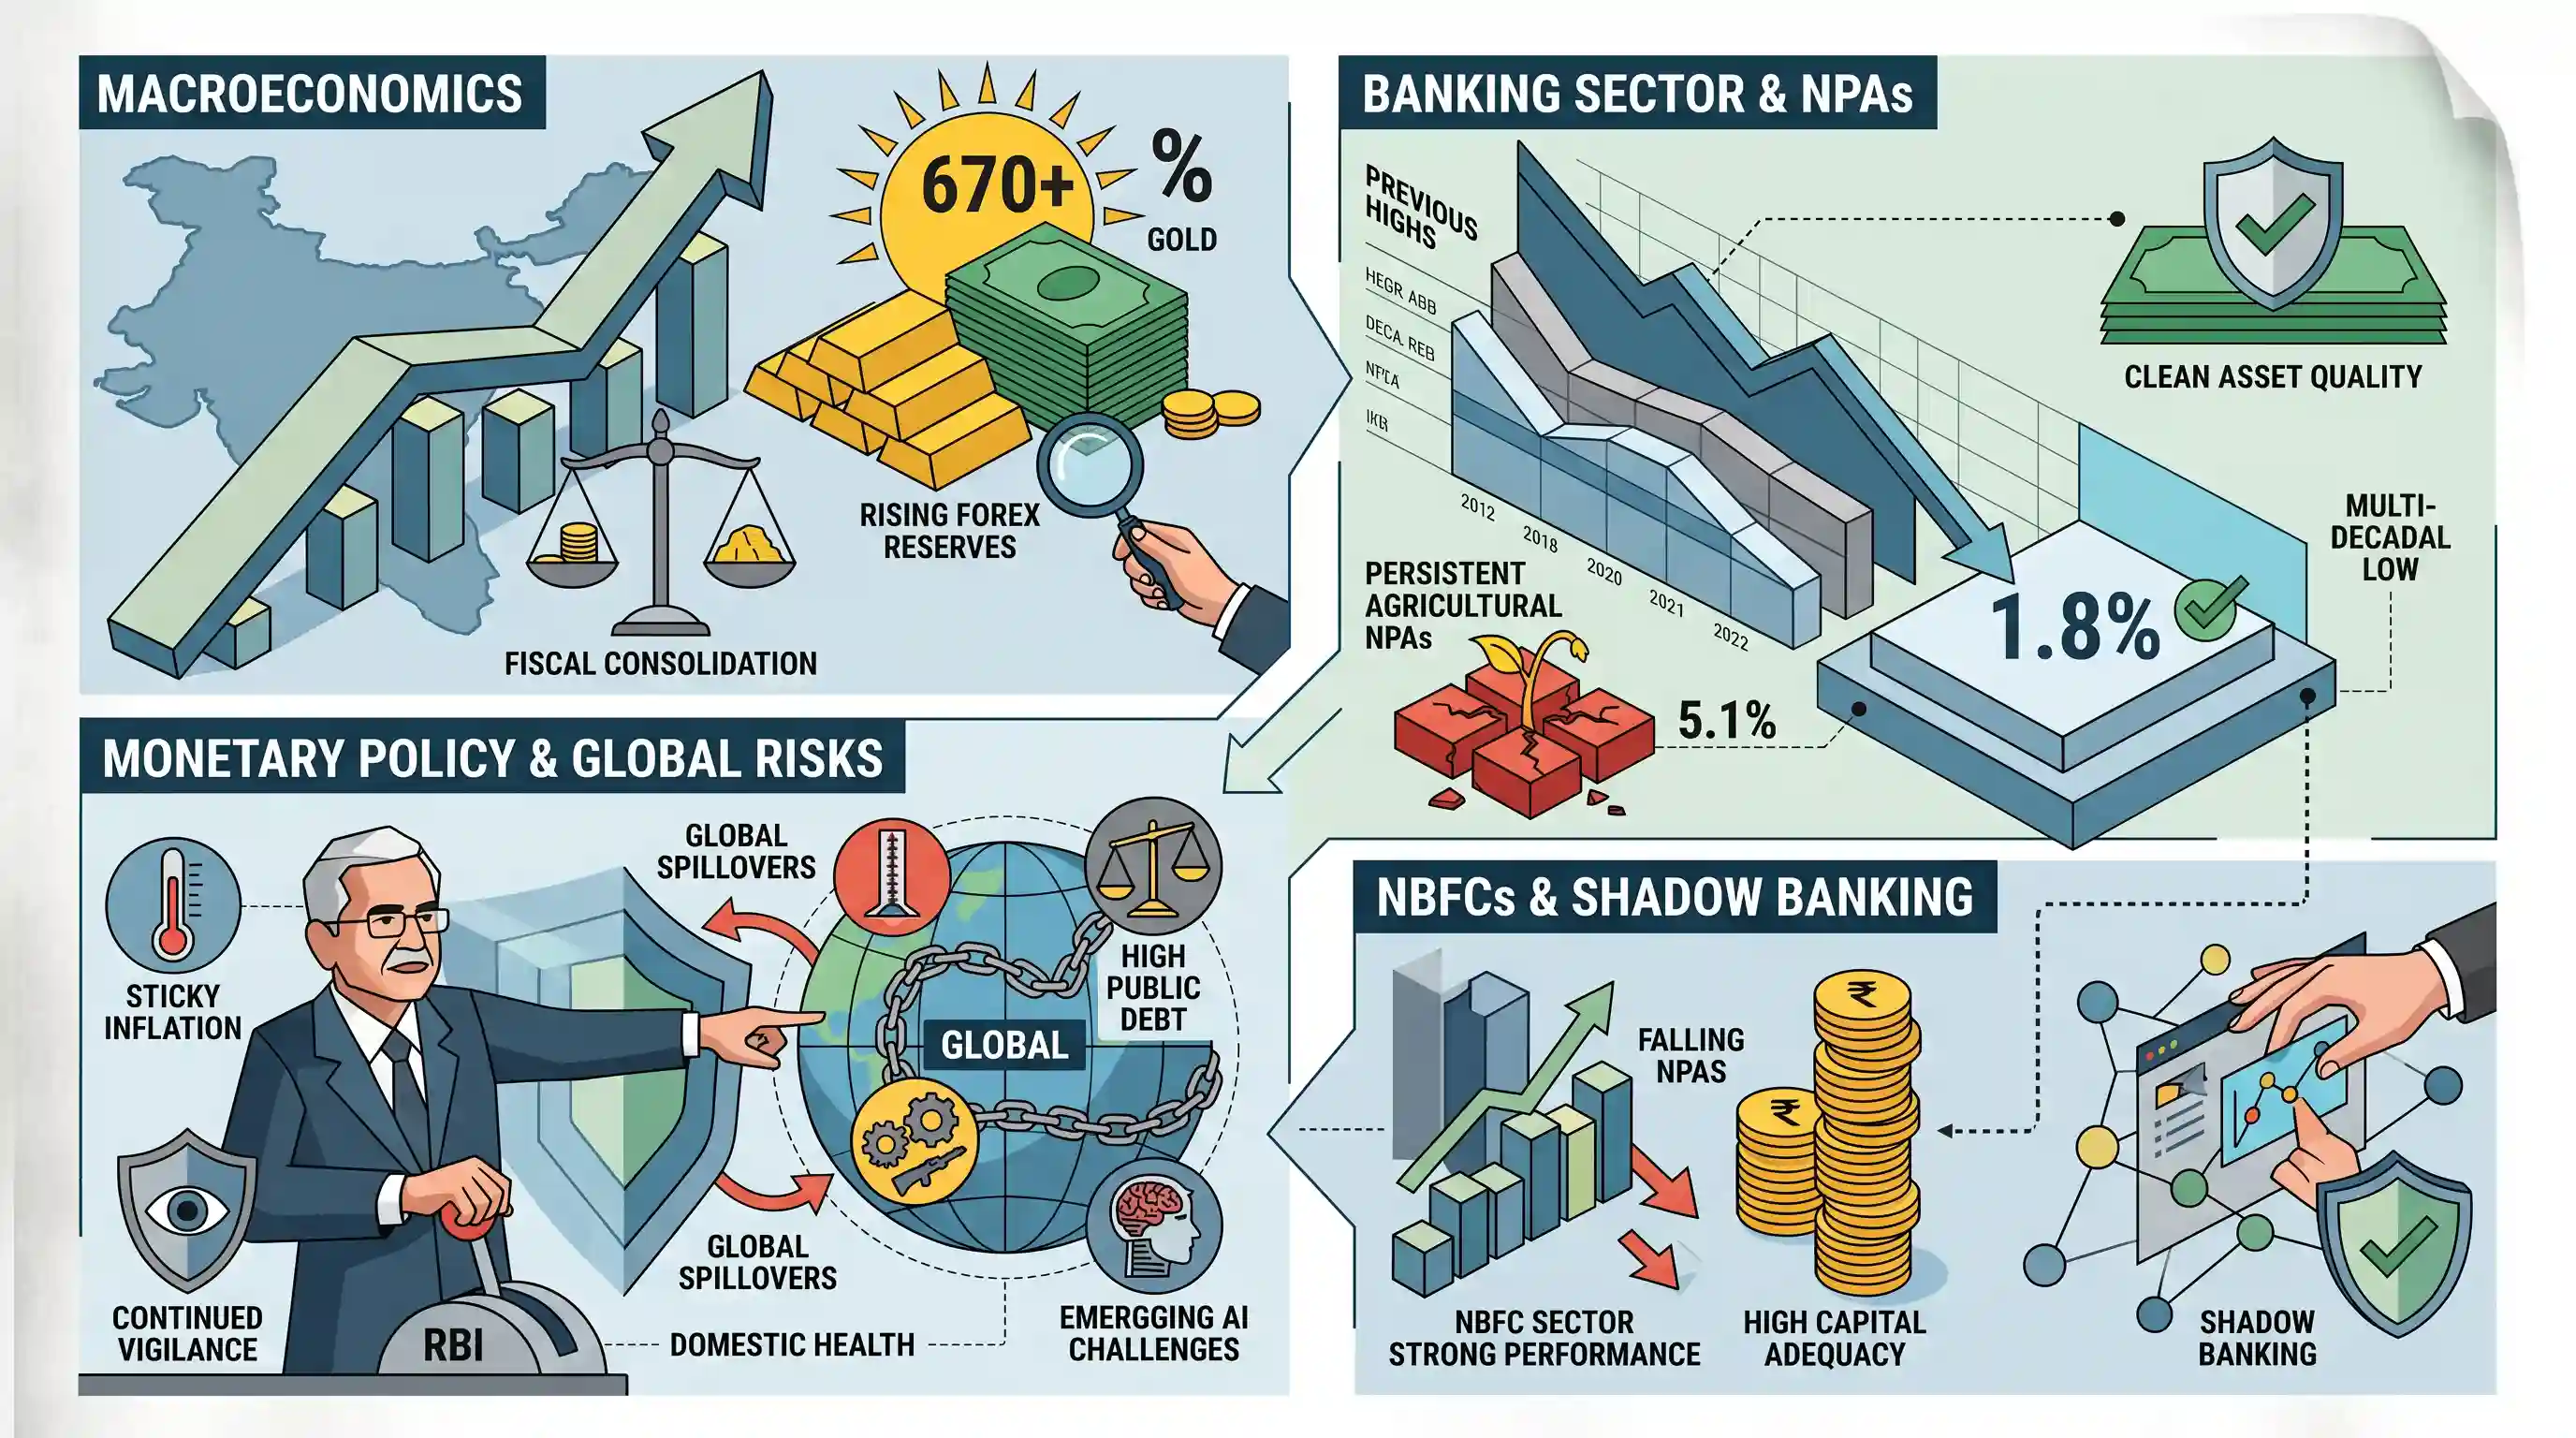
The Reserve Bank of India (RBI) has released its Financial Stability Report 2026, revealing a robust and resilient Indian financial sector amidst global uncertainties. The report highlights significant improvements in asset quality, with the gross non-performing asset (GNPA) ratio of scheduled commercial banks dropping to a multi-decadal low of 1.8%. The non-banking financial company (NBFC) sector also demonstrated strong performance with falling NPAs and high capital adequacy. However, RBI Governor Sanjay Malhotra cautioned against elevated global financial risks driven by sticky inflation, high public debt, geopolitical tensions, and the emerging challenges posed by Artificial Intelligence. While domestic macroeconomic fundamentals—including fiscal consolidation and rising forex reserves—remain strong, the RBI advises continued vigilance, particularly concerning persistent agricultural NPAs and global spillover effects.
Key Points
- The RBI's Financial Stability Report 2026 underscores the resilience of India's financial system against external shocks, high global public debt, and geopolitical fragmentation.
- Asset quality has notably improved, with the Gross Non-Performing Assets (GNPA) ratio of Scheduled Commercial Banks hitting a multi-decadal low of 1.8% in March 2026.
- Despite overall improvements, the agriculture sector retains the highest NPA ratio among major sectors, standing at 5.1%.
- NBFCs are demonstrating robust health with double-digit credit growth, high capital buffers, and a GNPA ratio that declined to 2.8%.
- RBI Governor Sanjay Malhotra highlighted emerging global risks, including sticky inflation, prolonged tight monetary policies, and the disruptive potential of Artificial Intelligence in finance.
Important Terms
Financial Stability Report (FSR)

A biannual RBI publication assessing the resilience of India's financial system, potential risks to stability, and the health of banking and non-banking sectors.
UPSC context
GS Paper III: Indian Economy. Tests understanding of systemic risk management and the health of the financial sector.
Gross Non-Performing Asset (GNPA) Ratio
A key metric representing the percentage of a bank's total loans that have not received interest or principal payments for 90 days or more.
UPSC context
GS Paper III: Banking. Crucial for understanding asset quality, bank profitability, and the 'Twin Balance Sheet' problem.
Capital to Risk-Weighted Assets Ratio (CRAR)
A measurement of a bank's available capital expressed as a percentage of its risk-weighted credit exposure, ensuring it can absorb a reasonable amount of loss.
UPSC context
GS Paper III: Banking Sector. Tests knowledge of Basel III norms and financial safety nets for depositors.
Non-Banking Financial Companies (NBFCs)
Entities providing bank-like financial services, such as loans and investments, without holding a full banking license or being part of the payment system.
UPSC context
GS Paper III: Economy. Focuses on shadow banking, credit flow to MSMEs, and systemic interconnectedness.
Fiscal Consolidation
A policy aimed at reducing the government's fiscal deficit and public debt-to-GDP ratio to ensure long-term macroeconomic stability and investor confidence.
UPSC context
GS Paper III: Government Budgeting. Vital for understanding fiscal discipline and its impact on inflation and growth.
Scheduled Commercial Banks (SCBs)
Banks listed in the Second Schedule of the RBI Act, 1934, including public, private, foreign, and regional rural banks, meeting specific capital and reserve criteria.
UPSC context
GS Paper III: Banking. Essential for understanding the formal credit structure and monetary policy transmission in India.
Financial Stability and Development Council (FSDC)
The apex-level body chaired by the Union Finance Minister to strengthen and institutionalize the mechanism for maintaining financial stability and inter-regulatory coordination.
UPSC context
GS Paper III: Statutory/Executive Bodies. Tests knowledge of India's financial regulatory architecture and crisis management framework.
Prelims Trap
The industrial and MSME sectors currently account for the highest NPA ratios in the Indian banking system.
Historically, corporate/industrial loans drove India's twin balance sheet problem. Currently, the agriculture sector holds the highest NPA ratio (5.1%).
Static Concepts Connected
What is the Financial Stability Report (FSR) and its relation to the FSDC?
- Publisher: Published bi-annually by the Reserve Bank of India on behalf of the Financial Stability and Development Council (FSDC).
- Core Purpose: Evaluates systemic risks to macro-financial stability and tests the resilience of the Indian financial sector.
- Methodology: Uses macro stress tests to evaluate how commercial banks would perform under baseline and adverse macroeconomic scenarios.
What is the Capital Adequacy Ratio (CAR) / CRAR for financial institutions?
- Definition: The ratio of a bank's capital to its risk-weighted assets and current liabilities, mandated under Basel norms.
- Components: Divided into Tier 1 (core equity, highly liquid) and Tier 2 (supplementary, less liquid) capital.
- Purpose: Ensures financial institutions have enough cushion to absorb a reasonable amount of loss before becoming insolvent, preventing systemic contagion.
Cross-Topic Patterns
AI in Finance & Systemic Cyber Risks
The RBI's warning on AI aligns with internal security topics. AI-driven algorithmic trading and deepfakes represent new vectors for financial fraud, accelerating the speed of potential systemic market crashes.
Farm NPAs and Priority Sector Lending
Persistently high agricultural NPAs (5.1%) connect to Priority Sector Lending (PSL) mandates and state farm loan waivers, which structurally challenge credit discipline despite overall banking sector recovery.

Expect a multi-statement Prelims question contrasting the multi-decadal low overall GNPA with the persistently high agricultural NPA.
Linked PYQs · 5
Linked PYQs · 5
- 2010PrelimsGS1
With reference to the Non-banking Financial Companies (NBFCs) in India, consider the following statements:
- 2016PrelimsGS1
'Global Financial Stability Report' is prepared by the
- 2022PrelimsGS1
In India, which one of the following is responsible for maintaining price stability by controlling inflation?
- 2024PrelimsGS1
Consider the following statements : 1. In India, Non-Banking Financial Companies can access the Liquidity Adjustment Facility window of the Reserve Bank of India. 2. In India, Foreign Institutional Investors can hold the Government Securities (G-Secs). 3. In India, Stock Exchanges can offer separate trading platforms for debts. Which of the statements given above is/are correct?
- 2026PrelimsGS1
Consider the following statements about the Non-Banking Financial Companies (NBFCs) in India : 1. NBFCs cannot accept demand deposits. 2. All the NBFCs operating in India have to be registered with the RBI. 3. NBFCs form part of the payment and settlement system and can issue cheque drawn on itself. 4. Deposit insurance facility of Deposit Insurance and Credit Guarantee Corporation (DICGC) is not available to the depositors of deposit taking NBFCs. Which of the statements given above is/are correct ?
