Income Tax Bill 2025 and Direct Tax Reforms
Source:The Hindu ↗
Why It Matters
The sweeping changes to the Income Tax Act represent a core component of India's economic reforms, touching upon GS3 (Direct Tax Reforms) and GS2 (the role of Parliamentary Committees in scrutinizing landmark legislation). Understanding the rationale behind shifting to a 'tax year' and reducing statutory complexity is vital for analyzing ease of compliance and governance.
Summary
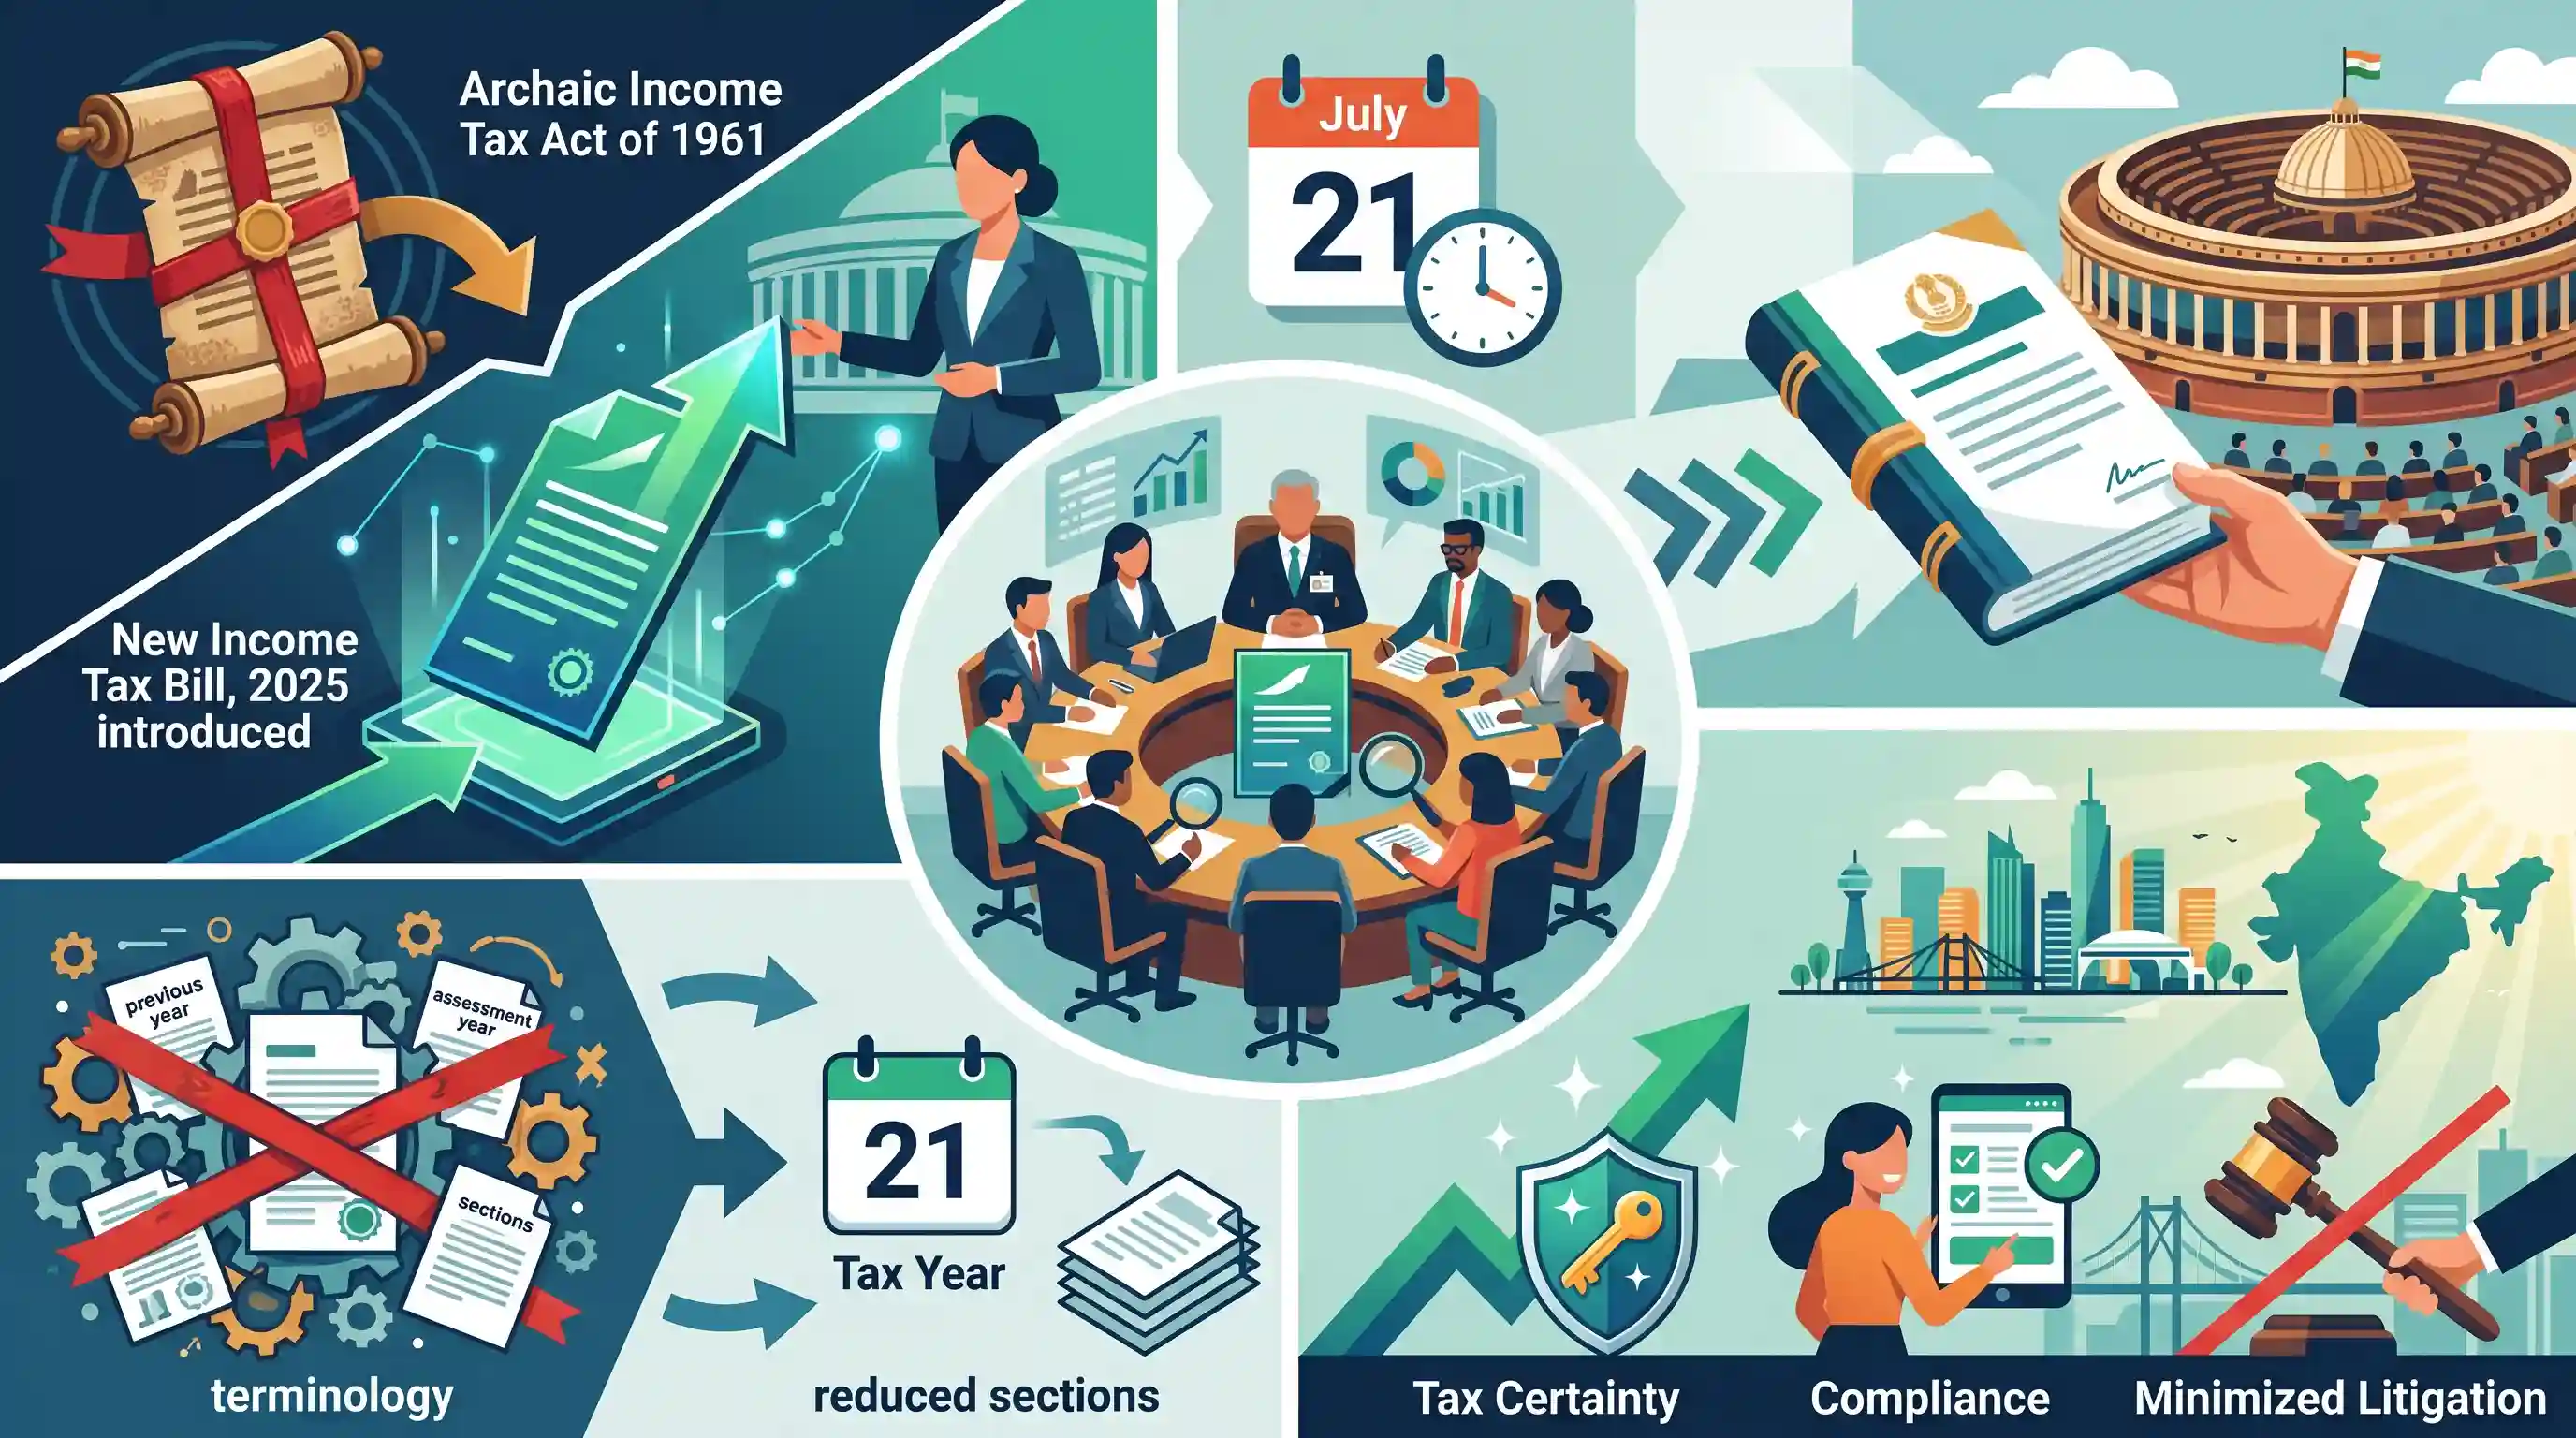
A Parliamentary Select Committee chaired by Baijayant Panda is scheduled to present its report on the new Income Tax Bill, 2025, to the Lok Sabha on July 21. The legislation, introduced by Finance Minister Nirmala Sitharaman, represents a major overhaul of India's direct tax regime by seeking to replace the archaic Income Tax Act of 1961. By significantly reducing the number of sections and simplifying tax terminology—such as replacing 'previous year' and 'assessment year' with a single 'tax year'—the Bill intends to enhance tax certainty, improve compliance, and minimize litigation.
Key Points
- The new Income Tax Bill, 2025 aims to replace the 64-year-old Income Tax Act of 1961 to simplify direct taxation in India.
- A 31-member Select Committee of the Lok Sabha, chaired by Baijayant Panda, is slated to table its report on the Bill by July 21.
- The simplified Bill cuts down the number of sections from 819 to 536, reduces chapters from 47 to 23, and halves the word count to 2.6 lakh.
- It introduces the concept of a 'tax year' (April 1 to March 31), effectively doing away with the legacy concepts of 'previous year' and 'assessment year'.
- The reform seeks to provide greater tax certainty, simplify the language for taxpayers, and significantly reduce the scope of litigation.
Important Terms
Income Tax Bill, 2025

Proposed legislation replacing the 1961 Act to overhaul India's direct tax regime. It aims to simplify terminology, reduce sections, and enhance compliance by introducing a unified 'tax year'.
UPSC context
GS Paper III: Indian Economy and Taxation; tests knowledge of contemporary fiscal reforms and direct tax administration.
Income Tax Act, 1961
The cornerstone legislation that has governed India's direct tax system since 1962. It established the dual concept of 'Previous Year' and 'Assessment Year' for tax liability calculation.
UPSC context
GS Paper III: Statutory frameworks; essential for understanding the evolution and challenges of India’s direct taxation.
Select Committee
An ad-hoc parliamentary panel constituted to examine a specific bill in detail. The Panda Committee scrutinized the 2025 Bill, inviting stakeholder feedback and suggesting over 285 amendments.
UPSC context
GS Paper II: Parliament and State Legislatures; tests knowledge of legislative scrutiny and the committee system's role.
Lok Sabha
The lower house of India’s bicameral Parliament. It holds exclusive power over Money Bills and plays a primary role in the introduction and passage of financial legislation.
UPSC context
GS Paper II: Indian Polity; fundamental to the legislative process and the principle of popular representation.
Tax Year
A unified 12-month period (April-March) introduced in the 2025 Bill to replace the confusing 'Previous Year' and 'Assessment Year' labels for earning and reporting income.
UPSC context
GS Paper III: Economic Development; significant for understanding technical simplifications in ease of doing business and tax compliance.
Prelims Trap
The Income Tax Bill 2025 was reviewed by a permanent Parliamentary Standing Committee.
Select Committees are ad hoc (temporary), created to scrutinize a specific bill, and dissolve upon submitting their report. They are not permanent Standing Committees.
Static Concepts Connected
What distinguishes a Select Committee from a Standing Committee?
- Ad-hoc Nature: Select Committees are temporary, formed to scrutinize a specific Bill, and dissolve immediately after submitting their report.
- Membership Structure: Usually comprises members from a single House (unless it's a Joint Select Committee), unlike Departmentally Related Standing Committees (DRSCs).
Why overhaul the 1961 Income Tax Act?
- Tax Certainty: Replaces archaic phrasing (e.g., separating previous and assessment years) to reduce subjective interpretation, enhancing predictability for taxpayers.
- Judicial Decongestion: The tax department is India's largest litigant but with low success rates. Simplifying the code helps unlock massive capital stuck in tribunals.
- Formalization Nudge: Trimming the Act from 819 to 536 sections lowers the compliance burden, nudging the informal sector toward formalization and improving the Tax-to-GDP ratio.
Cross-Topic Patterns
Tax certainty and FDI inflows
Replacing 'assessment years' with a unified 'tax year' directly supports 'Ease of Doing Business' by reducing interpretative tax litigation, historically a major hurdle for foreign direct investment in India.
Evolution of Parliamentary scrutiny
Sending major bills to Select Committees instead of permanent Standing Committees is a critical Mains GS-2 theme regarding the evolution and bypass of traditional parliamentary scrutiny mechanisms.

Expect a 2026 Prelims statement differentiating Select vs Standing Committees, and a GS3 Mains Q on how simplified tax codes spur GDP growth.
Linked PYQs · 3
Linked PYQs · 3
- 2021MainsGS2
Do Department-related Parliamentary Standing Committees keep the administration on its toes and inspire reverence for parliamentary control? Evaluate the working of such committees with suitable examples.
- 2018MainsGS3
Comment on the important changes introduced in respect of the Long-term Capital Gains Tax (LCGT) and Dividend Distribution Tax (DDT) in the Union Budget for 2018-2019.
- 2019MainsGS3
Enumerate the indirect taxes which have been subsumed in the Goods and Services Tax (GST) in India. Also, comment on the revenue implications of the GST introduced in India since July 2017.
