Ram temple trust adopts merit based process for CEO selection
Source:economic-times ↗
Why It Matters
The professionalization of the Shri Ram Janmbhoomi Teerth Kshetra Trust provides a prime example of large Indian religious bodies adopting modern governance, emphasizing efficiency, transparency, and meritocracy over traditional or personal criteria.
Summary
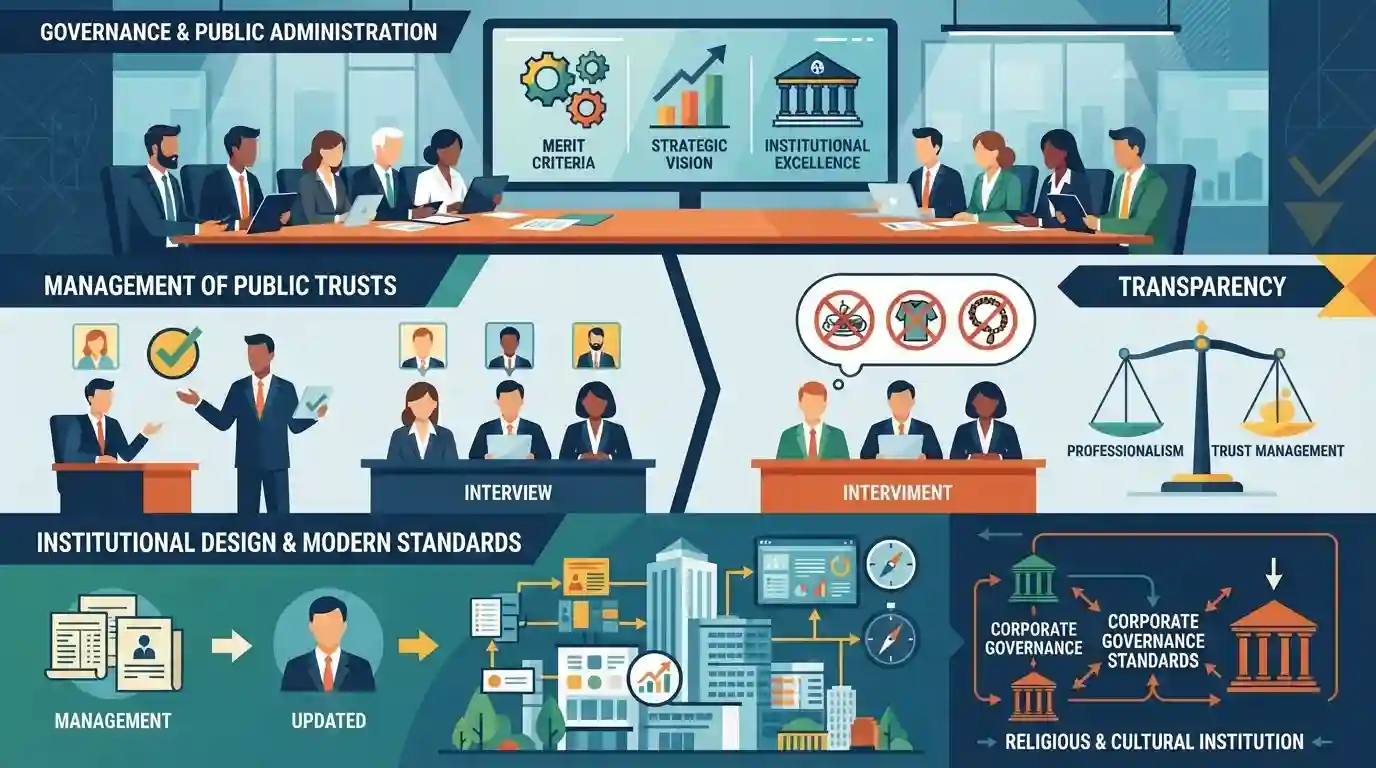
The search committee for the Chief Executive Officer (CEO) of the Shri Ram Janmbhoomi Teerth Kshetra Trust evaluated candidates strictly on merit, institutional excellence, and strategic vision. It was clarified that the panel refrained from asking personal or religious questions regarding food habits, attire, or daily religious practices. This transparent, professional recruitment approach reflects a growing trend of applying modern corporate governance standards to the management of large-scale religious and cultural institutions.
Key Points
- The Shri Ram Janmbhoomi Teerth Kshetra Trust is conducting a professional, merit-based selection process for the position of Chief Executive Officer (CEO).
- The evaluation criteria focused on candidates' professional experience, strategic vision, execution capabilities, and institutional excellence.
- The search committee explicitly clarified that no questions were asked regarding candidates' personal religious practices, food habits (vegetarianism), alcohol consumption, or daily rituals.
- The approach signifies a shift toward modern corporate governance, transparency, and non-discrimination in the administration of large religious public trusts.
Important Terms
Shri Ram Janmbhoomi Teerth Kshetra Trust

A trust established by the Government of India in 2020 following the Supreme Court verdict, tasked with overseeing the construction and management of the Ram Temple in Ayodhya.
UPSC context
Relevant for GS Paper 2 (Statutory/Non-statutory bodies) and GS 4 (Trust-based governance, accountability in managing large cultural institutions).
Trust-Based Governance
An approach to administration emphasizing transparency, self-certification, reduced rigid compliance, and maximizing public confidence, moving away from excessive control toward facilitative oversight.
UPSC context
Essential for GS 2 (Governance) and GS 4 (Ethics in Administration) concerning transparency, easing citizen engagement, and institutional reform.
Probity in Governance
The moral foundation in public administration requiring integrity, honesty, transparency, and the ethical use of public authority strictly for lawful public purposes.
UPSC context
A core GS Paper 4 (Ethics) topic, testing candidates on accountability, preventing misuse of authority, and sustaining public trust.
Prelims Trap
The Constitution prohibits any religious criteria for employment in institutions established or regulated by the State.
Article 16(5) explicitly allows laws to mandate that incumbents of offices connected to religious institutions must profess that particular religion.
Static Concepts Connected
How does the Constitution separate religious freedom from the secular administration of temples?
- Article 26(b) vs 26(d): Denominations manage 'matters of religion' as a fundamental right, but the State can regulate the 'administration of property' according to law.
- Article 16(5) Exception: Provides an exception to non-discrimination in public employment, allowing religious criteria for offices connected to religious or denominational institutions.
- Essential Religious Practices: SC doctrine established in the Shirur Mutt case protects core rituals but allows the state to regulate secular, financial, or administrative management.
Cross-Topic Patterns
Corporate Governance in Religious Trusts
Links GS-2 (Governance) and GS-4 (Ethics). Modernizing temple boards with CEO-style merit-based management mirrors institutional trends previously seen in the Tirupati and Vaishno Devi shrine boards.
Essential Religious Practices Doctrine
The distinction between a CEO's secular duties and a priest's spiritual duties roots back to the SC's ERP doctrine (Shirur Mutt case) defining permissible state regulation of religion.

Prelims 2026 may test Article 16(5) exceptions regarding religious employment, mixed with Article 26(d) on secular management of trusts.
Linked PYQs · 1
Linked PYQs · 1
- 2024UPPSC_PRELIMSGS1
Which of the following statements are correct with regard to ICT-based e-Governance? 1. e-Governance reduces the transparency of Government. 2. e-Governance reduces the cost of Government. 3. e-Governance increases citizens input into Government. 4. e-Governance increases bureaucratic red tapism. Select the correct answer from the codes given below:
