Delhi Excise Policy and State Revenue Governance
Source:Indian Express ↗
Why It Matters
The frequent changes in Delhi's excise policy highlight significant governance challenges, including the importance of transparency in public policy formulation, the critical role of constitutional bodies like the CAG in ensuring financial accountability, and the complexities of inter-agency dynamics involving the CBI and the Lieutenant Governor in the National Capital Territory.
Summary
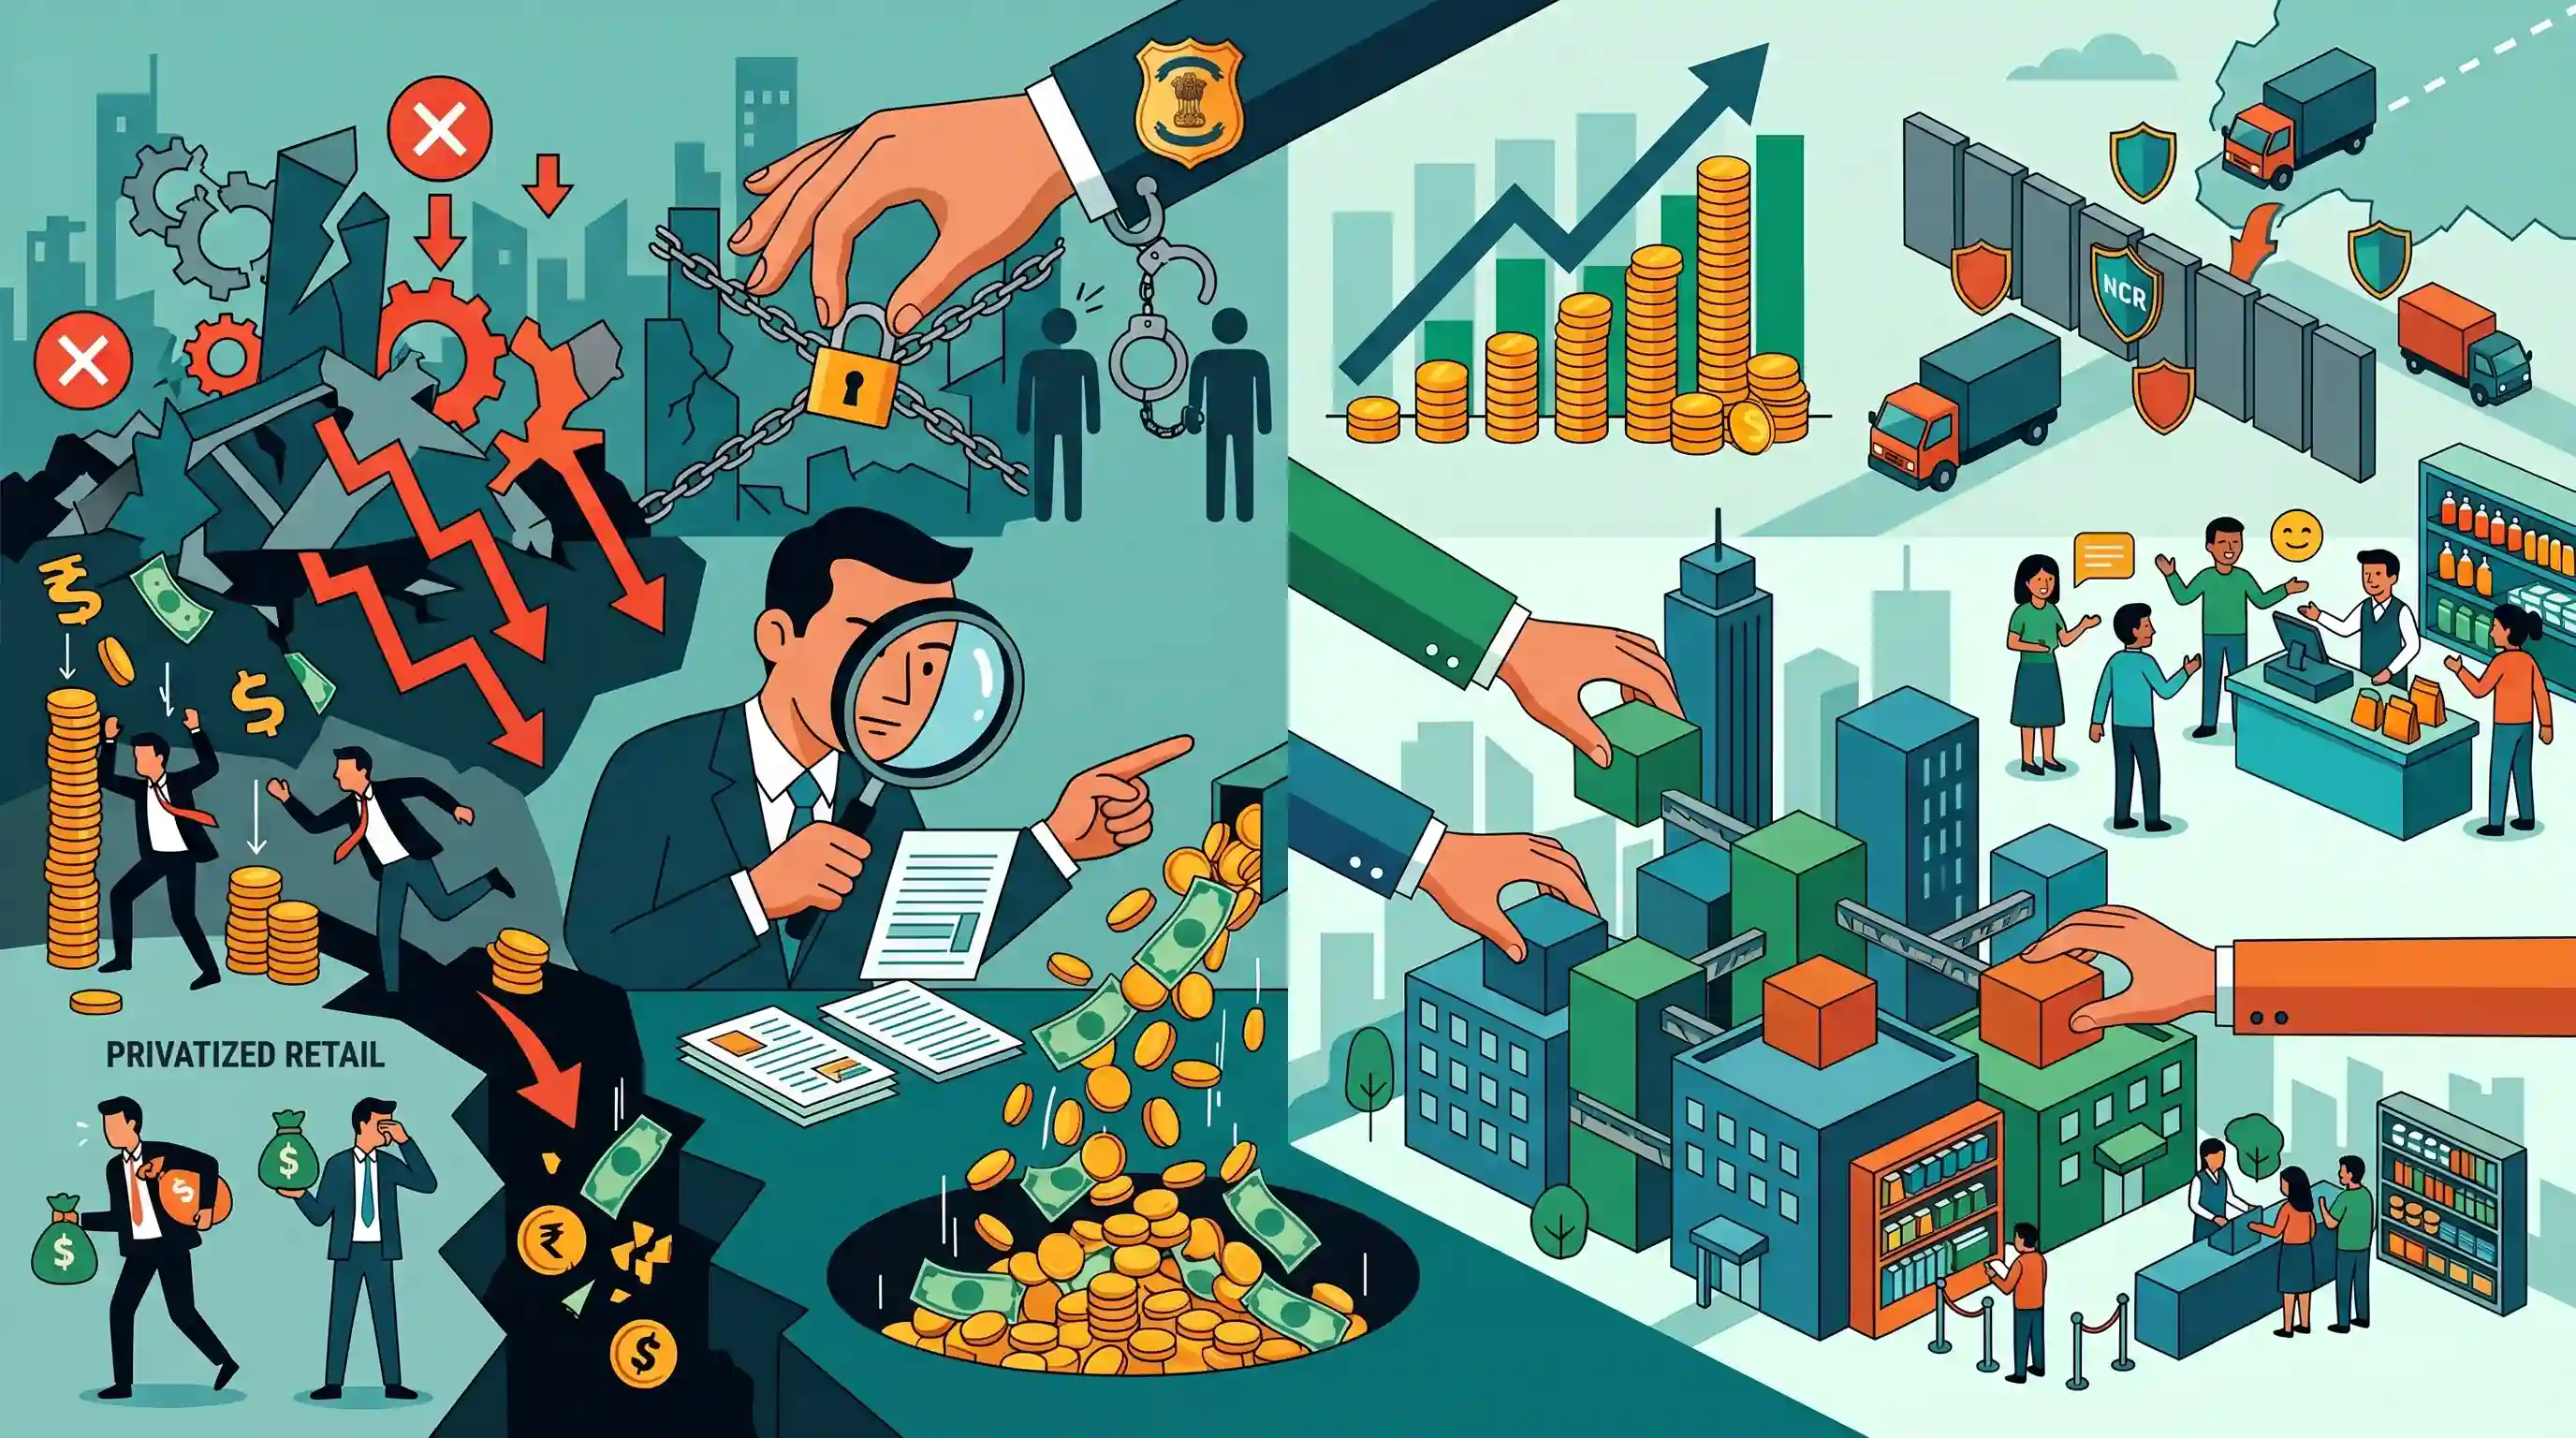
The Delhi government is preparing to launch a new excise policy focused on maximizing revenue, curbing illegal liquor smuggling from the NCR, and enhancing the customer experience. Unlike the previous AAP government's controversial 2021 policy, which privatized retail and was eventually scrapped following a CBI probe into alleged irregularities, the new policy will likely retain retail control within four government-run corporations. The urgency for a robust policy is underscored by a recent CAG report that identified a cumulative revenue loss of over Rs 2,000 crore under the previous regime.
Key Points
- Delhi Chief Minister Rekha Gupta announced that a new excise policy is being drafted to maximize state revenue and prevent financial losses.
- The new policy aims to curb illegal liquor smuggling from neighboring NCR regions and improve the overall customer experience.
- Retail liquor sales are expected to remain under the control of four government-run corporations, contrasting with the controversial 2021 policy that privatized retail.
- The previous excise policy, implemented by the AAP government, was scrapped after Lieutenant Governor VK Saxena recommended a CBI probe into alleged irregularities.
- A recent CAG report revealed that the previous excise policy resulted in a cumulative loss of over Rs 2,000 crore for the Delhi government between 2021 and 2022.
Important Terms
Comptroller and Auditor General (CAG)

A constitutional body under Article 148 that audits all receipts and expenditures of the Union and State governments to ensure financial accountability and transparency.
UPSC context
GS II: Constitutional Bodies; crucial for topics on accountability, financial oversight, and reports on policy implementation failures.
Central Bureau of Investigation (CBI)
The premier central investigative agency of India, deriving its power from the Delhi Special Police Establishment Act, 1946, primarily handling anti-corruption and economic offenses.
UPSC context
GS II: Statutory/Regulatory Bodies; tests knowledge of investigative jurisdiction and federalism (general consent issues).
Delhi Excise Policy 2021-22
A controversial 2021 framework that privatized liquor retail in Delhi, scrapped in 2022 following a CAG report alleging a ₹2,000 crore revenue loss and a CBI probe.
UPSC context
GS II: Government Policies and Interventions; an important case study for issues in policy design, implementation, and revenue leakages.
Article 239AA
The specific provision added by the 69th Amendment Act (1991) that grants special status to Delhi, establishing an elected Legislative Assembly and a Lieutenant Governor.
UPSC context
GS II: Indian Constitution/Federalism; central to the 'LG vs. Elected Government' power struggle in the National Capital Territory.
Excise Duty
An indirect tax levied on the production or manufacture of goods within a country; while most were subsumed by GST, it remains applicable to alcohol and petroleum.
UPSC context
GS III: Indian Economy/Fiscal Policy; tests understanding of indirect tax structures and State vs. Union revenue sources.
Delhi State Industrial and Infrastructure Development Corporation (DSIIDC)
A state-owned corporation responsible for industrial and infrastructure growth in Delhi, now part of the retail liquor distribution under the government-controlled model.
UPSC context
GS II/III: Role of Public Sector Undertakings (PSUs) in implementing state policies and ensuring non-monopolistic retail services.
Prelims Trap
"Excise duty on alcoholic liquor for human consumption has been subsumed under the Goods and Services Tax (GST)."
Article 366(12A) of the Constitution explicitly excludes alcoholic liquor for human consumption from GST. It remains under the exclusive taxation power of states (Entry 51).
Static Concepts Connected
How is alcoholic liquor taxed under the Indian Constitution?
- State List: Entry 8 governs the production and sale, while Entry 51 grants states the exclusive power to levy excise duties on alcoholic liquor for human consumption.
- GST Exclusion: Article 366(12A) explicitly excludes taxes on the supply of alcoholic liquor for human consumption from the definition of GST.
- Revenue Importance: Because it is outside GST, excise on liquor remains one of the largest sources of Own Tax Revenue (OTR) for state governments today.
What are the LG's powers in Delhi during disputes with the Council of Ministers?
- Presidential Referral: Under Article 239AA(4), if a difference of opinion arises, the Lieutenant Governor must refer the matter to the President for a final decision.
- Urgency Clause: Unlike State Governors, the Delhi LG holds a special power to take immediate action on urgent matters while pending the President's decision.
Cross-Topic Patterns
CAG's propriety audit mandate
The CAG's report on revenue loss highlights its 'propriety audit' power, which evaluates whether government policies result in systemic financial inefficiencies, going beyond mere legal compliance of expenditure.
CBI jurisdiction: UTs vs States
The LG recommended a CBI probe seamlessly because, under the DSPE Act, the CBI has original jurisdiction in Delhi (a UT), avoiding the general consent requirement applicable to full-fledged states.

Expect a tricky Prelims multi-statement question linking GST constitutional exclusions (Art 366) with State List taxation powers (Entry 51).
Linked PYQs · 3
Linked PYQs · 3
- 2018MainsGS2
“The Comptroller and Auditor General (CAG) has a very vital role to play.” Explain how this is reflected in the method and terms of his appointment as well as the range of powers he can exercise.
- 2024MainsGS2
“The duty of the Comptroller and Auditor General is not merely to ensure the legality of expenditure but also its propriety.” Comment.
- 2021MainsGS2
The jurisdiction of the Central Bureau of Investigation (CBI) regarding lodging an FIR and conducting probe within a particular State is being questioned by various States. However, the power of the States to withhold consent to the CBI is not absolute. Explain with special reference to the federal character of India.
