Municipal Corporation Finances and Capital Expenditure Allocations
Source:Indian Express ↗
Why It Matters
It provides a highly relevant case study for GS2 (devolution of finances to local bodies under the 74th Amendment) and GS3 (capital vs. revenue budgeting, urban infrastructure), illustrating how empowered municipalities can drive systemic urban development.
Summary
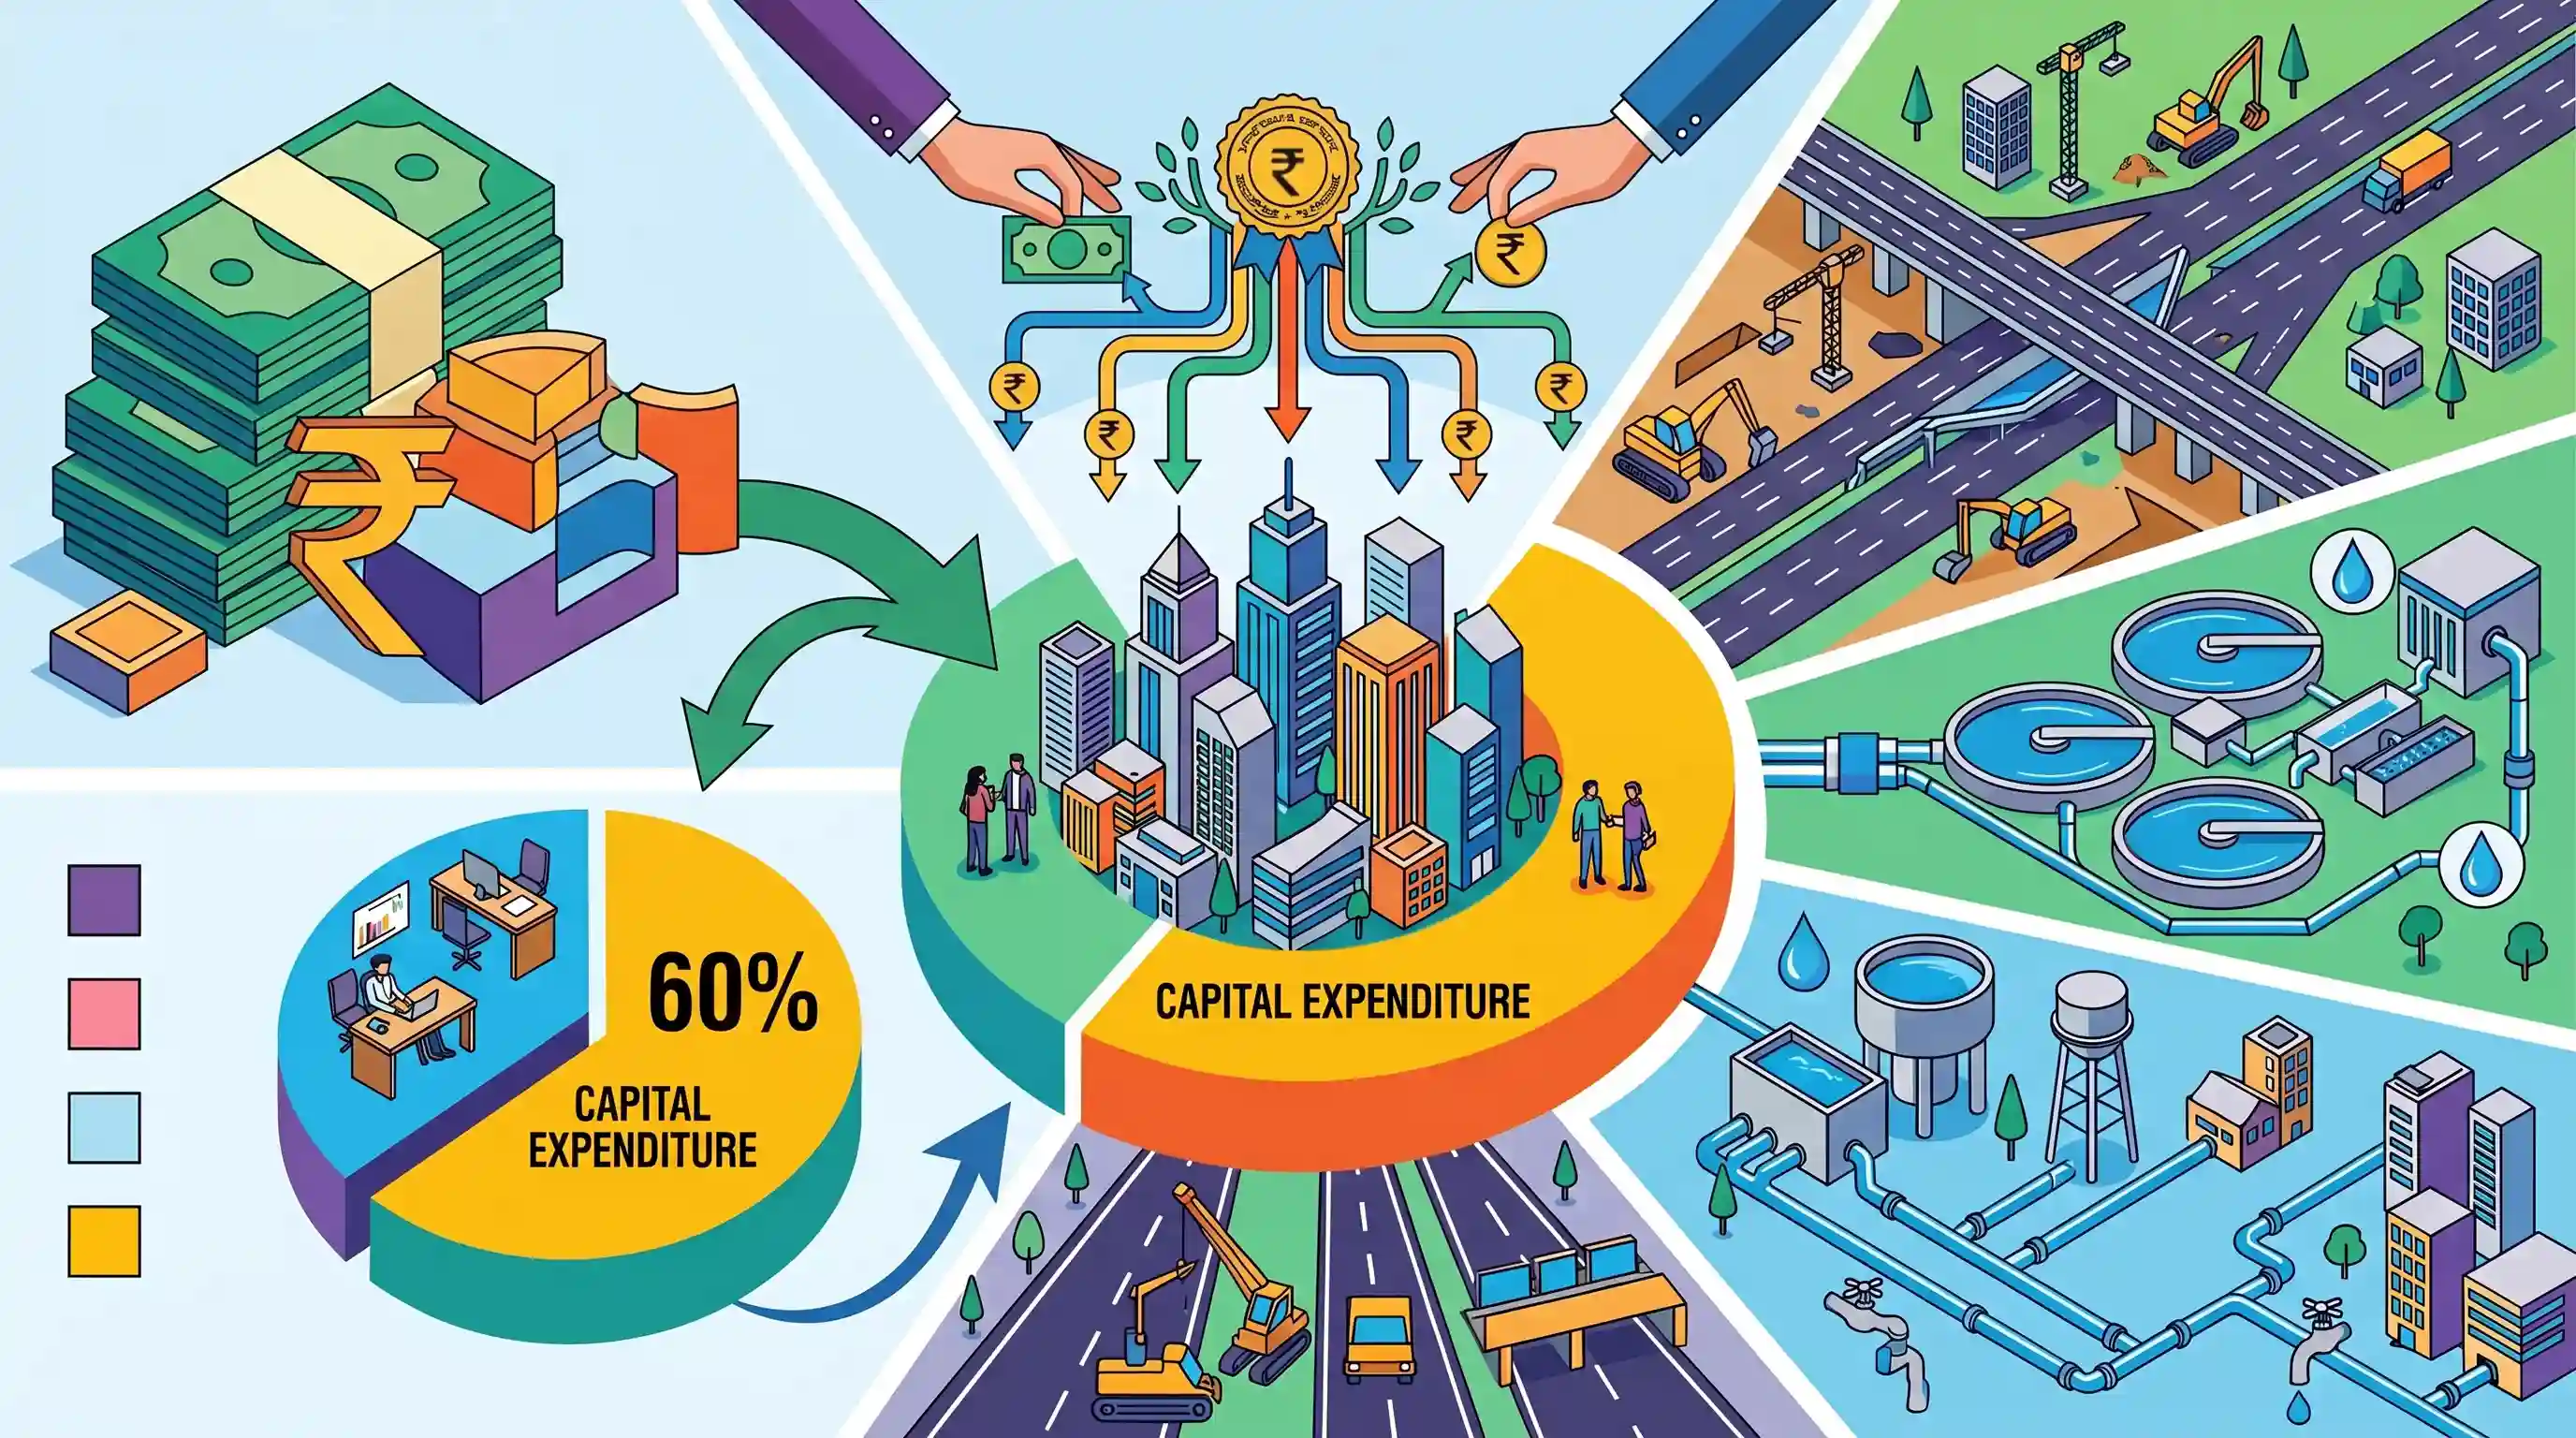
The Brihanmumbai Municipal Corporation (BMC) has unveiled a record ₹80,952-crore municipal budget with a significant 60% allocation earmarked for capital works. The budget prioritizes critical urban infrastructure development, including roads, sewage treatment plants, and water supply projects. This massive financial outlay highlights the capacity of large Urban Local Bodies (ULBs) to undertake long-term asset creation and addresses persistent challenges associated with rapid urbanization.
Key Points
- The BMC proposed a massive ₹80,952-crore budget, underscoring the vast financial scale of major urban local bodies (ULBs), which often exceeds the budgets of smaller states.
- A record 60% of the budget is allocated towards capital expenditure, prioritizing long-term asset creation over routine revenue expenditure.
- Key infrastructure focus areas include roads, sewage treatment plants (STPs), solid waste management, and water supply projects to address urban bottlenecks.
- The budget serves as a model for municipal financial empowerment, demonstrating how ULBs can mobilize resources to independently drive large-scale urban infrastructure transformations.
Important Terms
74th Constitutional Amendment Act

Enacted in 1992, it constitutionalized Urban Local Bodies, adding Part IXA and the 12th Schedule to ensure democratic decentralization and regular local elections.
UPSC context
GS Paper 2 (Polity); tests the legal framework for urban decentralization and the three-tier governance structure.
Brihanmumbai Municipal Corporation (BMC)
India’s wealthiest municipal corporation, established in 1888, managing Mumbai's civic infrastructure with a budget often exceeding that of several smaller Indian states.
UPSC context
GS Paper 2 (Governance); acts as a case study for mega-city management and ULB financial autonomy.
Urban Local Bodies (ULBs)
Smallest units of urban self-government (Nagar Panchayats, Municipal Councils, Municipal Corporations) mandated to manage local civic affairs and service delivery.
UPSC context
GS Paper 2 (Polity/Governance); focuses on grassroots democracy and the functional effectiveness of local government.
Capital Expenditure (CapEx)
Spending on physical assets like infrastructure (roads, bridges) that create long-term assets and enhance the economy's productive capacity.
UPSC context
GS Paper 3 (Economy); vital for analyzing the quality of government spending and asset creation.
Revenue Expenditure (RevEx)
Recurring government spending on day-to-day operations (salaries, pensions, subsidies) that does not result in the creation of permanent assets.
UPSC context
GS Paper 3 (Economy); central to understanding fiscal sustainability and recurring budget liabilities.
Devolution of Powers
The transfer of funds, functions, and functionaries from higher levels of government to local bodies to enable self-governance.
UPSC context
GS Paper 2 (Polity); key to evaluating the success of democratic decentralization and federalism.
State Finance Commission (SFC)
A constitutional body (Article 243Y) that recommends the distribution of tax revenues between the State and Urban Local Bodies.
UPSC context
GS Paper 2 (Polity); tests knowledge of fiscal federalism and local body financing mechanisms.
Twelfth Schedule
A constitutional list of 18 functional responsibilities (e.g., urban planning, sanitation) assigned to municipalities under the 74th Amendment Act.
UPSC context
GS Paper 2 (Polity); frequently tested for the functional jurisdiction of urban local governments.
Prelims Trap
ULBs receive a constitutionally guaranteed direct share of GST revenues to compensate for subsumed local taxes.
GST subsumed major local taxes like octroi, but the Constitution does not mandate a direct GST share for ULBs. Devolution relies entirely on non-binding State Finance Commission recommendations.
Static Concepts Connected
How does the Constitution provide for the financial empowerment of Municipalities?
- Article 243X: Empowers state legislatures to authorize municipalities to levy, collect, and appropriate taxes, duties, tolls, and fees.
- Article 243Y: Mandates the State Finance Commission to review the financial position of municipalities and recommend tax devolution and grants-in-aid.
- 12th Schedule: Lists 18 functional items (like urban planning and solid waste management) but does not guarantee an independent tax base.
What distinguishes Capital Expenditure (Capex) from Revenue Expenditure?
- Asset Creation: Capex creates physical/financial assets (e.g., roads, STPs) or reduces liabilities, while revenue expenditure does neither.
- Nature of Outlay: Revenue expenditure handles routine, recurring costs (salaries, maintenance), whereas Capex involves long-term, non-recurring investments that boost future productive capacity.
Cross-Topic Patterns
Municipal Bonds & SEBI guidelines
Heavy capital outlays for urban infrastructure require alternative financing. Linking ULB credit ratings to SEBI's municipal bond framework addresses the severe fiscal imbalance seen in Indian cities.
Fiscal federalism after GST rollout
The introduction of GST subsumed local taxes like octroi without a compensatory mechanism, crippling independent municipal revenue and increasing their reliance on state grants.

Expect a multi-statement question in 2026 linking the 74th CAA's 12th Schedule with the crippling impact of GST on independent ULB taxes.
Linked PYQs · 4
Linked PYQs · 4
- 2023MainsGS2
“The states in India seem reluctant to empower urban local bodies both functionally as well as financially.” Comment.
- 2021MainsGS3
Distinguish between Capital Budget and Revenue Budget. Explain the components of both these Budgets.
- 2017MainsGS1
"The growth of cities as I.T. hubs has opened up new avenues of employment, but has also created new problems." Substantiate this statement with examples.
- 2024PrelimsGS1
Which of the following statements are correct about the Constitution of India? 1. Powers of the Municipalities are given in Part IX A of the Constitution. 2. Emergency provisions are given in Part XVIII of the Constitution. 3. Provisions related to the amendment of the Constitution are given in Part XX of the Constitution. Select the answer using the code given below :
