KSWIFT portal streamlines professional tax compliance for MSMEs
Source:The Hindu ↗
Why It Matters
Demonstrates a practical state-level e-governance model (KSWIFT) that reduces regulatory friction and compliance burdens for MSMEs. It serves as a strong case study for GS2 (E-governance successes) and GS3 (Ease of Doing Business, MSME promotion).
Summary
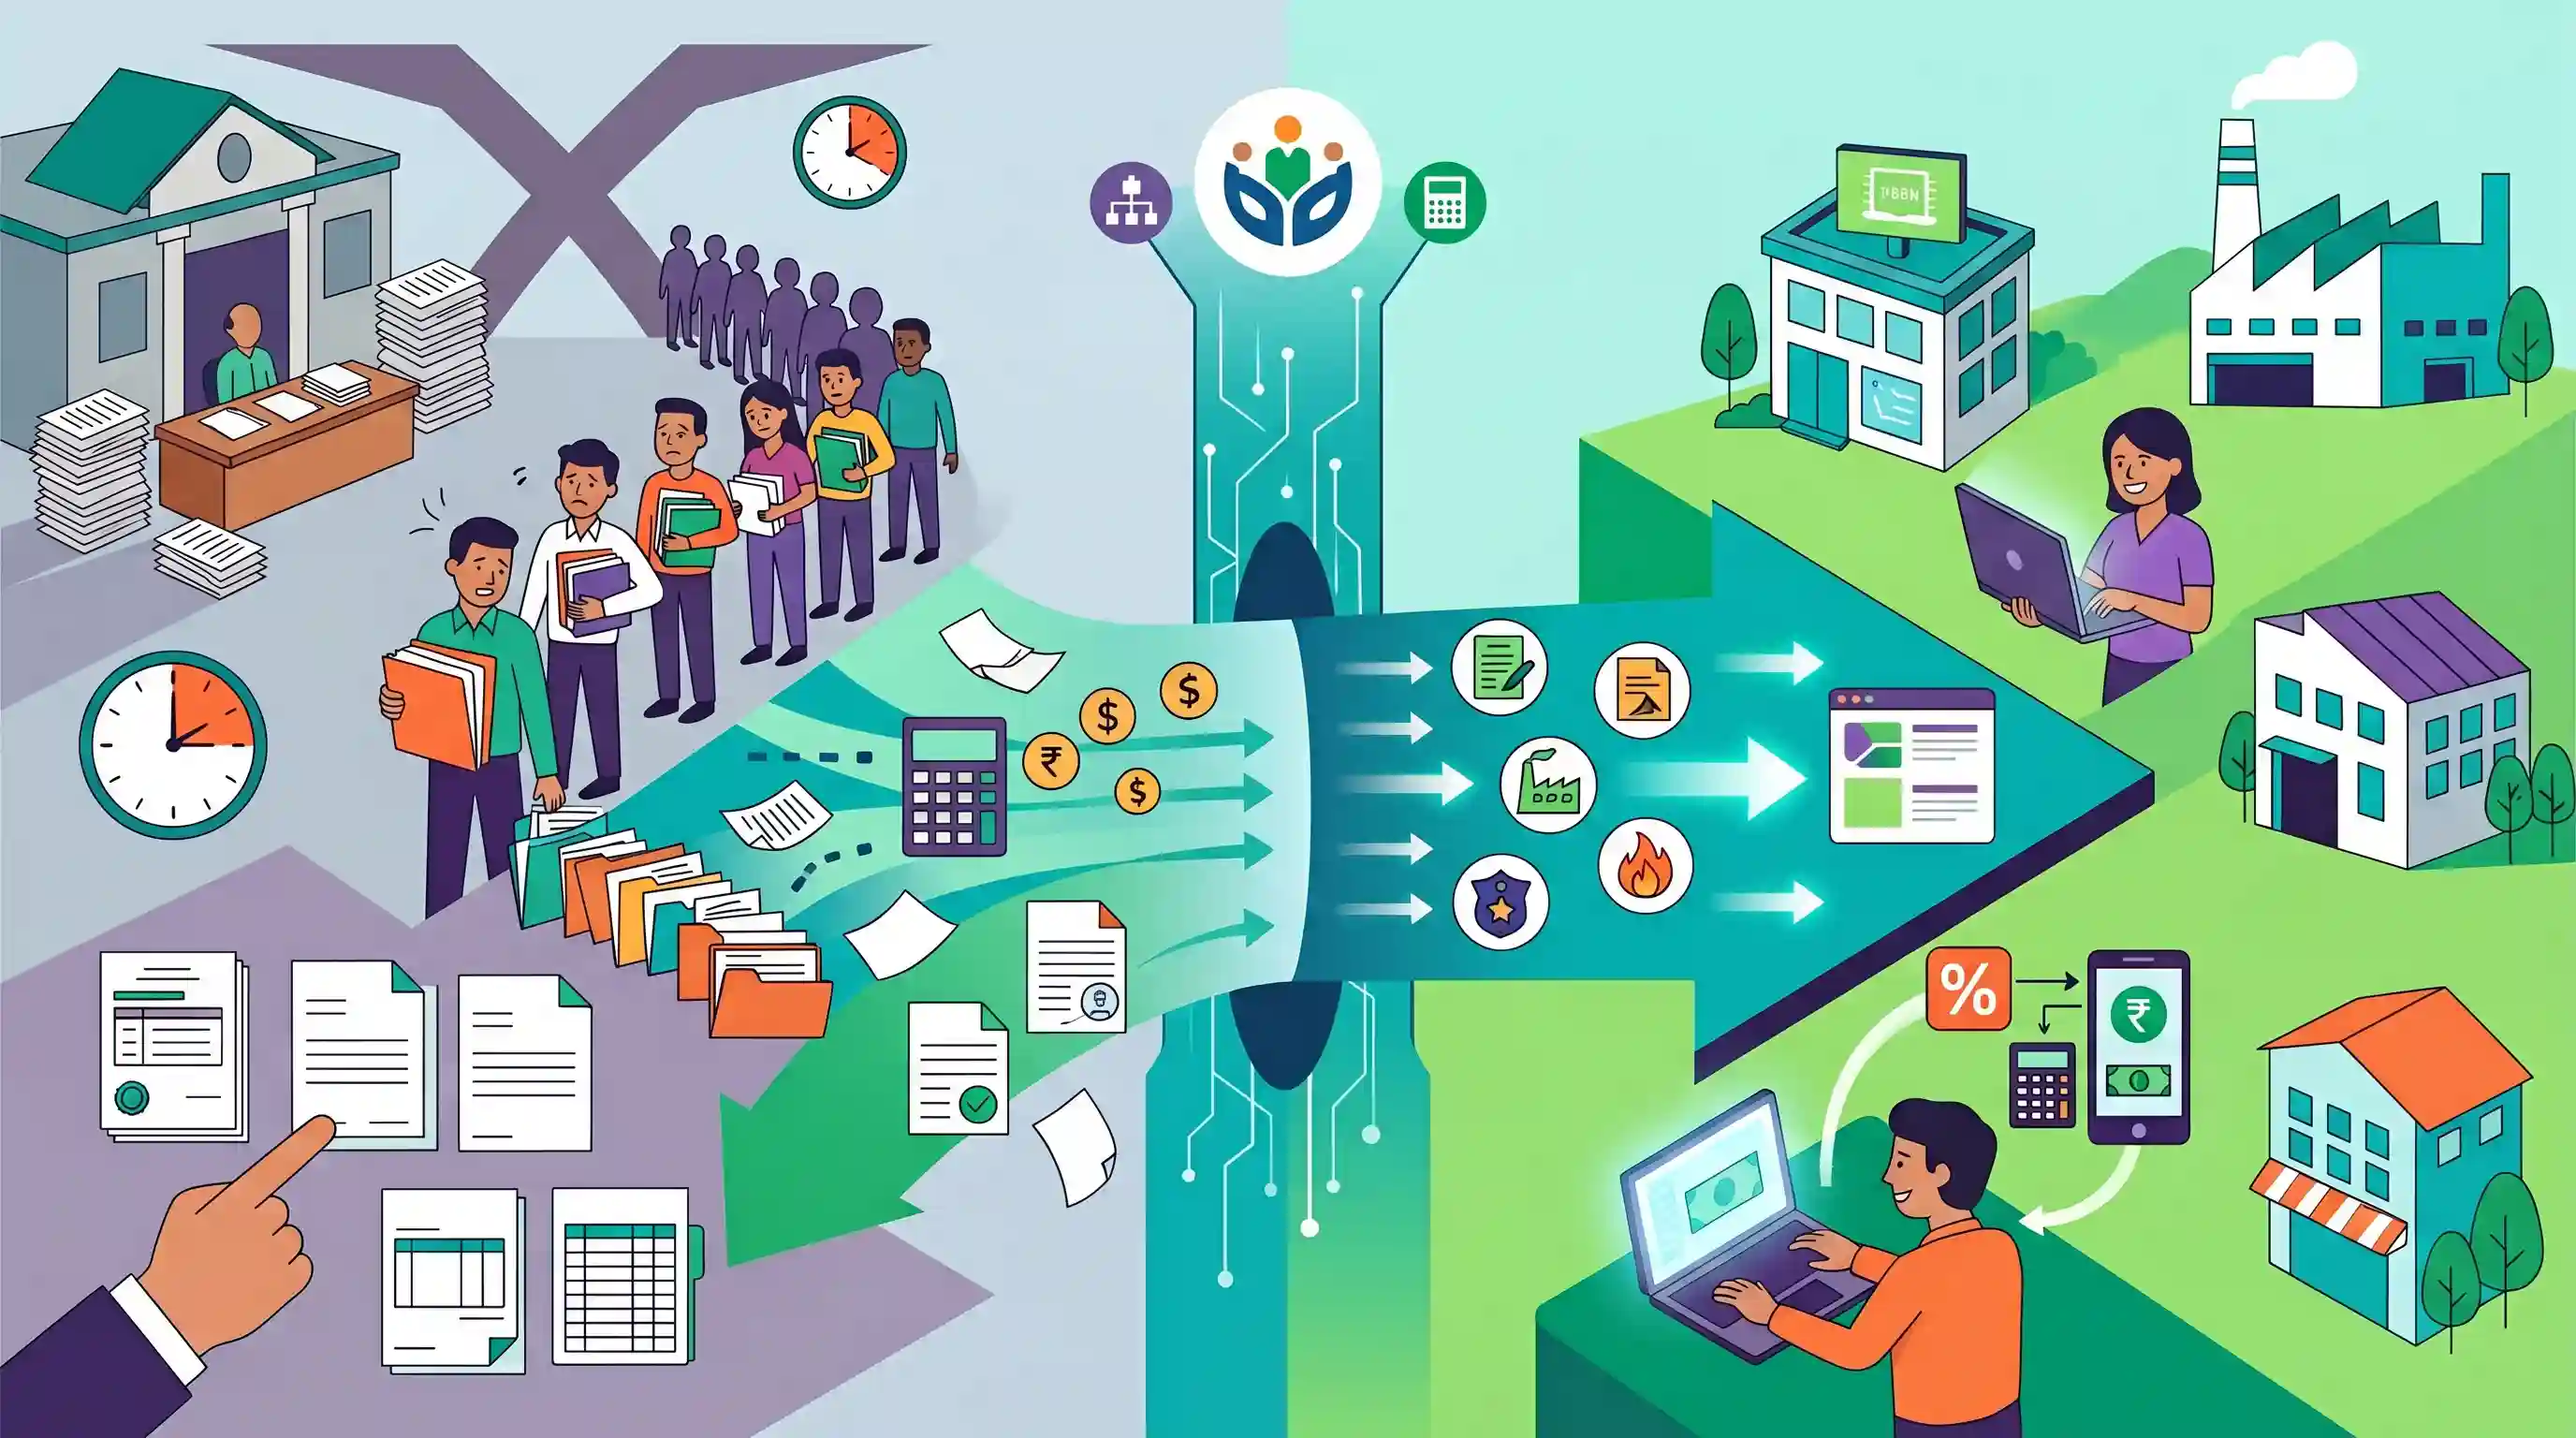
Kerala has upgraded its KSWIFT (Kerala Single Window Interface for Fast and Transparent Clearance) portal to allow MSMEs to calculate and pay professional tax online. Facilitated by the Kerala State Industrial Development Corporation (KSIDC), this e-governance initiative eliminates the need for entrepreneurs to physically visit local body offices. By consolidating over 120 services across 21 departments into a single platform, the state aims to reduce procedural delays, enhance transparency, and significantly improve the Ease of Doing Business for small enterprises.
Key Points
- Kerala's single-window clearance portal, KSWIFT, has introduced a feature allowing MSMEs to manage professional tax payments and returns online.
- The update removes the need for entrepreneurs to physically visit local self-government institutions, simplifying the regulatory compliance burden.
- KSWIFT provides access to over 120 services from approximately 21 state government departments to support business establishment and operations.
- The initiative is spearheaded by KSIDC as part of Kerala's broader efforts to improve the Ease of Doing Business (EoDB).
Important Terms
KSWIFT (Kerala Single Window Interface for Fast and Transparent Clearance)

An online single-window portal launched by the Kerala government to streamline industrial clearances, integrate departmental approvals, and provide time-bound licenses for entrepreneurs.
UPSC context
Relevant for GS-II (E-Governance) and GS-III (Ease of Doing Business); tests knowledge of state-level digital governance reforms.
Kerala State Industrial Development Corporation (KSIDC)
The premier agency responsible for industrial promotion, investment facilitation, and infrastructure development in Kerala, acting as the nodal body for single-window clearances.
UPSC context
Relevant for GS-III (Industrial Growth); tests understanding of institutional frameworks supporting state-level economic development.
Professional Tax
A state-levied direct tax on income earned by individuals through profession, trade, or employment, constitutionally capped at ₹2,500 per annum under Article 276.
UPSC context
Relevant for GS-II (Federalism) and GS-III (Fiscal Policy); tests knowledge of Article 276 and state taxation powers.
Local Self-Government Institutions (LSGIs)
Rural (Panchayats) and urban (Municipalities) bodies empowered by the 73rd and 74th Constitutional Amendments to manage local administration and collect specific taxes.
UPSC context
Critical for GS-II (Polity/Decentralization); tests understanding of the three-tier governance system and local resource mobilization.
Ease of Doing Business (EoDB)
A metric reflecting the simplicity and efficiency of a region's regulatory environment for starting, operating, and growing businesses.
UPSC context
Relevant for GS-III (Economic Development); tests knowledge of regulatory reforms and investment climate indicators.
MSME Sector
Enterprises classified by investment and turnover thresholds; they are vital for employment and GDP, often benefiting from specific simplified compliance regimes.
UPSC context
High importance for GS-III (Economy/Industrial Growth); tests awareness of small industries' role and policy support mechanisms.
Prelims Trap
"Because Professional Tax is a tax on income, it is levied by the Union Government but collected by Local Bodies."
False. Under Article 276, Professional Tax is explicitly levied by the State Legislature, despite being a tax on income. It is capped at ₹2,500 per year.
Static Concepts Connected
What is the constitutional basis for levying Professional Tax in India?
- Article 276: Empowers state legislatures to levy taxes on professions, trades, and employments, acting as an exception to the Union's exclusive power to tax income.
- ₹2,500 Cap: The 60th Constitutional Amendment Act (1988) capped the maximum professional tax payable by an individual at ₹2,500 per annum (up from ₹250).
- Local Body Collection: States frequently delegate the collection of this tax to Panchayats or Municipalities to augment their independent financial resources.
How do Single Window Systems function in Government-to-Business (G2B) governance?
- Service Integration: Platforms like KSWIFT or the National Single Window System consolidate multiple departmental clearances into one interface, reducing procedural friction for enterprises.
- Compliance Burden Reduction: By eliminating the need for physical visits to government offices, these portals actively curb rent-seeking and lower the administrative cost of formalization.
Cross-Topic Patterns
MSME Formalization & E-Governance
Tools like KSWIFT complement national digital platforms (like the Udyam portal) in lowering regulatory compliance costs, actively driving informal MSMEs toward formalization.
Financial Autonomy of Local Bodies
Automating professional tax payments directly strengthens the fiscal health of local self-governments by plugging leakages in their own-source revenue collection.

Expect a Prelims question combining Article 276 (Professional Tax cap) with G2B e-governance systems in the context of MSME formalization.
Linked PYQs · 3
Linked PYQs · 3
- 2023MainsGS3
Faster economic growth requires increased share of the manufacturing sector in GDP, particularly of MSMEs. Comment on the present policies of the Government in this regard.
- 2023MainsGS2
e-governance, as a critical tool of governance, has ushered in effectiveness, transparency and accountability in governments. What inadequacies hamper the enhancement of these features ?
- 2018MainsGS2
E-governance is not only about utilization of the power of new technology, but also much about critical importance of the 'use value' of information. Explain.
