RBI Approval for Bank Stake Acquisitions and Regulatory Norms
Source:The Hindu ↗
Why It Matters
Demonstrates the RBI's regulatory role in overseeing investments, acquisitions, and cross-holdings within the Indian banking sector. Relevant to GS3 topics on the Indian economy, banking regulations, and the role of Small Finance Banks in financial inclusion.
Summary
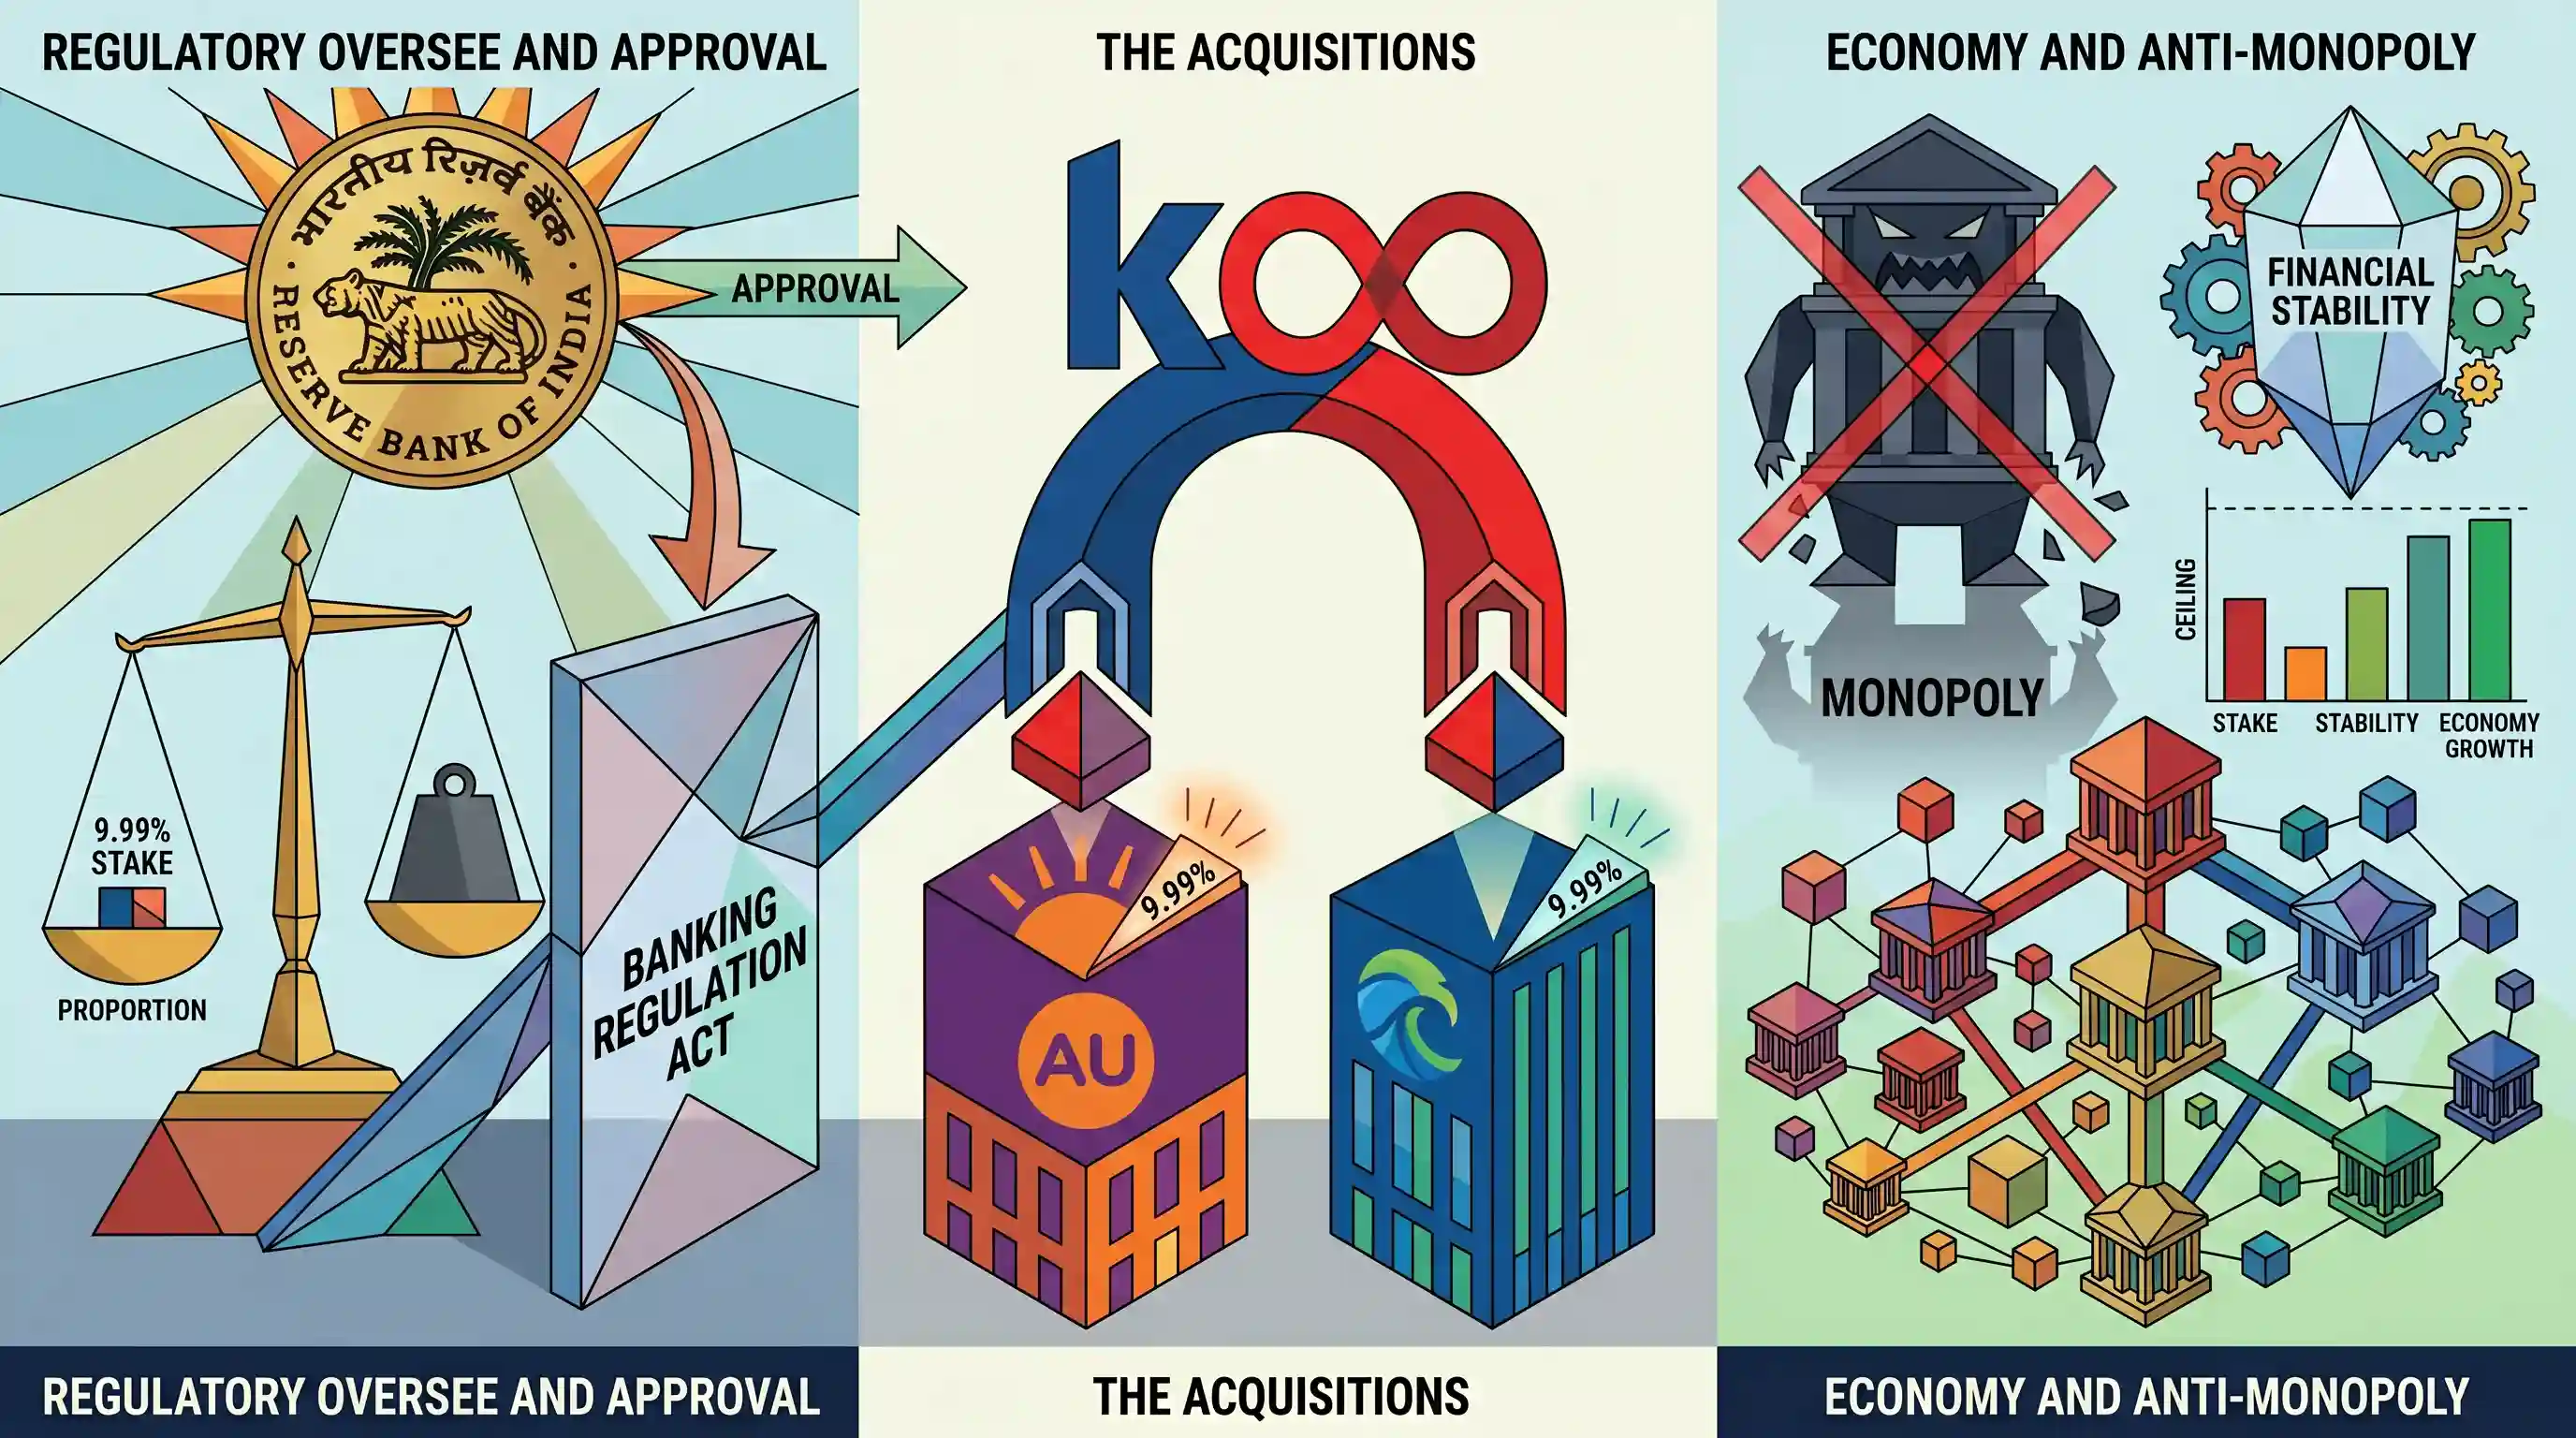
Kotak Mahindra Bank has received regulatory approval from the Reserve Bank of India (RBI) to acquire up to a 9.99% stake each in AU Small Finance Bank and Federal Bank. This acquisition is subject to RBI guidelines ensuring that the aggregate holding does not exceed 9.99% of paid-up share capital or voting rights. The RBI strictly monitors significant acquisitions in banking entities under the Banking Regulation Act to ensure financial stability and prevent monopolies.
Key Points
- The RBI has granted Kotak Mahindra Bank approval to acquire up to a 9.99% stake each in AU Small Finance Bank and Federal Bank.
- The approval ensures Kotak Mahindra Bank's shareholding does not exceed 9.99% of the paid-up share capital or voting rights in either of the target banks.
- Regulatory approvals for acquiring shares in banks are governed under the Banking Regulation Act, 1949, and RBI's Master Directions on Acquisition and Holding of Shares or Voting Rights.
- If Kotak Bank's shareholding falls below 5%, it will require fresh RBI approval to raise it back to 5% or above.
Important Terms
Banking Regulation Act, 1949

Enacted in 1949, this legislation provides the framework for supervising and regulating banking companies in India, empowering the RBI to control licensing, management, and mergers to ensure financial stability.
UPSC context
GS Paper 3: Indian Economy and issues relating to planning, mobilization of resources, growth, development, and employment. Relevant for banking sector reforms.
Reserve Bank of India (RBI)
India's central bank and regulatory body responsible for regulating the Indian banking system, issuing currency, and managing monetary policy to maintain price stability and economic growth.
UPSC context
GS Paper 3: Monetary Policy and Regulatory Framework. Tests understanding of RBI’s statutory powers over private and public banks.
Small Finance Bank (SFB)
A niche banking category in India providing basic financial services—like deposits and lending—to unserved and underserved sections, including small businesses, farmers, and the unorganized sector.
UPSC context
GS Paper 3: Financial Inclusion. Tests knowledge of specialized banking structures designed to broaden the reach of the financial system.
Paid-up Share Capital
The total amount of money a company has received from shareholders in exchange for shares of stock, serving as the denominator for calculating percentage ownership or voting rights.
UPSC context
GS Paper 3: Economy (Basics). Tests understanding of corporate finance terms used in regulatory thresholds and acquisitions.
Major Shareholding
Defined by the RBI as an aggregate holding of 5% or more of a bank's paid-up share capital or voting rights, requiring prior regulatory approval to ensure "fit and proper" ownership.
UPSC context
GS Paper 3: Banking Regulation. Significant for understanding ownership caps and the "9.99% rule" used to prevent monopolies in banking.
Prelims Trap
Prior RBI approval is mandatory for any individual or entity to acquire shares in a banking company.
RBI approval is not required for *any* share acquisition; it is only mandatory when acquiring 5% or more of paid-up capital or voting rights.
Static Concepts Connected
What are the key restrictions on shareholding in Indian private sector banks?
- 5% Threshold: Acquiring 5% or more of paid-up share capital or voting rights requires prior RBI approval under Section 12B of the Banking Regulation Act.
- Ownership Caps: Non-promoter shareholding is generally capped at 10% for natural persons and non-financial entities, and 15% for financial institutions, ensuring diversified ownership.
- Fit and Proper: RBI conducts continuous due diligence on major shareholders (5%+) to safeguard depositor interests and ensure management isn't compromised.
How do Small Finance Banks (SFBs) differ structurally from standard commercial banks?
- PSL Targets: SFBs must allocate 75% of their Adjusted Net Bank Credit to Priority Sector Lending, compared to the 40% mandate for standard commercial banks.
- Loan Size Limits: At least 50% of an SFB's loan portfolio must strictly comprise small ticket loans and advances up to Rs. 25 lakh.
- Credit Operations: Unlike Payments Banks, SFBs can undertake basic lending activities alongside accepting deposits, focusing heavily on unserved and underserved sections.
Cross-Topic Patterns
Cross-holding & SFB networks
Large banks acquire stakes in niche Small Finance Banks to indirectly capitalize on their specialized priority sector lending and rural financial inclusion networks without bearing direct operational costs.
Monopoly vs Financial Stability
Connects to RBI's broader corporate governance framework aiming to prevent concentration of power, cross-contamination, and systemic contagion risks across private sector financial entities.

Expect a multi-statement Prelims question testing the exact statutory thresholds (5% vs 10%) for bank ownership under the BR Act, 1949.
Linked PYQs · 4
Linked PYQs · 4
- 2017PrelimsGS1
What is the purpose of setting up of Small Finance Banks (SFBs) in India? 1. To supply credit to small business units 2. To supply credit to small and marginal farmers 3. To encourage young entrepreneurs to set up business particularly in rural areas. Select the correct answer using the code given below:
- 2024PrelimsGS1
With reference to the rule/rules imposed by the Reserve Bank of India while treating foreign banks, consider the following statements: 1. There is no minimum capital requirement for wholly owned banking subsidiaries in India. 2. For wholly owned banking subsidiaries in India, at least 50% of the board members should be Indian nationals. Which of the statements given above is/are correct?
- 2021PrelimsGS1
With reference to Urban Cooperative Banks' in India, consider the following statements : 1. They are supervised and regulated by local boards set up by the State Governments. 2. They can issue equity shares and preference shares. 3. They were brought under the purview of the Banking Regulation Act, 1949 through an Amendment in 1966. Which of the statements given above is/are correct?
- 2022MainsGS3
Is inclusive growth possible under market economy ? State the significance of financial inclusion in achieving economic growth in India.
