Kerala High Court Ruling on KIIFB Audit Mandate by CAG
Source:The Hindu ↗
Why It Matters
This ruling directly impacts the discourse on public financial accountability, the constitutional role of the CAG, and the legality of extra-budgetary borrowings by states, making it crucial for understanding Indian federalism and financial administration.
Summary
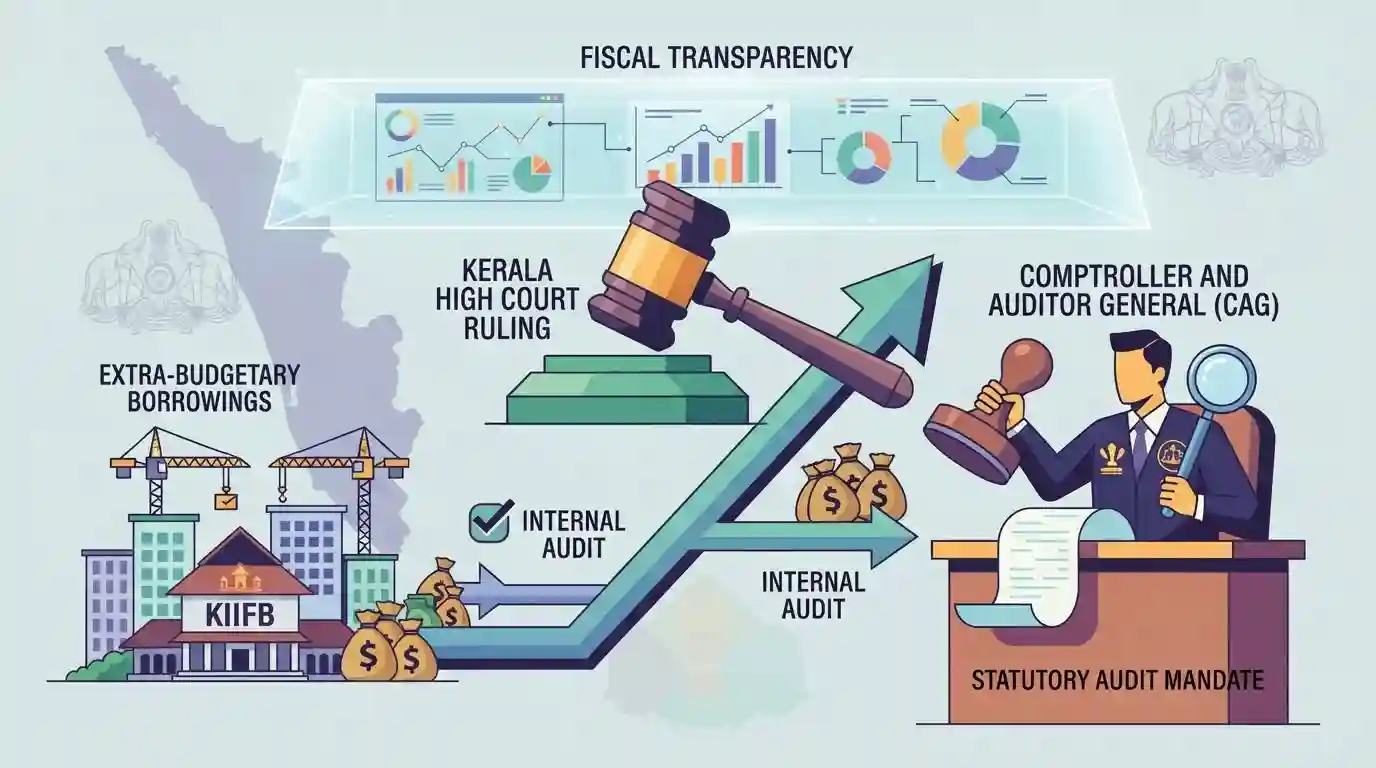
The Kerala High Court delivered a judgment ruling that the accounts of the Kerala Infrastructure Investment Fund Board (KIIFB) ought to have been audited by the Comptroller and Auditor General (CAG). The decision highlights key issues regarding fiscal transparency, statutory audit mandates, and the regulation of extra-budgetary borrowings by state governments.
Key Points
- The Kerala High Court held that the accounts of the Kerala Infrastructure Investment Fund Board (KIIFB) should have been subjected to audit by the Comptroller and Auditor General (CAG).
- The ruling addresses concerns regarding extra-budgetary borrowings and financial transparency in state-backed statutory bodies.
- It reinforces the expansive mandate of the CAG in ensuring public financial accountability and scrutinizing state fund deployments.
Important Terms
Comptroller and Auditor General (CAG)

An independent constitutional authority under Article 148 of the Indian Constitution responsible for auditing all receipts and expenditure of the Union and State Governments.
UPSC context
UPSC Prelims/Mains (GS Paper II): Tests understanding of constitutional bodies, financial accountability, and public expenditure auditing in India.
Kerala Infrastructure Investment Fund Board (KIIFB)
A statutory corporate body established to mobilize off-budget resources for infrastructure development in Kerala, utilizing state-guaranteed loans and bonds.
UPSC context
UPSC Mains (GS Paper II & III): Important for topics on fiscal federalism, off-budget borrowings, state finances, and financial transparency.
Off-Budget Borrowings
Financial obligations incurred by state government entities that are kept outside the formal state budget, impacting public debt limits and fiscal transparency.
UPSC context
UPSC Mains (GS Paper III - Indian Economy & Fiscal Policy): Tests knowledge of fiscal discipline, FRBM norms, and public debt management.
Prelims Trap
The CAG automatically has constitutional jurisdiction to audit every single public sector undertaking and statutory board created by a state legislature without exception.
Aspirants often assume CAG has an automatic right to audit all state-backed statutory bodies without statutory authorization or specific state legislative provisions, whereas Article 149 and the DPC Act govern its exact jurisdiction.
Static Concepts Connected
What are the constitutional provisions and statutory powers governing the Comptroller and Auditor General (CAG) of India?
- Constitutional Basis: Article 149 empowers Parliament to prescribe the duties and powers of the CAG in relation to the accounts of the Union and the States.
- Statutory Act: The CAG's duties are primarily detailed under the CAG's (Duties, Powers and Conditions of Service) Act, 1971.
- Audit Scope: CAG audits receipts and expenditure of the Consolidated Fund of India, each State, and Union Territories with a Legislative Assembly.
- Reporting Mechanism: Reports of the CAG relating to the accounts of a State are submitted to the Governor, who causes them to be laid before the State Legislature.
Cross-Topic Patterns
Fiscal Federalism and Off-Budget Borrowings
Extra-budgetary borrowings by states test the limits of fiscal federalism, FRBM Act compliance, and the constitutional oversight powers of the Comptroller and Auditor General.
Statutory Autonomy vs Constitutional Audit Mandate
Disputes between state-backed special purpose vehicles and federal audit bodies highlight tensions in cooperative federalism and statutory accountability.

CAG mandate under Article 149 and state off-budget borrowings likely to be tested via statement-based questions in Prelims.
Linked PYQs · 3
Linked PYQs · 3
- 2024MainsGS2
“The duty of the Comptroller and Auditor General is not merely to ensure the legality of expenditure but also its propriety.” Comment.
- 2018MainsGS2
“The Comptroller and Auditor General (CAG) has a very vital role to play.” Explain how this is reflected in the method and terms of his appointment as well as the range of powers he can exercise.
- 2016MainsGS2
Exercise of CAG's powers in relation to the accounts of the Union and the States is derived from Article 149 of the Indian Constitution. Discuss whether audit of the Government's policy implementation could amount to overstepping its own (CAG) jurisdiction.
