Monetary Policy Transmission and Retail Loan Rate Cuts
Source:The Hindu ↗
Why It Matters
Demonstrates a real-world example of monetary policy transmission, a key concept in macroeconomics and GS3 Economy. It illustrates how RBI policy rate changes (repo rate) directly influence commercial banks' lending rates for retail consumers.
Summary
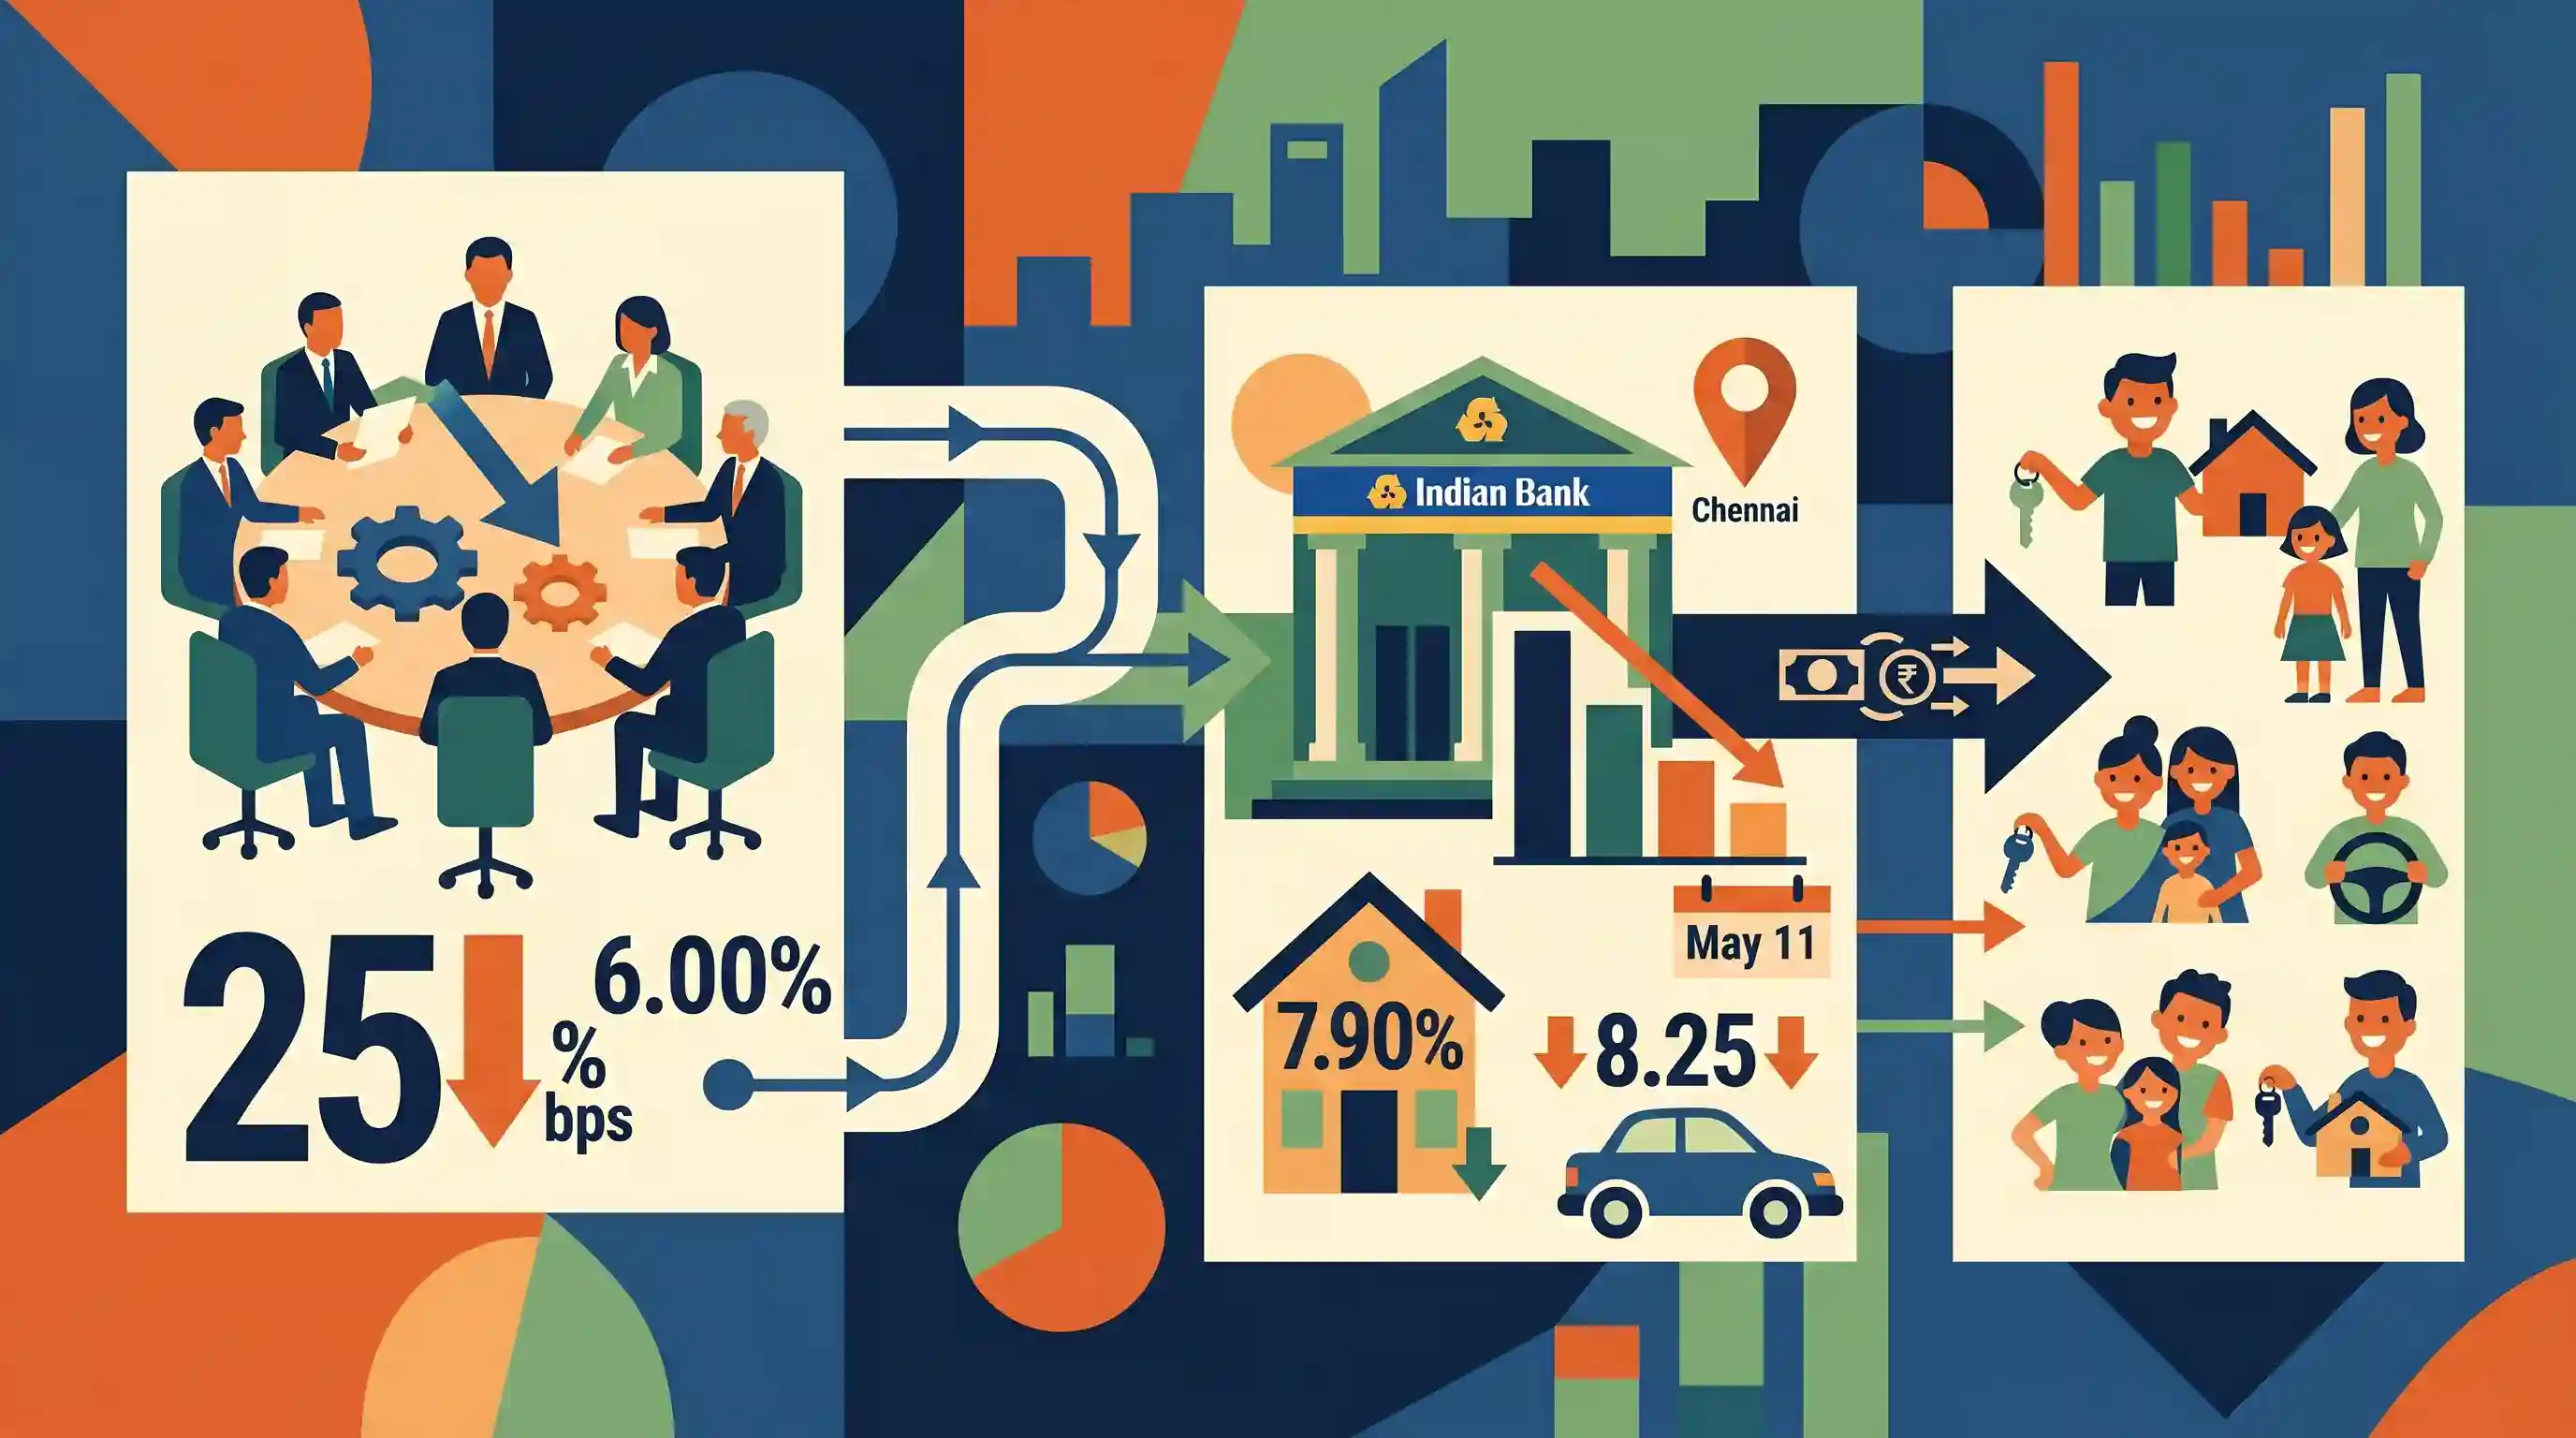
Following the Reserve Bank of India's Monetary Policy Committee reducing the benchmark short-term lending rate by 25 basis points to 6%, Indian Bank has announced a significant reduction in retail loan rates. The Chennai-based public sector lender slashed its home loan interest rate to 7.90% and vehicle loan interest rate to 8.25%, with the new rates taking effect on May 11. This move highlights effective monetary policy transmission, passing the benefits of the central bank's rate cuts directly to consumers.
Key Points
- Indian Bank has reduced its home loan interest rate by 30 basis points to 7.90% and vehicle loan interest rate by 45 basis points to 8.25%.
- This reduction follows the RBI Monetary Policy Committee's decision to cut the short-term lending rate (repo rate) by 25 basis points to 6%.
- The revised interest rates for retail loans by the Chennai-headquartered public sector lender will come into effect on May 11.
- This action exemplifies direct monetary policy transmission, as the bank passes on the benefits of the repo rate cut to retail borrowers.
Important Terms
Reserve Bank of India (RBI)

India's central bank and regulatory body, established in 1935. It manages monetary policy, regulates the banking system, and maintains financial stability to support economic growth.
UPSC context
GS-III: Indian Economy. Key for understanding central banking functions, regulatory powers, and inflation management.
Monetary Policy Committee (MPC)
A statutory six-member committee, chaired by the RBI Governor, that determines the benchmark repo rate to achieve the medium-term inflation target (4% +/- 2%) while considering growth objectives.
UPSC context
GS-III: Monetary Policy. Important for the transparent, rule-based framework for setting interest rates in India.
Monetary Policy Transmission
The process through which changes in the RBI's policy rates are passed through the financial system to influence lending rates for consumers and businesses.
UPSC context
GS-III: Economy. Tests critical analysis of how central bank actions impact the real economy and bank lending.
Repo Rate
The benchmark interest rate at which the RBI lends money to commercial banks against government securities. It is the primary tool for managing liquidity and inflation.
UPSC context
GS-III: Monetary Policy Tools. A core concept in Prelims/Mains regarding liquidity management and economic signaling.
Public Sector Banks (PSBs)
Banks where the Government of India holds a majority stake (51% or more). They are key instruments for financial inclusion and implementing national welfare schemes.
UPSC context
GS-III: Banking Sector. Tests knowledge of the government's role in credit markets and the challenges like NPAs.
Basis Points (bps)
A standard unit of measure for interest rates and other percentages in finance. One basis point is equal to 1/100th of 1% (0.01%).
UPSC context
Economic Literacy. Essential for interpreting financial data and central bank policy announcements in the news.
Prelims Trap
A repo rate cut by the RBI mandates an exactly proportional and automatic reduction in all retail loan interest rates.
While retail loans are linked to External Benchmarks (like Repo) since 2019, banks control the credit risk premium (spread), meaning final rate cuts vary.
Static Concepts Connected
What is the External Benchmark Lending Rate (EBLR) regime?
- Mandatory linking: Since 2019, the RBI mandated linking all new floating-rate personal, retail, and MSME loans to an external benchmark to ensure faster policy transmission.
- Benchmark options: Banks can choose the RBI repo rate, or the Government of India's 3-month or 6-month Treasury Bill yields published by FBIL.
- Risk premium (Spread): While the benchmark fluctuates automatically, the bank's 'spread' or credit risk premium remains fixed for the borrower unless their credit assessment changes.
What are the main hurdles to efficient Monetary Policy Transmission in India?
- Deposit rigidity: Indian banks rely heavily on long-term fixed-rate retail deposits. They cannot immediately lower these deposit payout rates when repo rates fall.
- Small savings competition: Government small savings schemes offer attractive, administratively-set interest rates, preventing banks from drastically lowering their own deposit rates to match repo cuts.
- NPA burden: Historically, high non-performing assets (NPAs) have forced banks to maintain higher Net Interest Margins to provision for bad loans, slowing rate pass-throughs.
Cross-Topic Patterns
Monetary transmission vs. Small Savings
The RBI's rate cuts often face friction from high returns on government small savings schemes (like PPF), which force banks to keep deposit rates high to remain competitive, ultimately squeezing lending margins.
EBLR vs. MCLR transition dynamics
The shift from internal benchmarks (MCLR/Base Rate) to external ones (EBLR) reflects a regulatory push to eliminate bank opacity in calculating the marginal cost of funds for retail borrowers.

Expect a 2026 Prelims statement linking EBLR mechanics to monetary transmission efficiency, focusing on what components banks can still vary.
Linked PYQs · 3
Linked PYQs · 3
- 2022PrelimsGS1
In India, which one of the following is responsible for maintaining price stability by controlling inflation?
- 2024MainsGS3
What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.
- 2024PrelimsGS1
With reference to the Indian economy, "Collateral Borrowing and Lending Obligations" are the instruments of:
