India Notifies Amended Tax Treaty With Mauritius Implementing PPT
Source:ddindia ↗
Why It Matters
Crucial for understanding international trade, foreign direct investment (FDI) inflows into India, and measures taken by the government to plug tax loopholes and curb treaty shopping.
Summary
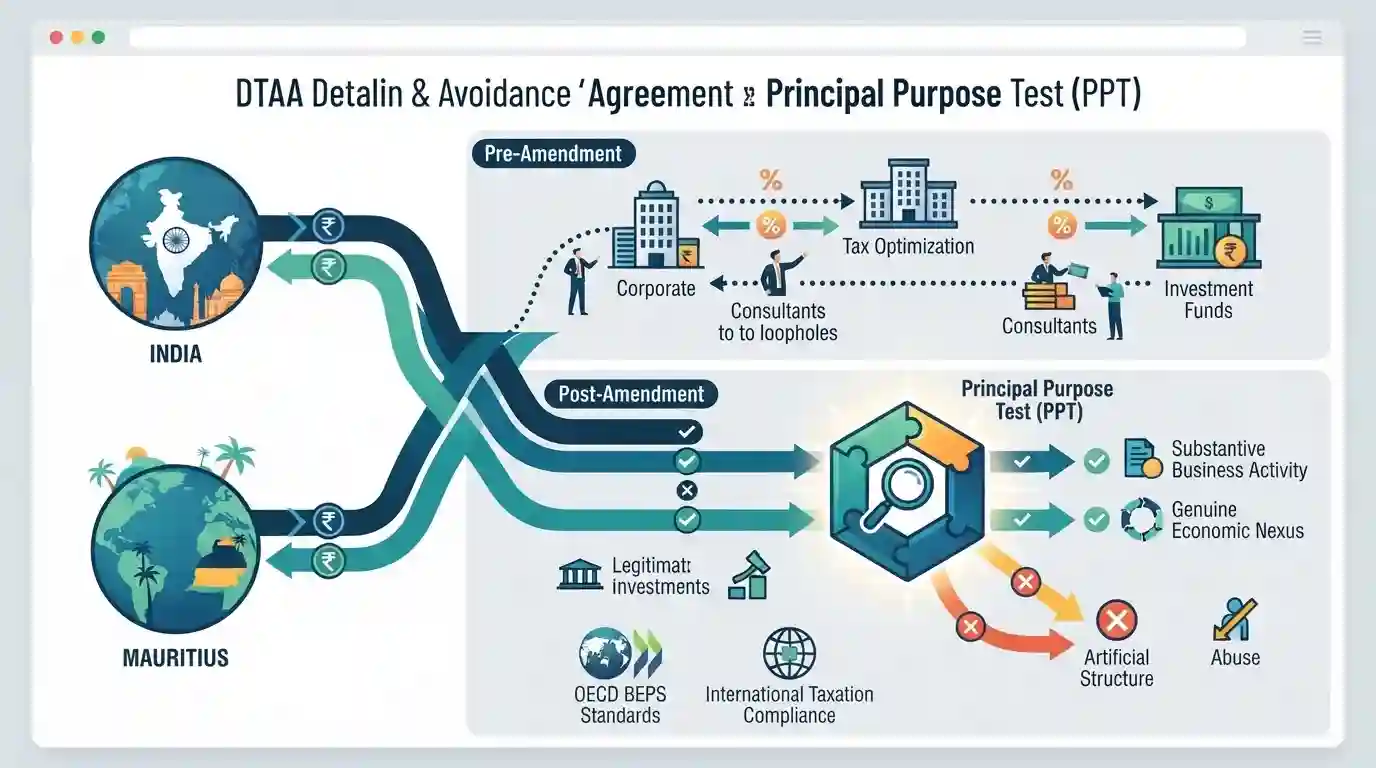
India notified the amended Double Taxation Avoidance Agreement (DTAA) with Mauritius, introducing the Principal Purpose Test (PPT). The amendment aims to prevent tax treaty abuse by checking whether tax avoidance is a primary motivation behind business or investment structures, complying with OECD BEPS standards.
Key Points
- India notified the amended India-Mauritius tax treaty incorporating the Principal Purpose Test (PPT).
- The Principal Purpose Test is an anti-abuse measure designed to ensure that tax treaty benefits are only granted if obtaining those benefits was not one of the principal purposes of any arrangement or transaction.
- This amendment aligns the bilateral tax treaty with global OECD/G20 Base Erosion and Profit Shifting (BEPS) minimum standards.
Important Terms
India-Mauritius Double Taxation Avoidance Agreement (DTAA)

A bilateral agreement between India and Mauritius designed to avoid double taxation of income and prevent fiscal evasion, recently amended to include anti-abuse measures like the Principal Purpose Test.
UPSC context
Important for MPSC Economy and International Relations (GS Paper), testing knowledge of bilateral tax treaties, foreign investments, and tax evasion frameworks.
Principal Purpose Test (PPT)
An anti-abuse rule incorporated into tax treaties allowing tax authorities to deny treaty benefits if obtaining them was one of the principal purposes of any arrangement or transaction.
UPSC context
Crucial for MPSC Economy and Taxation policy topics, assessing understanding of global anti-tax avoidance standards and the OECD BEPS framework.
Static Concepts Connected
What is the Double Taxation Avoidance Agreement (DTAA) and what are its key objectives?
- Definition: Bilateral treaty between two or more countries to avoid double taxation of income earned in intersecting jurisdictions.
- Objectives: Provides tax relief, stimulates foreign investment, and prevents tax evasion through mutual administrative assistance.
- Mechanism: Can operate through exemption method or credit method to eliminate overlapping tax liabilities.
Cross-Topic Patterns
DTAA Amendments Impacting FPI and FDI Flows
The India-Mauritius DTAA revision connects international taxation reform with Foreign Portfolio Investment (FPI) inflows, impacting Mauritius's historical role as the top FDI source for India.
OECD BEPS Standards and Multilateral Instruments
Incorporation of OECD BEPS standards into bilateral treaties showcases India's commitment to multilateral tax transparency frameworks like the Multilateral Instrument (MLI).

Expect a statement-based MPSC question on the India-Mauritius DTAA amendment, specifically testing the grandfathering clause for pre-2017 investments.
Linked PYQs · 2
Linked PYQs · 2
- 2026MPSC_PRELIMSGS1
Match the pairs. | Poverty Eradication Programs in India | Year of launch | |---|---| | (a) Integrated Rural Development Programme (IRDP) | (i) 2001 | | (b) Rural Landless Employment Guarantee Programme (RLEGP) | (ii) 1989 | | (c) Jawahar Rojgar Yojana | (iii) 1983 | | (d) Sampoorna Grameen Rojgar Yojana | (iv) 1978 | Code: (a) (b) (c) (d)
- 2023MPSC_PRELIMSGS1
What is meant by Gender Budget ?
