Income tax return filing deadline extension for assessment year
Source:Indian Express ↗
Why It Matters
Timely filing of Income Tax Returns is critical for the government's revenue mobilization and fiscal planning. Policy adjustments such as deadline extensions reflect ongoing administrative efforts to balance robust tax compliance with taxpayer convenience and systemic capabilities.
Summary
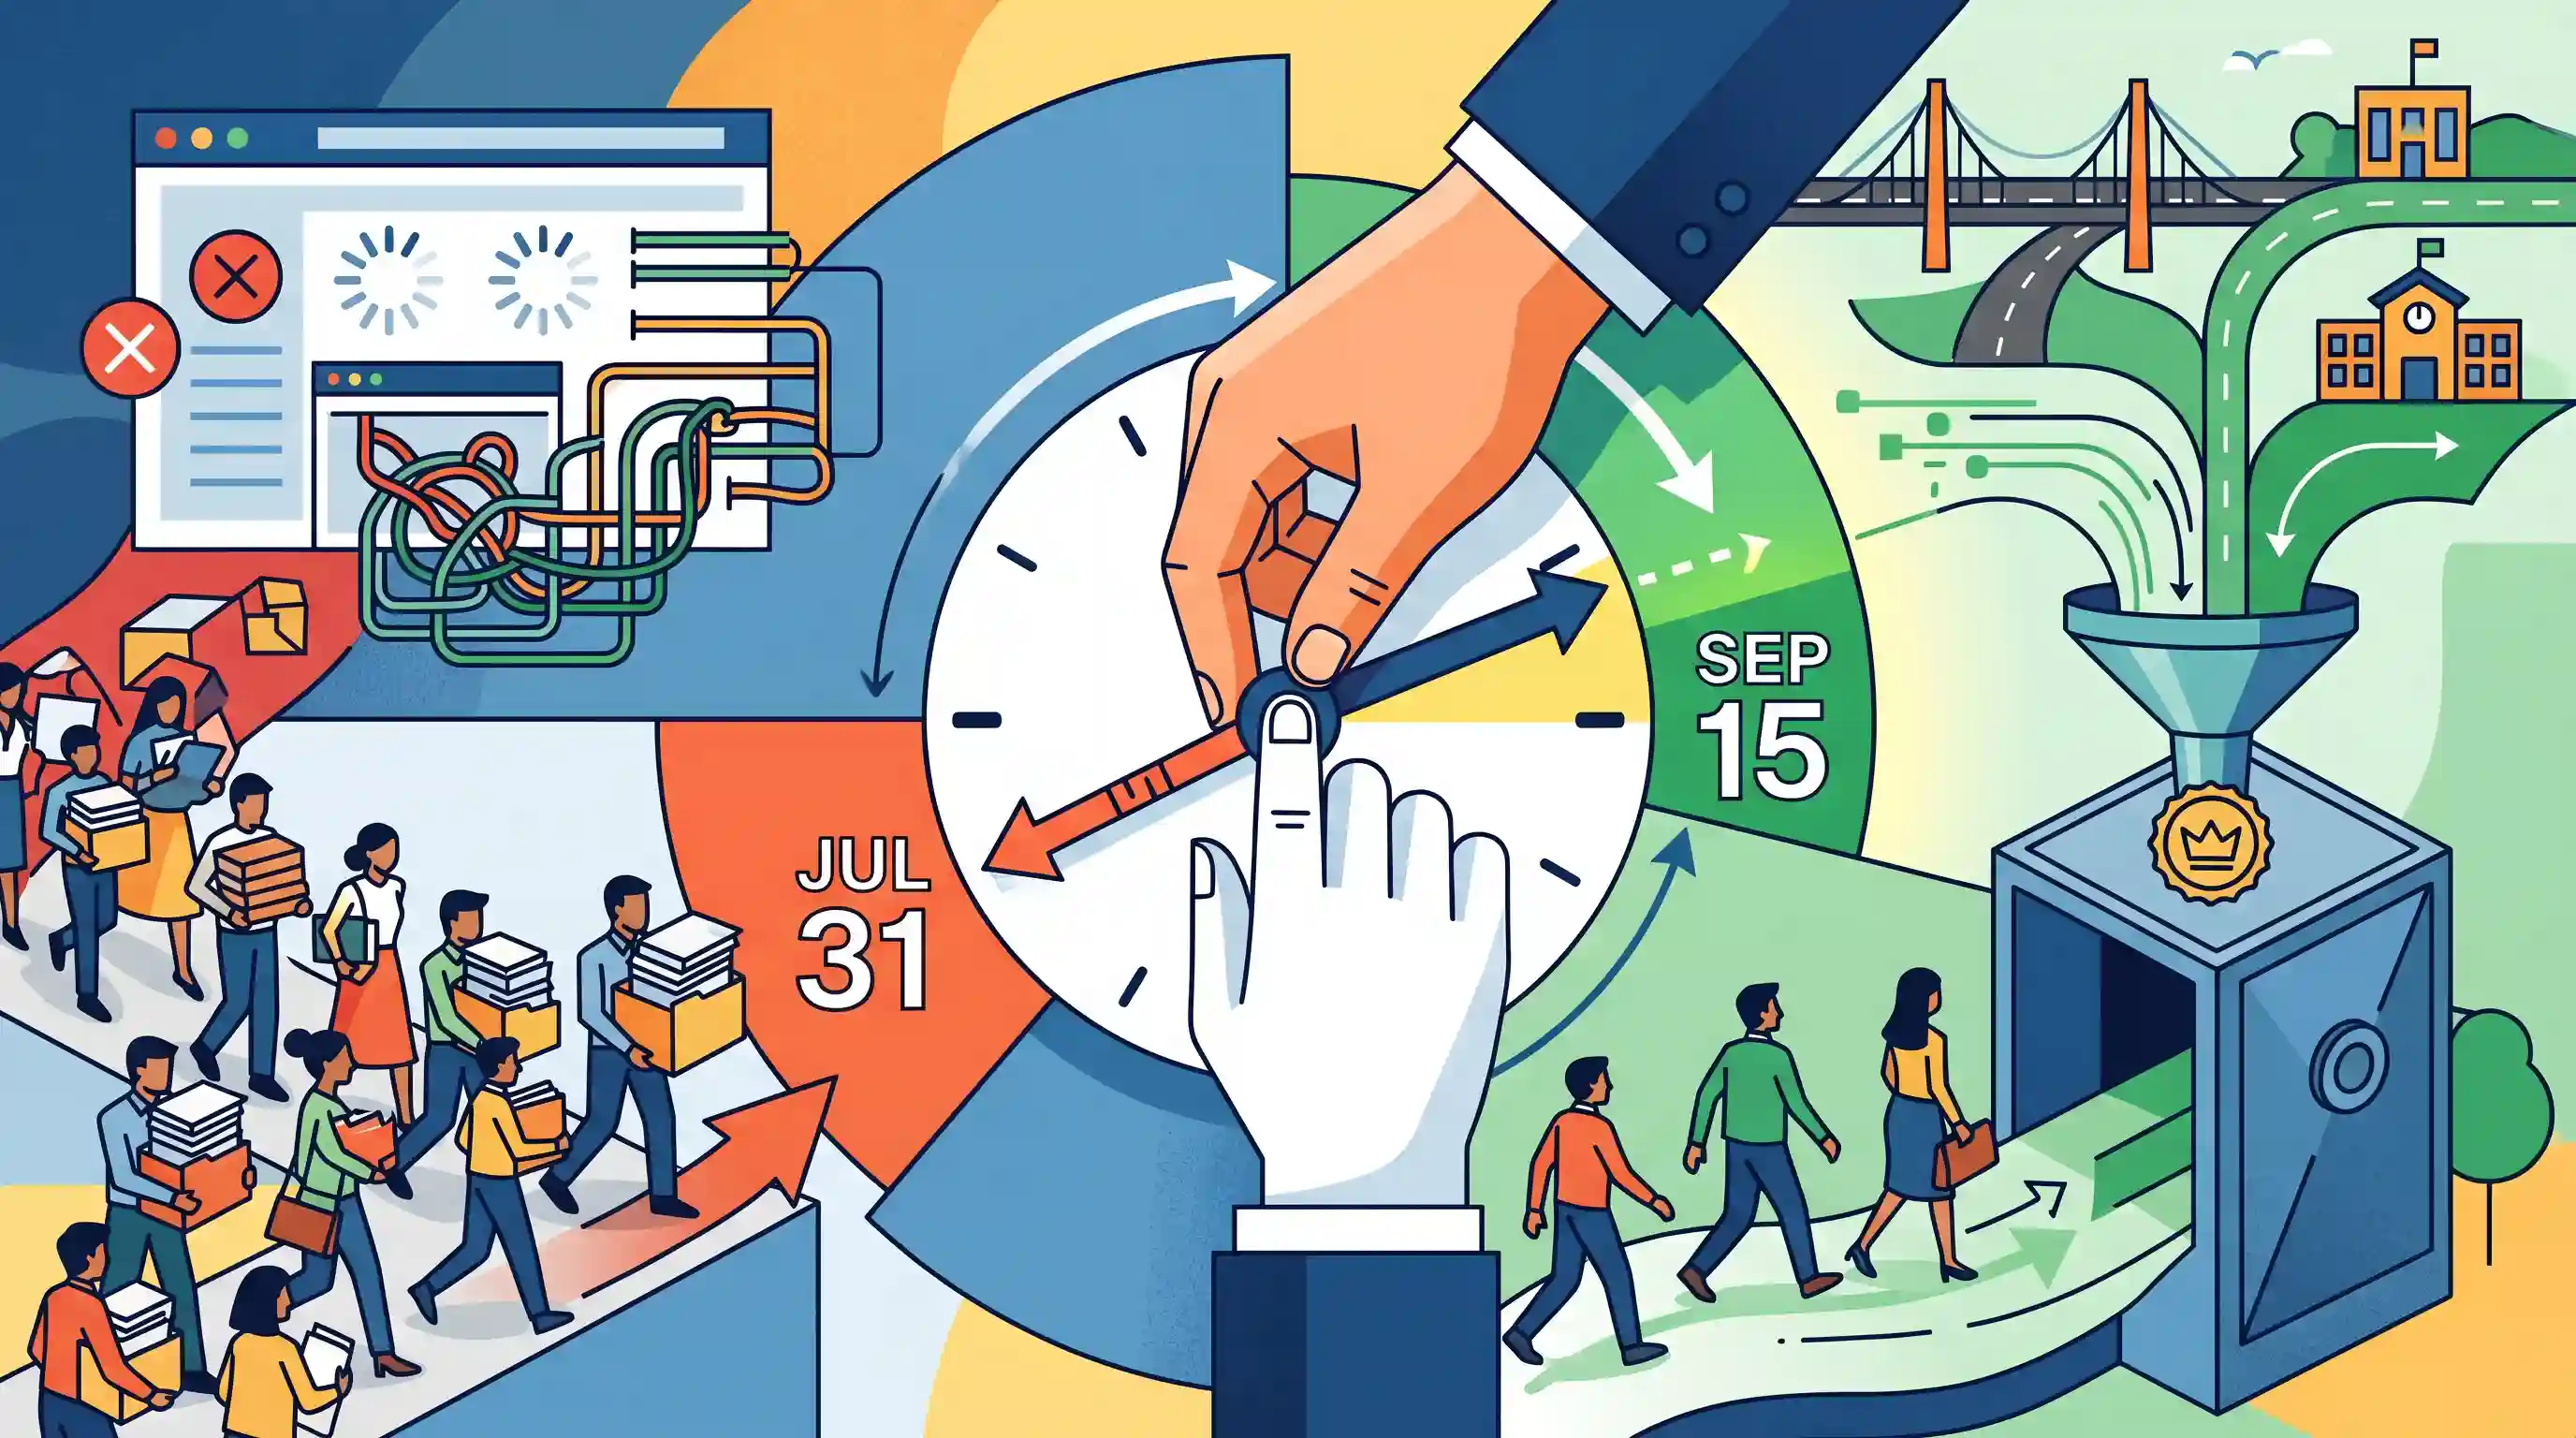
The Income Tax Department has extended the deadline for filing Income Tax Returns (ITR) for the Assessment Year 2026-27 (AY26) for individuals. The due date, which is typically July 31, has been pushed to September 15. Such extensions are usually granted to facilitate smoother tax compliance and address administrative or portal-related challenges faced by taxpayers.
Key Points
- The Income Tax Department has extended the due date for individuals to file their Income Tax Returns (ITR) for Assessment Year 2026-27 (AY26).
- The new deadline has been shifted from the original date of July 31 to September 15.
- This extension typically applies to individuals and entities whose accounts do not require a tax audit.
- Deadlines are often extended to ease the compliance burden on taxpayers, allow more time for reconciling financial data, or address technical glitches on the e-filing portal.
Important Terms
Central Board of Direct Taxes (CBDT)

The apex statutory body responsible for administering direct tax laws in India. It functions under the Department of Revenue within the Ministry of Finance and provides inputs for direct tax policy.
UPSC context
GS Paper III: Indian Economy (Taxation). Tests knowledge of statutory bodies and administrative machinery for resource mobilization.
Income Tax Act, 1961
The comprehensive legal framework governing the levy, collection, and administration of income tax in India. It outlines various heads of income, exemptions, deductions, and penalties for non-compliance.
UPSC context
GS Paper III: Government Budgeting. It is the foundational statute for direct taxation and fiscal policy in India.
Assessment Year (AY)
The 12-month period (April 1 to March 31) immediately following a Financial Year, during which the income earned in that previous year is reported, evaluated, and taxed by the authorities.
UPSC context
GS Paper III: Indian Economy. Essential for understanding tax compliance timelines and the distinction between earning and reporting periods.
Direct Tax
A tax paid directly by an individual or entity to the government on income or wealth. Unlike indirect taxes, the burden of a direct tax cannot be shifted to another person.
UPSC context
GS Paper III: Resource Mobilization. Tests conceptual clarity on progressive taxation and its role in reducing economic inequality.
Resource Mobilization
The process of gathering and managing financial, human, and natural resources to achieve developmental goals. In taxation, it refers to the government's ability to generate revenue to fund public expenditure.
UPSC context
GS Paper III: Indian Economy and issues relating to planning, mobilization of resources, growth, development, and employment.
Income Tax Department (ITD)
A government agency under the Department of Revenue, Ministry of Finance, responsible for enforcing direct tax laws and collecting revenue. It is headed by the Central Board of Direct Taxes (CBDT).
UPSC context
GS Paper III: Tax Administration. Relevant for topics on e-governance in taxation and administrative reforms.
Prelims Trap
"The extended September deadline applies universally to all individuals and corporate entities for the assessment year."
The extension specifically applies to individuals and entities whose accounts do not require a tax audit. Blanket statements claiming the extension applies universally to "all entities" are incorrect.
Static Concepts Connected
What is the statutory basis and mandate of the CBDT?
- Statutory Origin: It is a statutory body constituted under the Central Board of Revenue Act, 1963.
- Core Function: It formulates policies and administers direct tax laws (Income Tax, etc.) under the Department of Revenue, Ministry of Finance.
- Autonomy: Unlike GST, which relies on the GST Council (Constitutional), direct taxes are independently managed by the CBDT.
What are the macroeconomic implications of the Tax-to-GDP ratio?
- Definition: It measures the government's efficiency in tax collection relative to the overall size of the economy.
- Fiscal Impact: A consistently low ratio constrains government capital expenditure, reduces social sector spending, and increases reliance on fiscal borrowing.
- Progressivity: A higher direct-tax component within this ratio indicates a more progressive, equitable tax regime aimed at income redistribution.
Cross-Topic Patterns
E-Governance & Tax Compliance
Technical glitches in public portals (like IT e-filing or MCA21) frequently delay compliance, highlighting the gap between Digital India ambitions and state IT infrastructure capabilities.
Tax Audits & Cashless Economy
The differential tax audit threshold (₹1Cr normal vs ₹10Cr for digital transactions) demonstrates how direct tax policy is actively used to incentivize the transition to a cashless, formalized economy.

Expect a multi-statement Prelims question comparing the statutory mandates of CBDT vs CBIC, alongside recent trends in Tax-to-GDP ratio.
Linked PYQs · 2
Linked PYQs · 2
- 2025PrelimsGS1
With reference to the Government of India, consider the following information: Organization Some of its functions It works under I. Directorate of Enforcement Enforcement of the Fugitive Economic Offenders Act, 2018 Internal Security Division-I, Ministry of Home Affairs II. Directorate of Revenue Intelligence Enforces the Provisions of the Customs Act, 1962 Department of Revenue, Ministry of Finance III. Directorate General of Systems and Data Management Carrying out big data analytics to assist tax officers for better policy and nabbing tax evaders Department of Revenue, Ministry of Finance In how many of the above rows is the information correctly matched?
- 2023PrelimsGS1
Consider the following statements: Statement-I: Interest income from the deposits in Infrastructure Investment Trusts (InvITs) distributed to their investors is exempted from tax, but the dividend is taxable. Statement-II: InvITs are recognized as borrowers under the 'Securitization and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002'. Which one of the following is correct in respect of the above statements?
