Implementation of New Income Tax Act 2025 Simplifies Tax Structure
Source:Indian Express ↗
Why It Matters
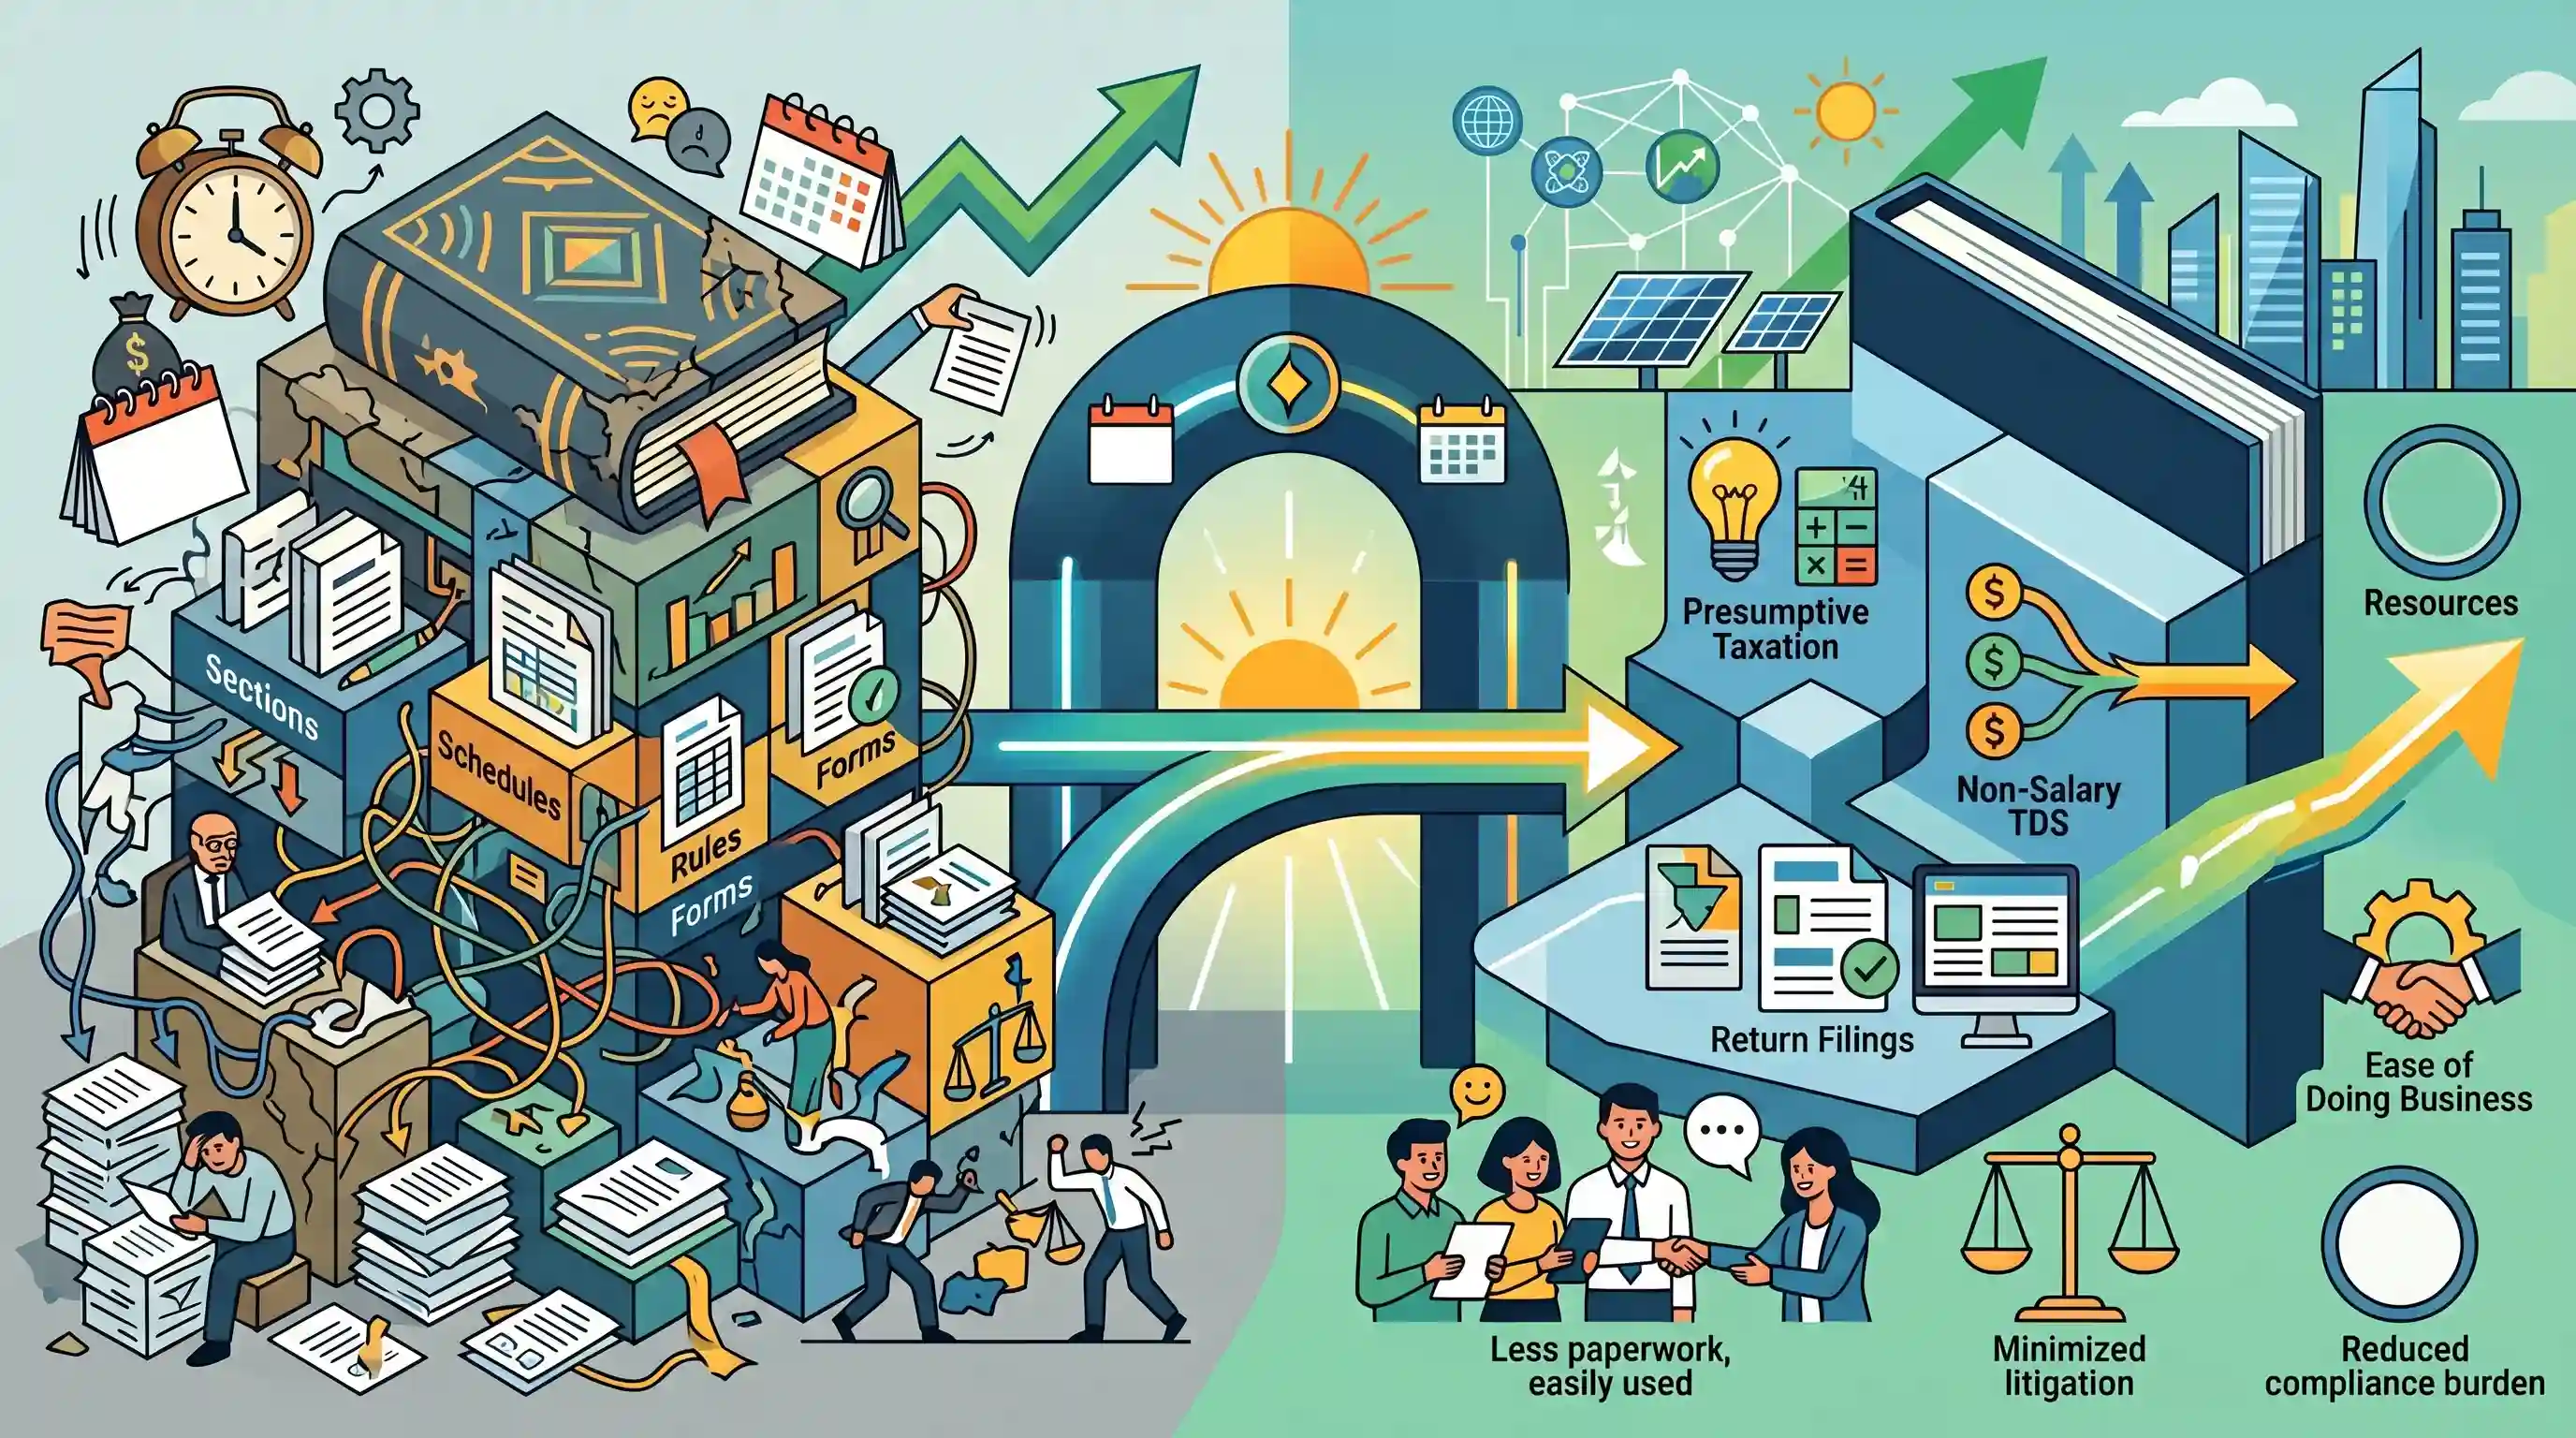
The enactment of the Income-tax Act, 2025 represents the most significant structural reform to India's direct tax system in over sixty years. It aligns with the government's broader economic agenda to simplify compliance, expand the tax base, and improve the ease of doing business, making it highly relevant for GS3 questions on fiscal policy, resource mobilization, and economic reforms.
Summary
The article highlights the upcoming transition to the new Income-tax Act, 2025, which replaces the six-decade-old Income-tax Act, 1961, effective April 1, 2026 (Assessment Year 2026-27). This major direct tax reform aims to simplify the tax code by reducing the number of sections from 298 to 174 and consolidating schedules, rules, and forms. Key structural changes include grouping presumptive taxation (under Section 58), consolidating non-salary TDS provisions (Section 393), and unifying all types of return filings (Section 263). The overhaul is designed to reduce compliance burdens, minimize litigation, and promote ease of doing business, while existing filings for AY 2025-26 will continue under the old regime.
Key Points
- The Income-tax Act, 2025 will replace the 1961 Act starting April 1, 2026 (applicable for the financial year beginning April 1, 2025, Assessment Year 2026-27).
- The new Act drastically reduces complexity, cutting sections from 298 to 174, schedules from 14 to 3, and merging multiple rules and forms.
- Presumptive taxation provisions (formerly Sections 44AD, 44ADA, 44AE) are consolidated into a single Section 58.
- TDS provisions for non-salary payments are merged into Section 393, simplifying deduction rules.
- Return filings (original, belated, revised, and updated) are consolidated under Section 263, while Forms 15G/15H merge into Form 121, and tax audit reports shift to Form 26.
- For the upcoming Assessment Year 2025-26, filings will still follow the old 1961 Act framework.
Important Terms
Income-tax Act, 2025

A major legislative overhaul replacing the 1961 Act from April 1, 2026. It aims to simplify direct tax codes, reduce sections, and modernize administration through digitization and unified return filings.
UPSC context
GS Paper III (Economy). Tests knowledge of direct tax reforms, mobilization of resources, and administrative simplification for ease of doing business.
Income-tax Act, 1961
The primary legislation governing direct taxes in India for over six decades. It is being superseded by the 2025 Act to eliminate archaic provisions and reduce massive legal clutter.
UPSC context
GS Paper III. Historically significant for understanding the evolution of India's fiscal policy and the drivers behind current structural tax reforms.
Tax Year
A unified 12-month period (April 1 to March 31) introduced in the 2025 Act. It replaces the distinct 'Financial Year' and 'Assessment Year' concepts to align with international tax standards.
UPSC context
GS Paper III. Important for understanding procedural reforms in taxation and the reduction of compliance complexity for taxpayers.
Presumptive Taxation
A simplified tax scheme allowing small businesses and professionals to declare income as a fixed percentage of turnover, exempting them from maintaining detailed books of accounts or audits.
UPSC context
GS Paper III. Tests understanding of inclusive tax policies designed to formalize the economy and reduce burdens on the MSME sector.
Tax Deducted at Source (TDS)
A mechanism where the person making specified payments (like salary, rent, or commission) withholds tax at the source and remits it directly to the Central Government on the recipient's behalf.
UPSC context
GS Paper III. Key to understanding revenue collection, curbing tax evasion, and the administrative role of the payer in the tax ecosystem.
Central Board of Direct Taxes (CBDT)
The statutory authority under the Ministry of Finance responsible for administering direct tax laws in India and providing inputs for policy formulation related to direct taxes.
UPSC context
GS Paper II (Statutory Bodies) & Paper III (Economy). Tests knowledge of the institutional framework governing India's revenue administration.
Prelims Trap
The Income-tax Act, 2025 replaces the 1961 Act for all income tax return filings in Assessment Year 2025-26.
AY 2025-26 filings will still use the old 1961 Act framework. The new 2025 Act takes effect for income earned from April 1, 2025 (AY 2026-27).
Static Concepts Connected
What is the Presumptive Taxation Scheme under Indian Income Tax?
- Core mechanism: Allows taxpayers to declare income at a prescribed statutory rate, exempting them from maintaining detailed books of account.
- Target demographic: Designed to ease compliance for small businesses, independent professionals, and specific transporters.
- Primary benefit: Reduces audit burdens, minimizes litigation, and significantly lowers the cost of compliance for SMEs.
How do Financial Year (FY) and Assessment Year (AY) differ in taxation?
- Financial Year: The 12-month period (April 1 to March 31) during which a taxpayer actually earns the income.
- Assessment Year: The 12-month period immediately following the FY, during which the earned income is evaluated, reported, and taxed.
Cross-Topic Patterns
Direct vs Indirect Tax Consolidation
While the 2017 GST regime unified indirect taxes to integrate markets, the IT Act 2025 mirrors this reform by consolidating direct tax compliance, drastically reducing sections, and streamlining TDS rules.
MSME Formalization and Presumptive Tax
Streamlining presumptive taxation under a single section aligns with broader MSME formalization goals, connecting direct tax simplicity to Udyam registration, GST compliance, and better formal credit access.

Expect a 2026 Prelims multi-statement question contrasting the 1961 Act vs 2025 Act, specifically on presumptive taxation & simplified TDS.
Linked PYQs · 2
Linked PYQs · 2
- 2019MainsGS3
Enumerate the indirect taxes which have been subsumed in the Goods and Services Tax (GST) in India. Also, comment on the revenue implications of the GST introduced in India since July 2017.
- 2025PrelimsGS1
Suppose the revenue expenditure is ₹ 80,000 crores and the revenue receipts of the Government are ₹60,000 crores. The Government budget also shows borrowings of ₹ 10,000 crores and interest payments of ₹ 6,000 crores. Which of the following statements are correct? I. Revenue deficit is ₹ 20,000 crores. II. Fiscal deficit is ₹ 10,000 crores. III. Primary deficit is ₹ 4,000 crores. Select the correct answer using the code given below.
