GST rate rationalization proposals and indirect taxation reforms
Source:The Hindu ↗
Why It Matters
GST rate rationalisation is a vital ongoing economic reform in India aimed at simplifying the tax structure, preventing tax evasion, and minimizing the compliance burden on taxpayers. It directly impacts the Union-State financial relations, revenue neutrality, and the overall macroeconomic environment, making it a high-yield topic for both UPSC Prelims and GS3 Mains.
Summary
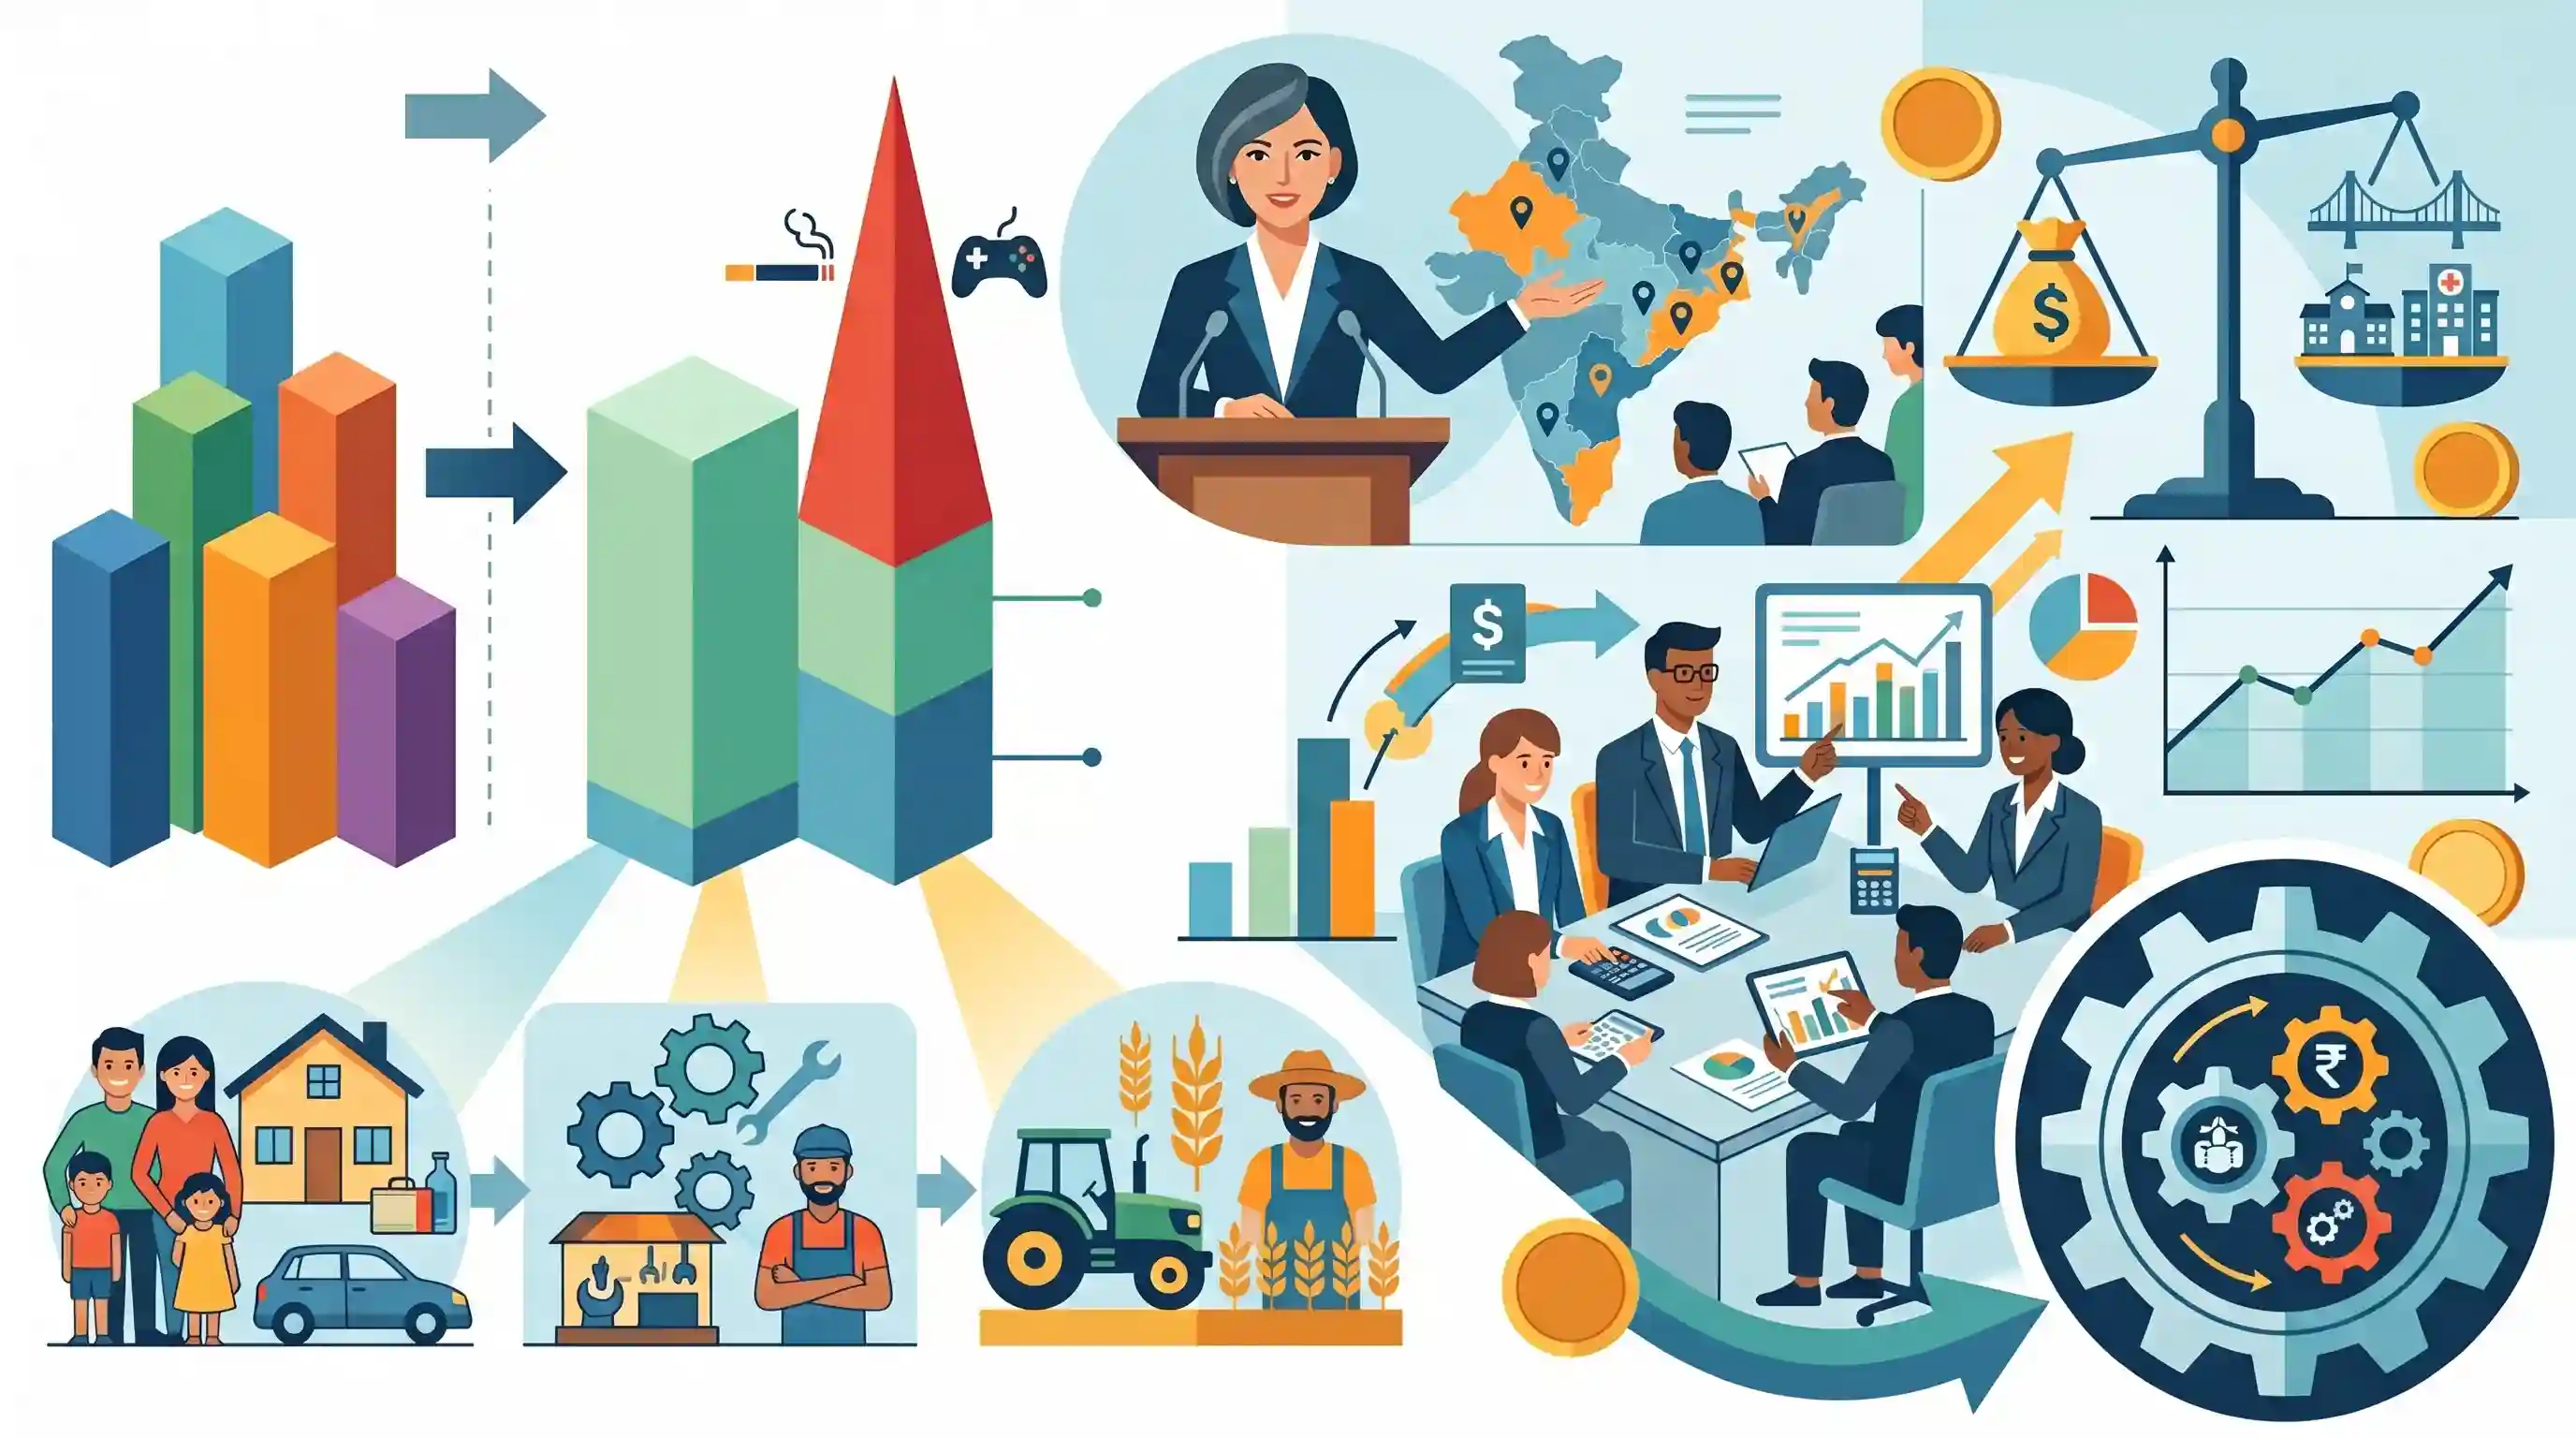
The Union government is advancing a significant proposal to restructure the Goods and Services Tax (GST) rates, shifting from the existing four-slab system to a two-tier structure of 5% and 18%. Finance Minister Nirmala Sitharaman will present this plan at the Group of Ministers (GoM) meeting on GST rate rationalisation. The proposal includes a 40% tax rate on specific demerit goods like tobacco and online gaming. This strategic reform intends to simplify indirect taxation and ease the tax burden on the middle class, MSMEs, and the farm sector, with states engaged in evaluating its revenue impact.
Key Points
- Union Finance Minister Nirmala Sitharaman is scheduled to address the first Group of Ministers (GoM) meeting on GST rate rationalisation to present the Centre's proposal.
- The Centre proposes restructuring the current four-slab GST system (5%, 12%, 18%, 28%) into a simplified 2-tier structure of 5% and 18%.
- A special higher rate of 40% is proposed for specific 'demerit' goods such as pan masala, tobacco products, and online gaming.
- The proposed tax rate rejig aims to reduce the financial burden on the middle class, Micro, Small and Medium Enterprises (MSMEs), and the agricultural sector.
- State representatives in the GoM have shown preliminary openness to the changes, pending detailed discussions on potential revenue implications.
Important Terms
Goods and Services Tax (GST)

A multi-stage, destination-based indirect tax levied on the supply of goods and services, replacing various central and state taxes to create a unified national market.
UPSC context
GS Paper-3: Indian Economy; fundamental for understanding indirect tax reforms, fiscal formalization, and the 'One Nation, One Tax' concept.
GST Council
A constitutional body established under Article 279A, chaired by the Union Finance Minister, that makes recommendations on GST rates, exemptions, and administrative rules via cooperative federalism.
UPSC context
GS Paper-2 & 3: Federalism/Economy; tests the institutional framework of fiscal federalism and the 101st Constitutional Amendment Act.
Group of Ministers (GoM)
A sub-committee of state finance ministers tasked by the GST Council to examine complex issues—like tax slabs—and propose technical solutions for final council approval.
UPSC context
GS Paper-3: Economy; represents the deliberative and delegatory mechanisms used to resolve Centre-State technical disagreements in tax policy.
Rate Rationalisation
The systematic review and merging of tax slabs to simplify the GST structure, reduce classification disputes, and correct inverted duty structures for better compliance.
UPSC context
GS Paper-3: Economy; critical for discussing ease of doing business, inflation management, and secondary-stage tax reforms in India.
Demerit Goods
Socially harmful or luxury items (e.g., tobacco, aerated drinks) taxed at the highest rates to discourage consumption and fund welfare; often includes a 'Sin Tax.'
UPSC context
GS Paper-3: Economy; tests understanding of tax as a social engineering tool and its role in revenue mobilization through 'sin taxes.'
MSMEs
Enterprises classified by investment and turnover limits under the MSMED Act; they are vital for employment, exports, and inclusive growth in India.
UPSC context
GS Paper-3: Economy; core topic for inclusive growth, industrial manufacturing (Make in India), and rural employment generation.
Prelims Trap
The Group of Ministers (GoM) has statutory powers under Article 279A to finalize and implement GST rate changes.
GoMs are merely recommendatory sub-committees. Only the GST Council has the constitutional mandate (Article 279A) to formally recommend rate changes to the Union and States.
Static Concepts Connected
What is the Inverted Duty Structure (IDS) under the GST regime?
- Core Anomaly: An anomaly where the tax rate on raw materials (inputs) is higher than the tax rate on the final finished product.
- Economic Impact: Results in unutilized Input Tax Credit (ITC) accumulation, blocking crucial working capital for domestic manufacturers and MSMEs.
- Resolution: Manufacturers must claim refunds to recover costs, increasing compliance burdens. Consolidating tax slabs naturally resolves this anomaly.
How are decisions made within the GST Council under Article 279A?
- Voting Weights: The Union government holds 1/3rd of the voting weight, while all States collectively hold 2/3rd of the total weight.
- Passage Threshold: Decisions require a 3/4th (75%) majority of the weighted votes of members present and voting to pass.
- Central Veto: Because of the 1/3rd weight, the Centre holds an effective veto over any GST Council decision.
Cross-Topic Patterns
Fiscal federalism + State revenue autonomy
Rate restructuring directly impacts state revenues, connecting to broader debates on states' fiscal autonomy, the cessation of GST compensation, and Finance Commission devolutions.
Demerit goods + Digital economy regulation
Classifying online gaming with tobacco at a proposed 40% rate links indirect taxation to recent regulatory crackdowns on digital platforms and foreign gaming apps.

Expect a 2026 Prelims multi-statement question pairing the mechanics of 'Inverted Duty Structure' with GST Council voting rules.
Linked PYQs · 5
Linked PYQs · 5
- 2019MainsGS3
Enumerate the indirect taxes which have been subsumed in the Goods and Services Tax (GST) in India. Also, comment on the revenue implications of the GST introduced in India since July 2017.
- 2013MainsGS3
Discuss the rationale for introducing Goods and Services Tax (GST) in India. Bring out critically the reasons for the delay in roll out for its regime.
- 2025MainsGS2
Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?
- 2018PrelimsGS1
Consider the following items : 1. Cereal grains hulled 2. Chicken eggs cooked 3. Fish processed and canned 4. Newspapers containing advertising material Which of the above items is/are exempted under GST (Goods and Services Tax)?
- 2017PrelimsGS1
What is/are the most likely advantages of implementing 'Goods and Services Tax (GST)'? 1. It will replace multiple taxes collected by multiple authorities and will thus create a single market in India. 2. It will drastically reduce the 'Current Account Deficit' of India and will enable it to increase its foreign exchange reserves. 3. It will enormously increase the growth and size of economy of India and will enable it to overtake China in the near future. Select the correct answer using the code given below:
