GST Council Tax Officer Arrest Powers and Rate Structure Reforms
Source:Indian Express ↗
Why It Matters
Important for understanding structural reforms in India's indirect taxation system, compliance burdens on businesses, and the role of the GST Council in fiscal federalism.
Summary
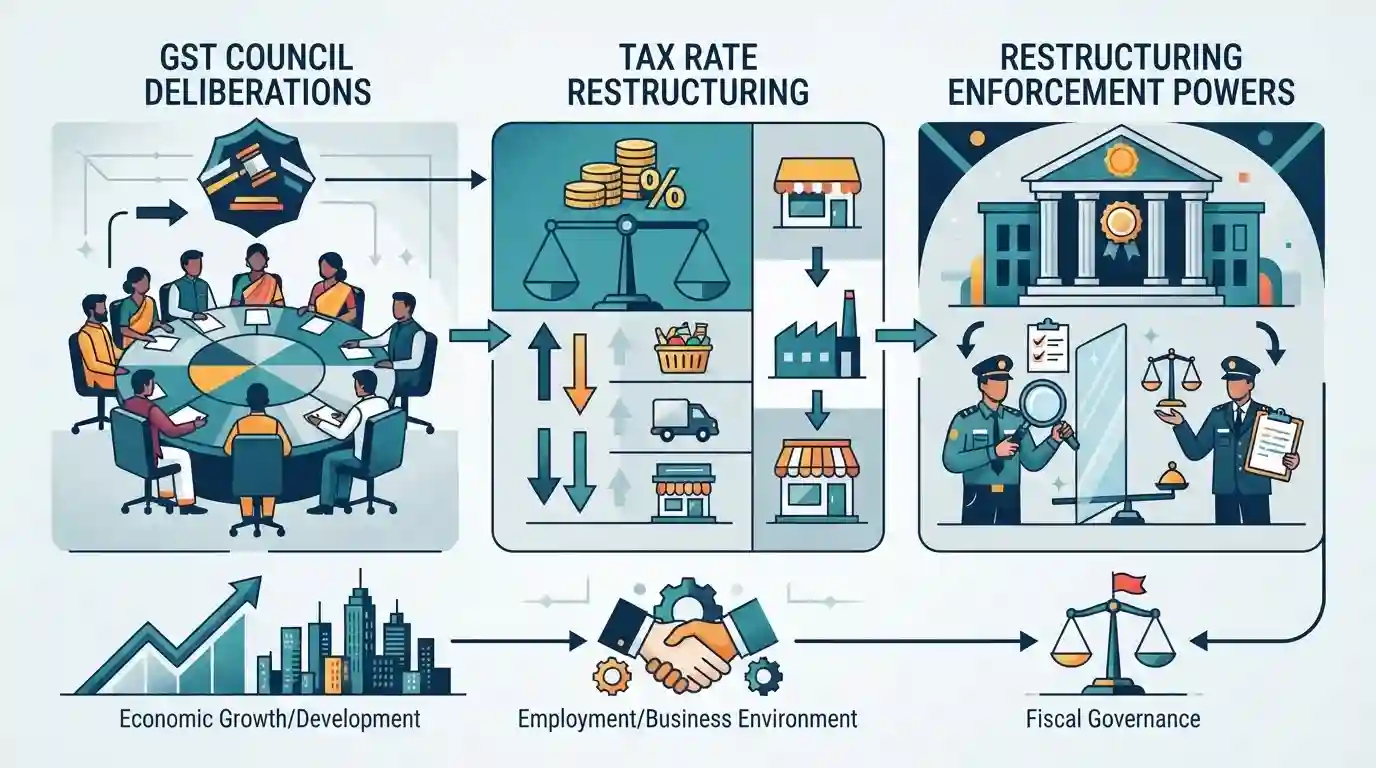
The article discusses decisions and deliberations from the GST Council meeting concerning the restructuring of arrest powers for tax officers and adjustments to tax rate structures, impacting businesses and fiscal governance.
Key Points
- The GST Council has proposed changes impacting tax officers' arrest powers and rate structures.
- Such reforms aim to balance ease of doing business with tax compliance.
- Highlights the ongoing evolution of the GST framework and cooperative federalism in India's taxation system.
Important Terms
Goods and Services Tax GST

A comprehensive, multi-stage, destination-based indirect tax levied on the supply of goods and services in India, replacing a cascade of central and state levies under the 101st Constitutional Amendment Act, 2016.
UPSC context
UPSC Prelims/Mains (GS Paper III - Economy): Tests knowledge of indirect taxation, federal fiscal architecture, and tax reforms.
GST Council
A constitutional body established under Article 279A of the Indian Constitution, comprising the Union Finance Minister and State Finance Ministers, tasked with making recommendations on GST rates, rules, and exemptions.
UPSC context
UPSC Prelims/Mains (GS Paper II & III): Tests federal governance, cooperative federalism, and institutional decision-making in fiscal policy.
Prelims Trap
The Union government can unilaterally pass any tax rate or structural reform in the GST Council due to its supreme fiscal authority.
Aspirants often confuse the Centre's absolute veto with majority rule; the Centre actually holds 1/3rd voting weight and requires state consensus, not unilateral command.
Static Concepts Connected
What are the constitutional provisions, composition, and voting mechanism of the GST Council under Article 279A?
- Article 279A: Constitutional Basis: Created under Article 279A, inserted by the 101st Constitutional Amendment Act, 2016.
- Composition: Composition: Chaired by the Union Finance Minister, with State Finance/Taxation Ministers as members.
- Weighted Voting: Voting Power: Centre holds 1/3rd of total votes; all states combined hold 2/3rds. Decisions require a 3/4th majority.
Cross-Topic Patterns
Cooperative Federalism and Fiscal Decentralisation
The GST Council's weighted voting formula (Centre 1/3, States 2/3) serves as India's premier testing ground for fiscal federalism under Article 279A, balancing state autonomy with national uniformity.
Decriminalisation of Economic Offences vs Revenue Security
Revising arrest thresholds balances criminal deterrence in tax evasion with the executive's push to decriminalize minor economic offenses and improve business sentiment.

GST Council voting mechanics (Art 279A) and prosecution threshold changes are prime candidates for a multi-statement Prelims question.
Linked PYQs · 2
Linked PYQs · 2
- 2019MainsGS3
Enumerate the indirect taxes which have been subsumed in the Goods and Services Tax (GST) in India. Also, comment on the revenue implications of the GST introduced in India since July 2017.
- 2025MainsGS2
Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?
