GST Council Discusses Tax Reforms and Arrest Power Scrapping
Source:Indian Express ↗
Why It Matters
The decisions of the GST Council directly impact fiscal federalism, tax compliance, the ease of doing business, and the balance between investigative powers and administrative overreach.
Summary
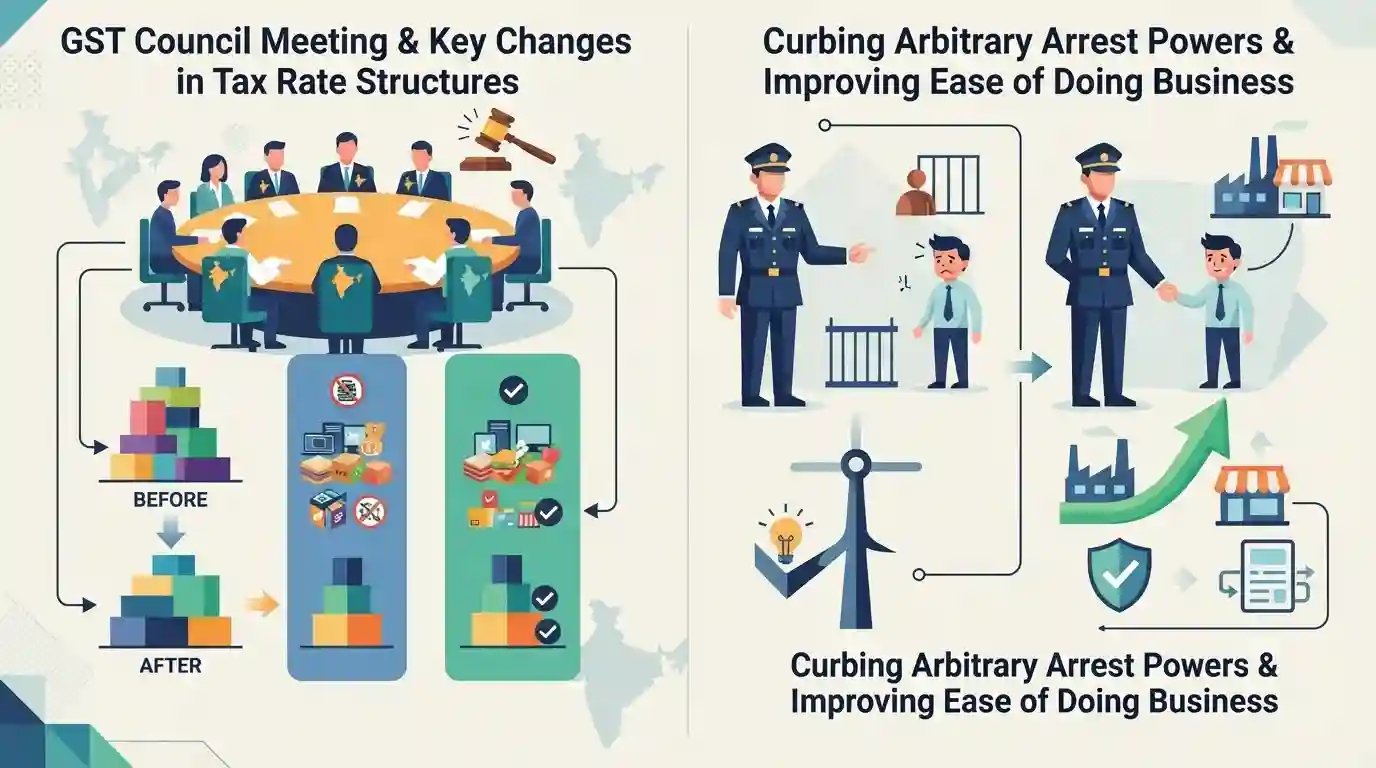
The GST Council meeting addressed key changes in tax rate structures and deliberated on curbing arbitrary arrest powers of tax officers to improve ease of doing business and reduce taxpayer harassment, while maintaining compliance.
Key Points
- The GST Council meeting discussed rationalisation of tax rates and structural changes.
- Proposals to curb tax evasion while reducing harassment by removing or restricting certain arrest powers of tax officers were evaluated.
- The move aims to balance compliance enforcement with improving the ease of doing business for traders and manufacturers.
Important Terms
GST Council

A constitutional body established under Article 279A by the 101st Amendment Act, comprising the Union Finance Minister and state finance ministers, to make recommendations on GST rates, exemptions, and tax administration.
UPSC context
GS Paper II (Polity - Federalism & Constitutional Bodies); tests understanding of cooperative federalism, Centre-State fiscal relations, and joint decision-making mechanisms.
101st Constitutional Amendment Act
The landmark legislation enacted in 2016 that paved the way for the nationwide rollout of the Goods and Services Tax by amending the Constitution and altering India's federal tax structure.
UPSC context
GS Paper II (Polity - Amendments & Federal Features) & GS Paper III (Economy - Taxation); tests constitutional changes in fiscal federalism.
Goods and Services Tax Act
The comprehensive set of legislative acts (Central GST, State GST, and Integrated GST) that govern the levy, collection, and administration of indirect taxes across India.
UPSC context
GS Paper III (Economy - Taxation, Growth, and Compliance); tests understanding of modern fiscal laws, ease of doing business, and tax compliance.
Prelims Trap
The GST Council is a statutory body set up under the Goods and Services Tax Act.
Aspirants often assume the GST Council is a statutory body created under an Act of Parliament, but it is a constitutional body established under Article 279A.
Static Concepts Connected
What are the constitutional provisions, composition, and voting weightage mechanism of the GST Council in India?
- Constitutional Basis: Article 279A empowers the President to constitute the GST Council as a constitutional body.
- Composition: Comprises the Union Finance Minister (Chairperson), Union Minister of State in charge of Revenue, and State Finance/Taxation Ministers.
- Voting Mechanism: The Centre has one-third voting weight and the States combined have two-thirds voting weight; decisions require a three-fourth majority.
Cross-Topic Patterns
Cooperative Federalism vs. Fiscal Centralization
GST Council decisions reflect the delicate constitutional balance between central and state fiscal autonomy, testing the strength of cooperative federalism in tax administration.
Trust-Based Governance and Ease of Doing Business
Reducing criminal liabilities and raising prosecution thresholds align tax policy with broader Ease of Doing Business and decriminalization of economic offences.

Expect a statement-based question on the constitutional status, voting mechanism, and recent decriminalization reforms of the GST Council.
Linked PYQs · 3
Linked PYQs · 3
- 2025MainsGS2
Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?
- 2023MainsGS2
Explain the significance of the 101st Constitutional Amendment Act. To what extent does it reflect the accommodative spirit of federalism?
- 2019MainsGS3
Enumerate the indirect taxes which have been subsumed in the Goods and Services Tax (GST) in India. Also, comment on the revenue implications of the GST introduced in India since July 2017.
