Pradhan Mantri Jan Dhan Yojana and Financial Inclusion Impact
Source:The Hindu ↗
Why It Matters
Financial inclusion and economic democracy are fundamental pillars of inclusive growth. Understanding the institutional mechanism of PMJDY, its integration with the JAM Trinity, and its socio-economic impacts (such as women empowerment and reducing leakages) is crucial for both Mains (GS3 Economy, GS2 Governance) and Prelims.
Summary
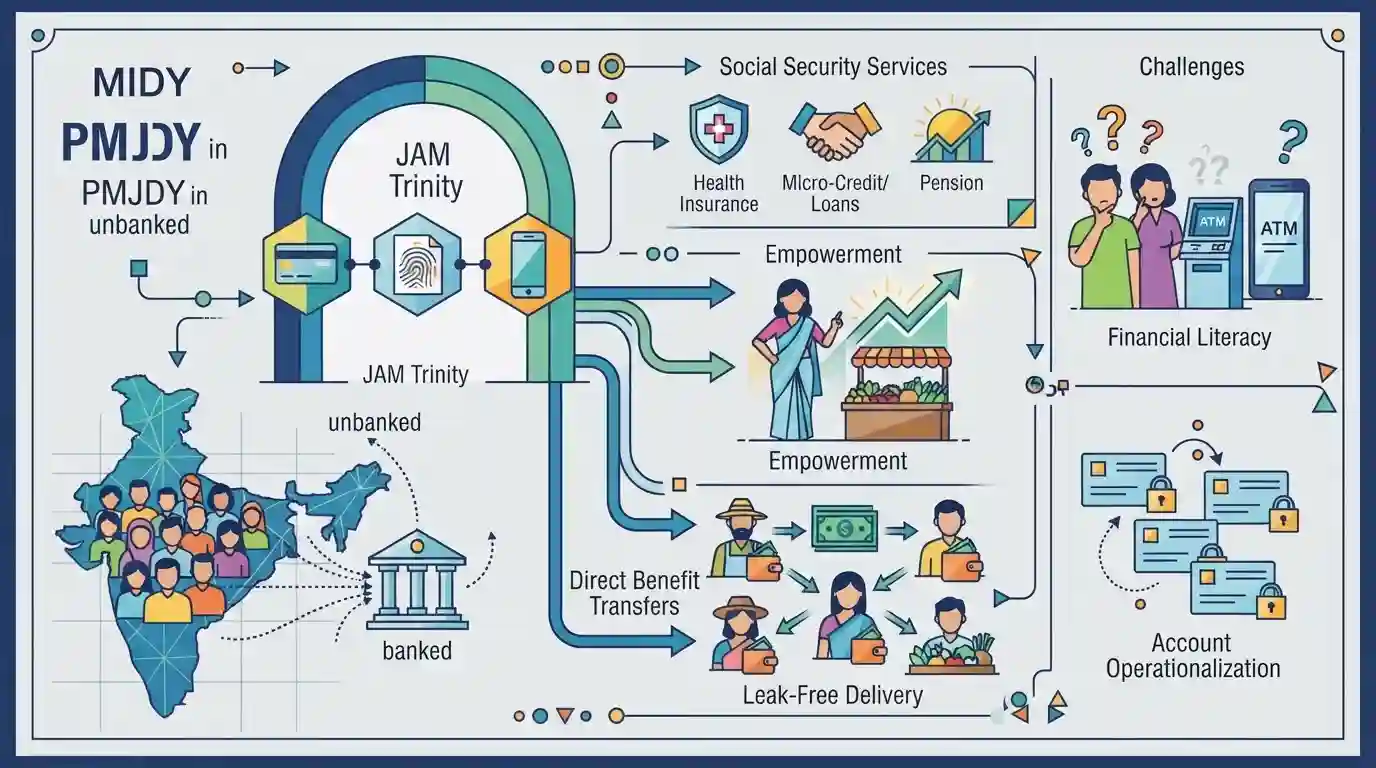
The article analyzes the transformative impact of the Pradhan Mantri Jan Dhan Yojana (PMJDY) in fostering 'financial democracy' in India. By bringing hundreds of millions of unbanked citizens into the formal financial system, PMJDY has shifted the paradigm of welfare delivery. It details how the integration of the JAM (Jan Dhan-Aadhaar-Mobile) trinity has enabled leak-free Direct Benefit Transfers, empowered women economically, and built a baseline for broader social security services like insurance and micro-credit, while also pointing out remaining challenges like financial literacy and account operationalization.
Key Points
- Financial Democracy as Inclusion: PMJDY has democratized access to the banking system, ensuring that opening an account is a universal right rather than an elite privilege.
- The JAM Trinity Evolution: The integration of Jan Dhan accounts with Aadhaar and Mobile (JAM Trinity) has created a robust digital public infrastructure (DPI) that supports leakproof governance and transparent Direct Benefit Transfers (DBT).
- Socio-Economic Empowerment of Women: Over 55% of PMJDY accounts are held by women, which significantly boosts their financial autonomy, household savings, and involvement in local economic activities.
- Deepening the Financial Safety Net: PMJDY serves as an gateway for marginalized sections to access micro-insurance (PMJJBY, PMSBY), pensions (Atal Pension Yojana), and overdraft credit facilities.
- Addressing Current Bottlenecks: Major operational challenges include reducing dormant/zero-balance accounts, improving rural banking infrastructure (via Business Correspondents), and enhancing financial and digital literacy to prevent cyber fraud.
Important Terms
Pradhan Mantri Jan Dhan Yojana (PMJDY)

India's national financial inclusion mission launched in 2014 to provide universal, affordable banking access, offering basic zero-balance savings accounts, overdraft facilities, RuPay debit cards, and basic insurance cover.
UPSC context
GS Paper III: Inclusive growth; GS Paper II: Welfare schemes for vulnerable sections.
JAM Trinity (Jan Dhan-Aadhaar-Mobile)
A core digital public infrastructure integration linking Jan Dhan bank accounts, Aadhaar biometric identity, and mobile numbers to enable targeted, leak-proof delivery of government welfare subsidies directly to citizens.
UPSC context
GS Paper III: Digital public infrastructure; GS Paper II: E-governance applications.
Direct Benefit Transfer (DBT)
A governance reform launched in 2013 that aims to transfer government subsidies, pensions, and scholarships directly into beneficiaries' Aadhaar-linked bank accounts, eliminating intermediaries and reducing leakage.
UPSC context
GS Paper III: Direct subsidies and savings; GS Paper II: Welfare delivery mechanisms.
National Payments Corporation of India (NPCI)
An umbrella organization founded in 2008 by RBI and IBA to operate retail payment and settlement systems in India, pioneering innovations like UPI, RuPay, and Aadhaar-enabled Payment Systems.
UPSC context
GS Paper III: Financial technology and mobilization of resources.
Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY)
A government-backed term life insurance scheme launched in 2015 offering ₹2 lakh life cover for death due to any reason to bank account holders aged 18-50 for an annual premium of ₹436.
UPSC context
GS Paper II: Social security nets; GS Paper III: Inclusive financial development.
Pradhan Mantri Suraksha Bima Yojana (PMSBY)
A government personal accident insurance scheme launched in 2015 providing ₹2 lakh cover for accidental death/permanent total disability and ₹1 lakh for partial disability to account holders aged 18-70 at ₹20 annually.
UPSC context
GS Paper II: Government welfare schemes; GS Paper III: Growth and social inclusion.
Atal Pension Yojana (APY)
A voluntary, co-contributory pension scheme launched in 2015 designed for workers in the unorganized sector (aged 18-40) providing a guaranteed minimum monthly pension of ₹1,000 to ₹5,000 after age 60.
UPSC context
GS Paper II: Social safety nets; GS Paper III: Resource mobilization.
Prelims Trap
PMJDY aimed to cover every unbanked adult in India since its launch in 2014.
In 2014, the target was 'every household'. It was structurally shifted to 'every unbanked adult' during its extension in 2018.
Static Concepts Connected
What is RBI’s Financial Inclusion (FI) Index and its structural parameters?
- Measurement parameters: Measures financial inclusion across three dimensions: Access (35% weight), Usage (45% weight), and Quality (20% weight).
- Scale and base: Constructed annually without a base year, ranging from 0 (complete exclusion) to 100 (complete inclusion).
- Target variables: Captures information on various aspects of financial literacy, consumer protection, and service deficiency.
How does Aadhaar Enabled Payment System (AePS) facilitate rural micro-banking?
- Underlying model: A bank-led model allowing interoperable financial transactions at Point of Sale devices through Business Correspondents.
- Core authentication: Requires only Aadhaar verification (biometric or OTP) and the bank name; no physical card or signature is needed.
- Enabled operations: Permits cash deposit, cash withdrawal, balance enquiry, and Aadhaar-to-Aadhaar fund transfers.
Cross-Topic Patterns
DPI exports and India's soft power
Leveraging India's open-source JAM tech stack as a template for digital sovereignty and bilateral cooperation with Global South nations.
Financial autonomy and Gender Budgeting
Directing welfare to women's accounts shifts intra-household bargaining power, directly advancing outcomes in health, nutrition, and education.

PMJDY's structural shift (household to adult) and micro-credit conditionalities likely to feature in a direct statement-based question.
Linked PYQs · 4
Linked PYQs · 4
- 2016MainsGS3
Pradhan Mantri Jan-Dhan Yojana (PMJDY) is necessary for bringing unbanked to the institutional finance fold. Do you agree with this for financial inclusion of the poorer section of the Indian society? Give arguments to justify your opinion.
- 2024PrelimsGS1
With reference to the Pradhan Mantri Jan Dhan Yojana (PMJDY), which of the following statements is/are correct? 1. The scheme aims to open bank accounts for unbanked households. 2. There is a minimum balance requirement for accounts opened under this scheme. 3. Beneficiaries get a Rupay Debit Card with an inbuilt accident insurance cover. Select the correct answer using the code given below.
- 2015PrelimsGS1
'Pradhan Mantri Jan-Dhan Yojana' has been launched for
- 2022MainsGS3
Is inclusive growth possible under market economy ? State the significance of financial inclusion in achieving economic growth in India.
