Rajasthan Finance and Appropriation Accounts Fiscal Scrutiny
Source:dainiknavajyoti ↗
Why It Matters
Important for understanding state-level fiscal governance, public accountability, audit mechanisms, and budget management in Rajasthan, frequently tested in RPSC RAS Prelims economy and polity sections.
Summary
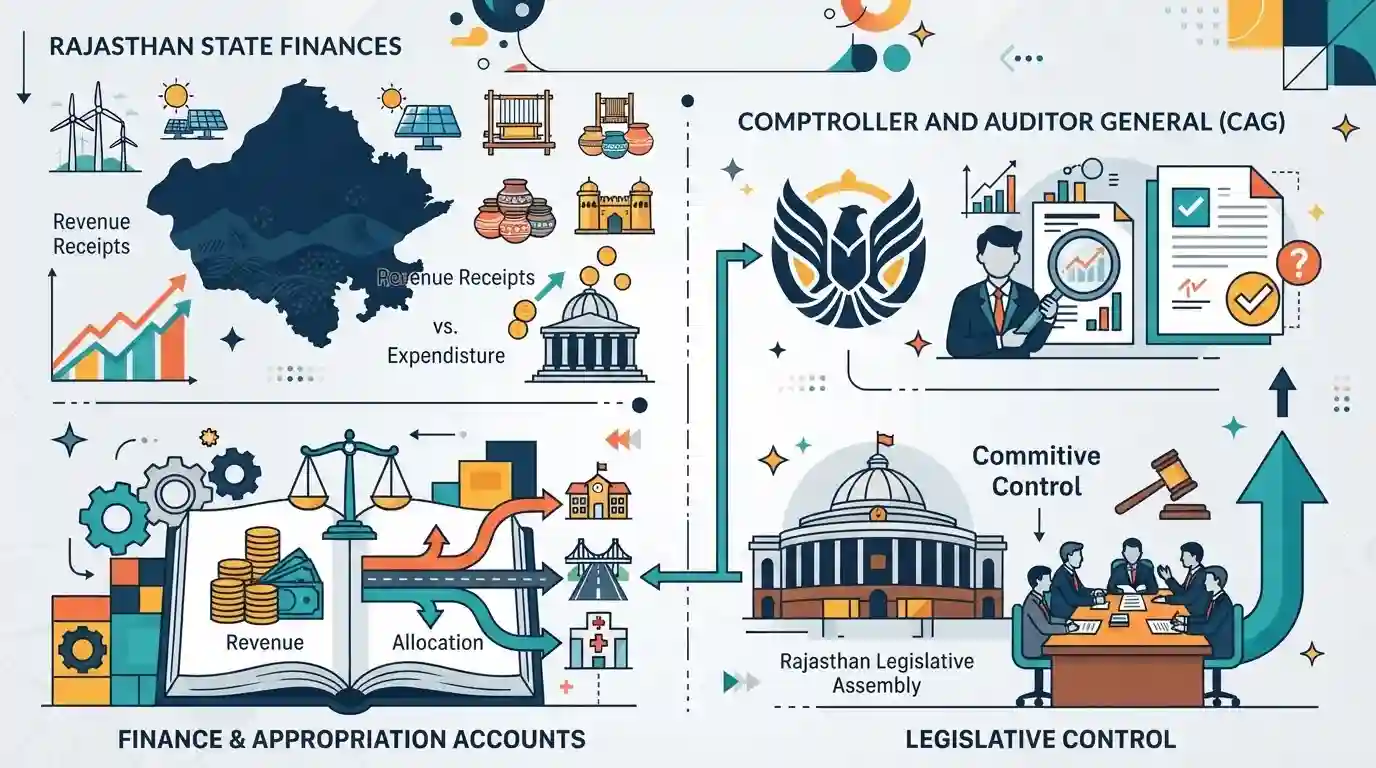
An overview of the Finance and Appropriation Accounts of the Rajasthan Government, highlighting state public finance trends, budget execution, and legislative oversight by bodies like the CAG and the Rajasthan Legislative Assembly committees.
Key Points
- The Finance and Appropriation Accounts of the Rajasthan Government detail the state's revenue, expenditure, and overall fiscal management for the financial year.
- These reports, prepared by the Comptroller and Auditor General (CAG), serve as crucial tools for legislative scrutiny over public finances and budget implementation in the Rajasthan Legislative Assembly.
- They provide insights into fiscal indicators like fiscal deficit, revenue deficit, and adherence to the FRBM Act limits.
Important Terms
Rajasthan Fiscal Responsibility and Budget Management Act

An Act enacted to ensure fiscal prudence, stability, and transparency in Rajasthan by reducing revenue deficits, managing public debt, and enforcing budgetary targets.
UPSC context
Important for RPSC (Economy & Polity - State Finances), testing knowledge of fiscal discipline rules and budget management in Rajasthan.
Comptroller and Auditor General of India (CAG)
An independent constitutional authority under Article 148 of the Indian Constitution responsible for auditing state and union accounts, including those of Rajasthan.
UPSC context
Crucial for RPSC Polity and Public Administration papers, testing oversight mechanisms and auditing of public funds.
Static Concepts Connected
What is the difference between Finance Accounts and Appropriation Accounts prepared by the CAG?
- Finance Accounts:: It shows the annual receipts and disbursements of the state government, detailing revenue and capital accounts, public debt, and loans/advances.
- Appropriation Accounts:: It accounts for the grants voted by the State Legislature and charged on the Consolidated Fund, highlighting cases of excess or savings in expenditure.
Cross-Topic Patterns
CAG Audit and PAC Accountability Linkage
The CAG audits state finances under Article 151, which are then examined by the Public Accounts Committee (PAC) of the Rajasthan Legislative Assembly, linking audit reports to legislative control.

CAG reports and FRBM Act compliance targets are frequently tested in RPSC economic administration and state budget MCQs.
Linked PYQs · 3
Linked PYQs · 3
- 2025RPSC_PRELIMSGS1
Consider the following statements regarding Rajasthan’s fiscal deficit: A. The actual fiscal deficit in 2022-23 was 3.76 percent of the state’s Gross Domestic Product. B. This is less than the limit approved by the F.R.B.M. Act, 2005. C. The fiscal deficit in 2022-23 was higher than in 2021-22. Choose the correct option:
- 2021RPSC_PRELIMSGS1
According to the rules of procedure and conduct of business of the Rajasthan Legislative Assembly, which of the following departments' appropriations is not under the control of the Appropriation Committee 'A'?
- 2024RPSC_PRELIMSGS1
Consider the following statements regarding fiscal deficit in 2022-23 of Rajasthan: A. Rajasthan fiscal deficit in the year 2022-23 has been 3.76 percent of GDP estimation. B. The recommended fiscal deficit presented by the F.R.B.M. Act, 2003.
