Formula-Based Devolution of State Grants for Urban Local Bodies
Source:The Hindu ↗
Why It Matters
This issue serves as a perfect contemporary case study for the persistent reluctance of State governments to financially empower Urban Local Bodies (a core challenge of the 74th Constitutional Amendment). It highlights the debate between discretionary funding and formula-based devolution necessary for equitable urban governance.
Summary
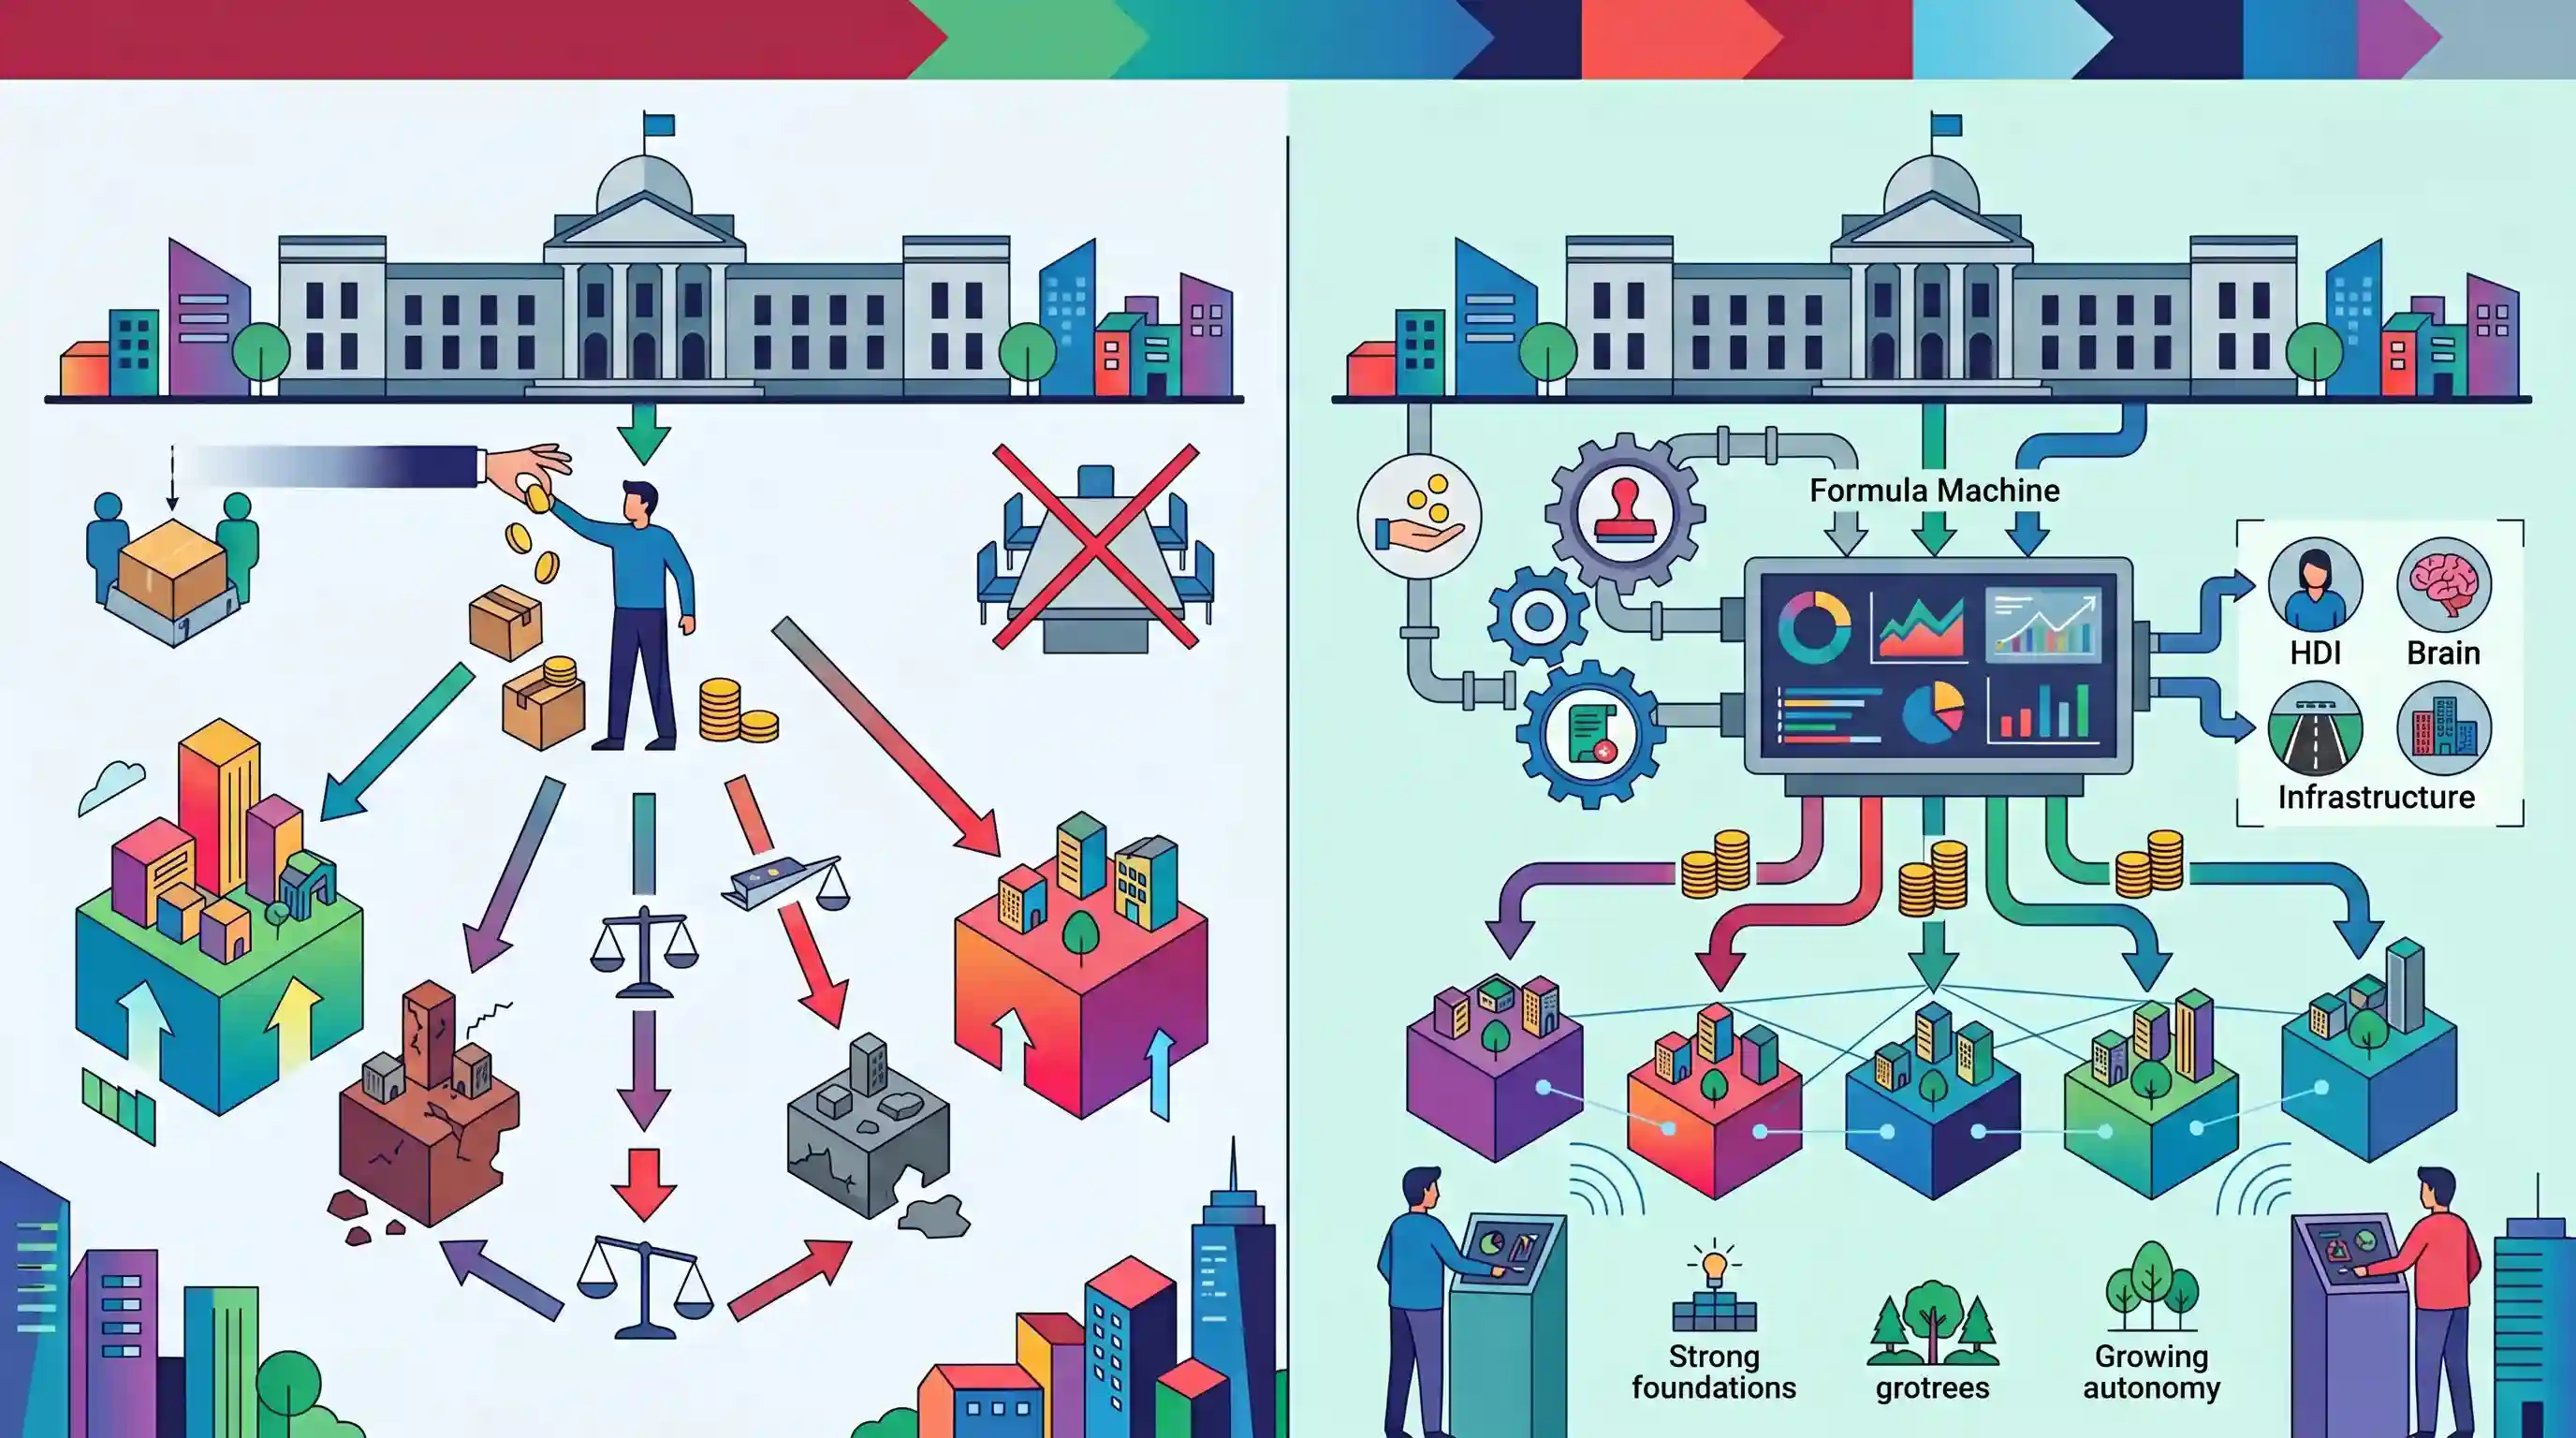
Experts and civic activists in Karnataka are advocating for a formula-based financial devolution of State grants to the five newly restructured city corporations of Bengaluru, criticizing the government's plan for discretionary, "need-based" allocations. Given the massive disparity in revenue-generating potential among the new corporate zones, stakeholders warn that ad-hoc funding will worsen civic inequity. The debate intensified after the Greater Bengaluru Governance Act, 2024 dropped a provision to establish a Finance Advisory Committee for the Greater Bengaluru Authority (GBA). Advocates recommend mirroring the Central Finance Commission by statutorily sharing state taxes (like GST and stamp duty) with local bodies based on an objective, ward-level infrastructure and human development index, ensuring genuine financial autonomy for urban local bodies.
Key Points
- The restructuring of Bengaluru into five new city corporations has triggered demands for a formula-based devolution of State government grants to urban local bodies.
- Activists argue against the state government's proposed discretionary "need-based" allocations, warning it could lead to political favoritism and inequitable urban development.
- Revenue generation potential varies drastically across the five new corporations (e.g., tech-heavy Mahadevapura vs. residential Yelahanka), necessitating an objective funding formula.
- The Greater Bengaluru Governance Act, 2024 controversially omitted a planned Finance Advisory Committee, centralizing financial power away from the Greater Bengaluru Authority (GBA).
- Experts recommend devolving a fixed share of state taxes (like GST, stamp duty, and vehicle tax) to municipal bodies based on a ward-level index incorporating infrastructure and human development metrics.
Important Terms
Greater Bengaluru Governance Act, 2024

Legislation enacted to restructure Bengaluru's urban governance into a three-tier system (GBA, multiple City Corporations, and Ward Committees), replacing the monolithic Bruhat Bengaluru Mahanagara Palike (BBMP) Act.
UPSC context
GS Paper II: Functions and responsibilities of the Union and the States, issues and challenges pertaining to the federal structure.
Greater Bengaluru Authority (GBA)
A statutory apex body chaired by the Karnataka Chief Minister, created to coordinate planning, infrastructure, and parastatal agencies across the newly formed city corporations in Bengaluru.
UPSC context
GS Paper II: Urban governance, metropolitan planning committees, and decentralization of powers (74th Constitutional Amendment).
State Finance Commission (SFC)
The constitutional body mandated under Articles 243-I and 243-Y to review the financial position of local bodies and recommend the principles for state tax devolution.
UPSC context
GS Paper II: Constitutional bodies; tests knowledge of fiscal federalism and financial health of local governments.
Bruhat Bengaluru Mahanagara Palike (BBMP)
The erstwhile monolithic municipal corporation responsible for Bengaluru's civic administration, which is being dissolved and restructured into five separate city corporations under new governance reforms.
UPSC context
GS Paper II: Local self-government and issues related to urban administration and service delivery.
Financial Devolution
The statutory transfer of financial resources and revenue-raising powers from the State government to local bodies (ULBs/PRIs) to ensure functional autonomy.
UPSC context
GS Paper II/III: Fiscal federalism, devolution of finances to the local level, and resource mobilization.
Finance Advisory Committee
A proposed but ultimately omitted body in the Greater Bengaluru Governance Act intended to recommend formula-based fund allocation among city corporations to prevent discretionary funding.
UPSC context
GS Paper II: Transparency and accountability in governance; institutional mechanisms for equitable resource distribution.
Prelims Trap
The Constitution mandates a fixed percentage of state tax revenue to be devolved to Urban Local Bodies.
Article 243Y only mandates State Finance Commissions to *recommend* devolution principles. The actual formula, quantum, and implementation are left to the discretion of the State Legislature.
Static Concepts Connected
What are the constitutional provisions for Urban Local Body (ULB) finances?
- Article 243X: Empowers the State Legislature to authorize municipalities to levy, collect, and appropriate specific taxes, duties, and tolls.
- Article 243Y: Mandates the State Finance Commission to review ULB finances and recommend principles for tax sharing and grants-in-aid.
- Article 280(3)(c): Mandates the Central Finance Commission to suggest measures to augment a State's Consolidated Fund to supplement municipal resources.
How did the 15th Finance Commission reform grants for Urban Local Bodies?
- Demographic Categorization: It created two distinct categories for tailored grant distribution: Million-Plus urban agglomerations and non-million-plus cities.
- Performance-Linked Grants: For Million-Plus cities, 100% of the grants are performance-based, strictly tied to improvements in air quality and sanitation benchmarks.
Cross-Topic Patterns
Double standards in fiscal federalism
States demand predictable, formulaic tax devolution from the Centre, yet frequently adopt discretionary, ad-hoc funding models for their own Urban Local Bodies, mirroring the centralization they criticize.
Parastatals vs 74th Amendment Act
The omission of Bengaluru's Finance Advisory Committee reflects a pan-India trend: states bypassing constitutionally mandated ULB autonomy in favor of state-controlled parastatals and centralized urban authorities.

Financial strangulation of ULBs via discretionary state grants vs Article 243Y principles is a prime candidate for a GS2 Mains 2026 question.
Linked PYQs · 2
Linked PYQs · 2
- 2023MainsGS2
“The states in India seem reluctant to empower urban local bodies both functionally as well as financially.” Comment.
- 2024MainsGS2
Analyse the role of local bodies in providing good governance at local level and bring out the pros and cons merging the rural local bodies with the urban local bodies.
