Critique addresses vertical imbalances in Indian fiscal federalism
Source:Indian Express ↗
Why It Matters
The constitution of the 16th Finance Commission has reignited debates over tax devolution. Understanding the distinction between vertical and horizontal devolution, the controversy over demographic criteria, and the impact of cesses and surcharges is highly relevant for GS2 (Polity - Federalism) and GS3 (Economy - State Finances).
Summary
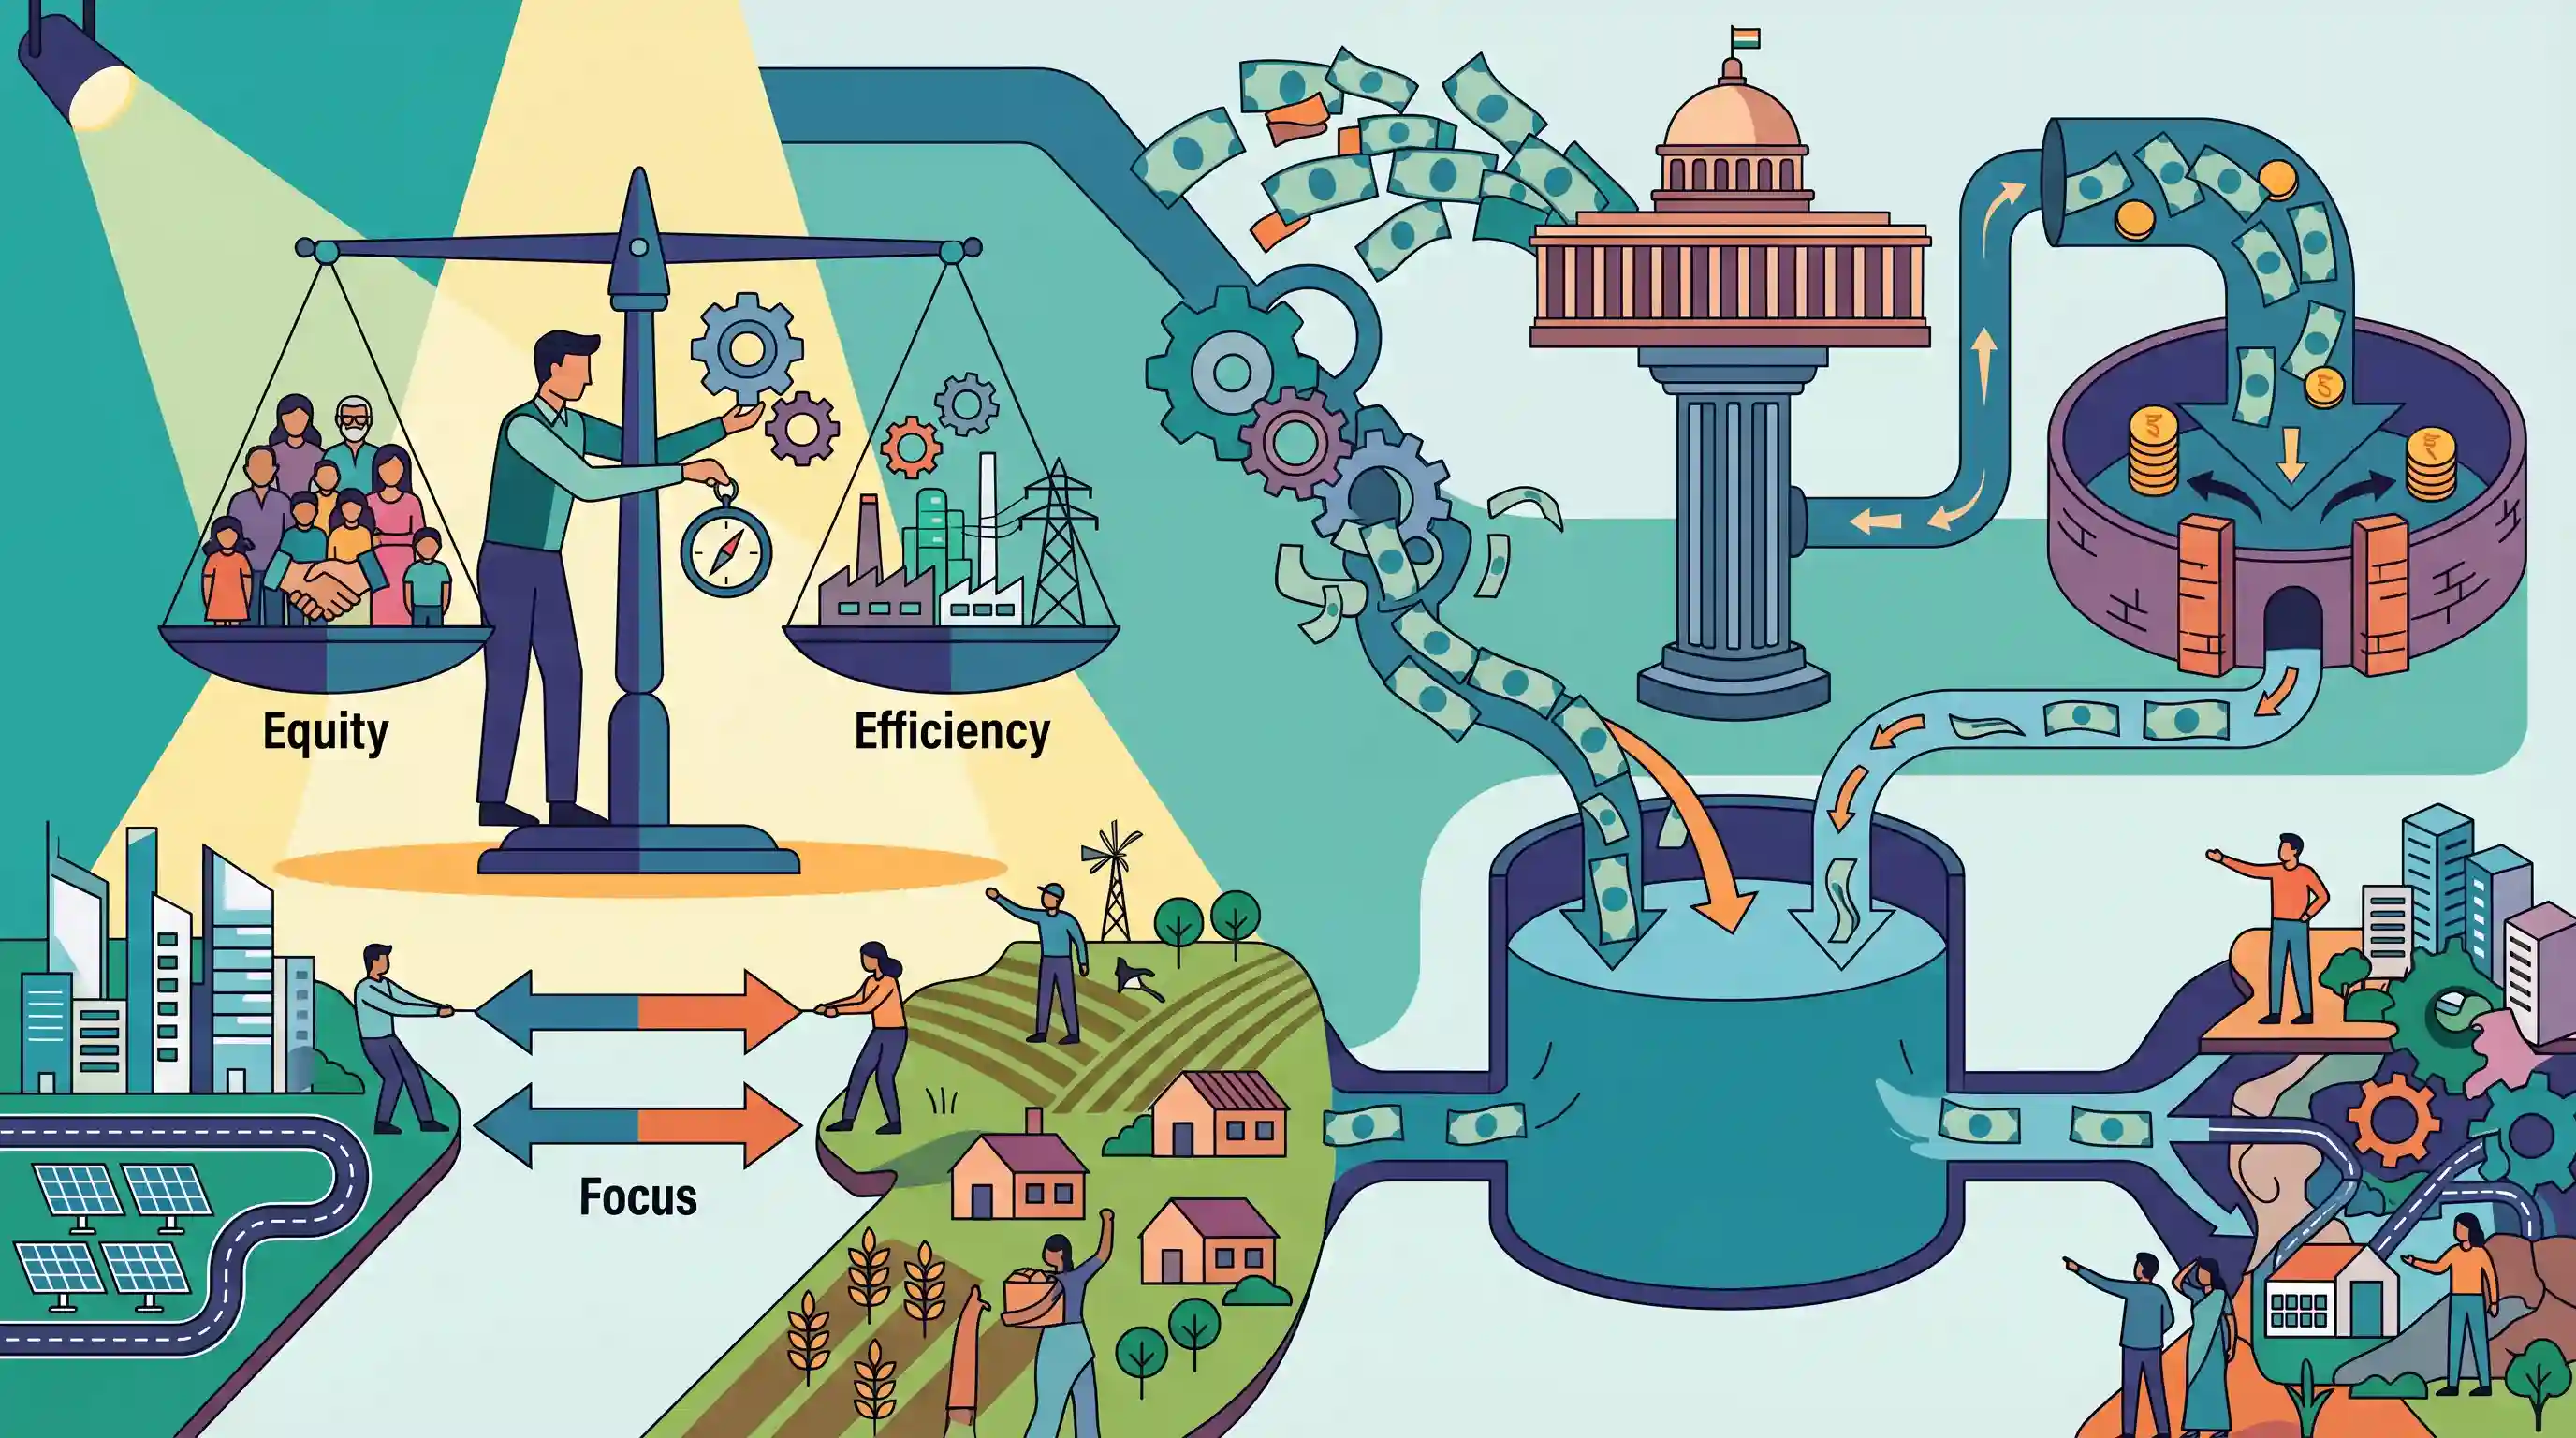
The article critiques the conventional narrative that frames the Finance Commission's mandate primarily as a 'balancing act' between equity and efficiency in resource allocation among states. It argues that this perspective is misleading because it masks deeper structural issues in India's fiscal federalism, particularly the vertical imbalance caused by the Union government's increasing reliance on cesses and surcharges. By keeping these levies out of the divisible pool, the Centre limits the total funds available to states. The piece urges a shift in focus from the horizontal tug-of-war between well-performing Southern states and less-developed Northern states, to addressing the systemic resource constraints in Centre-State financial relations.
Key Points
- The narrative that the Finance Commission merely performs a 'balancing act' between equity (supporting poorer states) and efficiency (rewarding performing states) is a misleading dichotomy.
- Framing the issue solely around horizontal devolution (state vs. state) distracts from the core structural problem of vertical imbalance between the Centre and the States.
- The Union government's increasing reliance on cesses and surcharges, which are excluded from the divisible tax pool, systematically shrinks the overall resources available for devolution to the states.
- To ensure robust fiscal federalism, the 16th Finance Commission must address these foundational asymmetries rather than merely tinkering with criteria like population or income distance to appease competing regional demands.
Important Terms
Finance Commission

A constitutional body established under Article 280 that recommends the distribution of financial resources between the Union and State governments to address vertical and horizontal fiscal imbalances.
UPSC context
GS2/Constitutional Bodies and GS3/Fiscal Policy; tests understanding of India's 'balancing wheel' of fiscal federalism.
Article 280 of the Constitution
The constitutional provision that mandates the President to constitute a Finance Commission every five years to recommend tax devolution and principles for grants-in-aid.
UPSC context
GS2/Indian Constitution; essential for explaining the legal framework governing Centre-State financial relations.
Fiscal Federalism
The system governing financial relationships between different levels of government, focusing on the allocation of revenue-raising powers and expenditure responsibilities.
UPSC context
GS2/Federalism and GS3/Indian Economy; tests ability to analyze cooperative federalism and states' financial autonomy.
Divisible Pool
The portion of total central tax revenue—excluding cesses and surcharges—that is legally mandated to be shared between the Union and the States.
UPSC context
GS3/Indian Economy; critical for discussing vertical fiscal imbalances and the impact of central levies on state finances.
Vertical Devolution
The sharing of the divisible pool of taxes between the Union government and the State governments collectively (e.g., the current 41% share).
UPSC context
GS3/Budgeting; tests knowledge of resource sharing ratios and the central government's fiscal dominance.
Horizontal Devolution
The distribution of the states' collective share of taxes among individual states based on criteria like population, income distance, and forest cover.
UPSC context
GS3/Indian Economy; evaluates the balancing of regional equity versus performance-based incentives for states.
Cesses and Surcharges
Additional levies imposed by the Centre for specific purposes; they are not part of the divisible pool, thus reducing the total resources shared with states.
UPSC context
GS2/Centre-State Relations and GS3/Taxation; a major point of contention regarding 'centralization' of financial powers.
Prelims Trap
"The divisible pool of taxes recommended by the Finance Commission includes all cesses and surcharges levied by the Union."
Under Articles 270 and 271, cesses and surcharges are explicitly excluded from the divisible pool and are retained entirely by the Union government.
Static Concepts Connected
What constitutes the divisible tax pool and how is it distributed?
- Divisible Pool: Comprises all Union taxes except cesses under Article 270 and surcharges under Article 271.
- Vertical Devolution: The total percentage of the divisible pool allocated collectively to all states (e.g., 41%).
- Horizontal Devolution: The formula dividing the states' collective share among individual states based on equity and efficiency.
How do cesses and surcharges differ under the Constitution?
- Cess: A tax levied for a specific purpose (Article 270) whose proceeds must be utilized only for that stated objective.
- Surcharge: An extra tax under Article 271 for general Union purposes, flowing directly into the Consolidated Fund of India.
- Constitutional Exclusion: Both are permanently excluded from the divisible pool, reducing the effective resource base available to states.
Cross-Topic Patterns
Delimitation freeze vs Fiscal devolution
The North-South debate over demographic performance in horizontal devolution directly shadows the looming post-2026 Lok Sabha delimitation crisis, tightly linking fiscal equity to political representation.
GST Compensation and Central reliance
The structural shrinkage of the divisible pool via cesses parallels past state struggles with GST compensation timelines, underscoring systemic vulnerabilities in India's asymmetrical federalism.

Expect a 2026 Prelims question linking the 16th FC's new 'Contribution to GDP' criterion with the constitutional exclusion of cesses.
Linked PYQs · 2
Linked PYQs · 2
- 2025MainsGS2
Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?
- 2025PrelimsGS1
Which of the following statements with regard to recommendations of the 15th Finance Commission of India are correct? I. It has recommended grants of ₹ 4,800 crores from the year 2022-23 to the year 2025-26 for incentivizing States to enhance educational outcomes. II. 45% of the net proceeds of Union taxes are to be shared with States. III. ₹ 45,000 crores are to be kept as performance-based incentive for all States for carrying out agricultural reforms. IV. It reintroduced tax effort criteria to reward fiscal performance. Select the correct answer using the code given below.
