Congress Alleges Sebi Probe Hindered by Tax Haven Non Cooperation
Source:The Hindu ↗
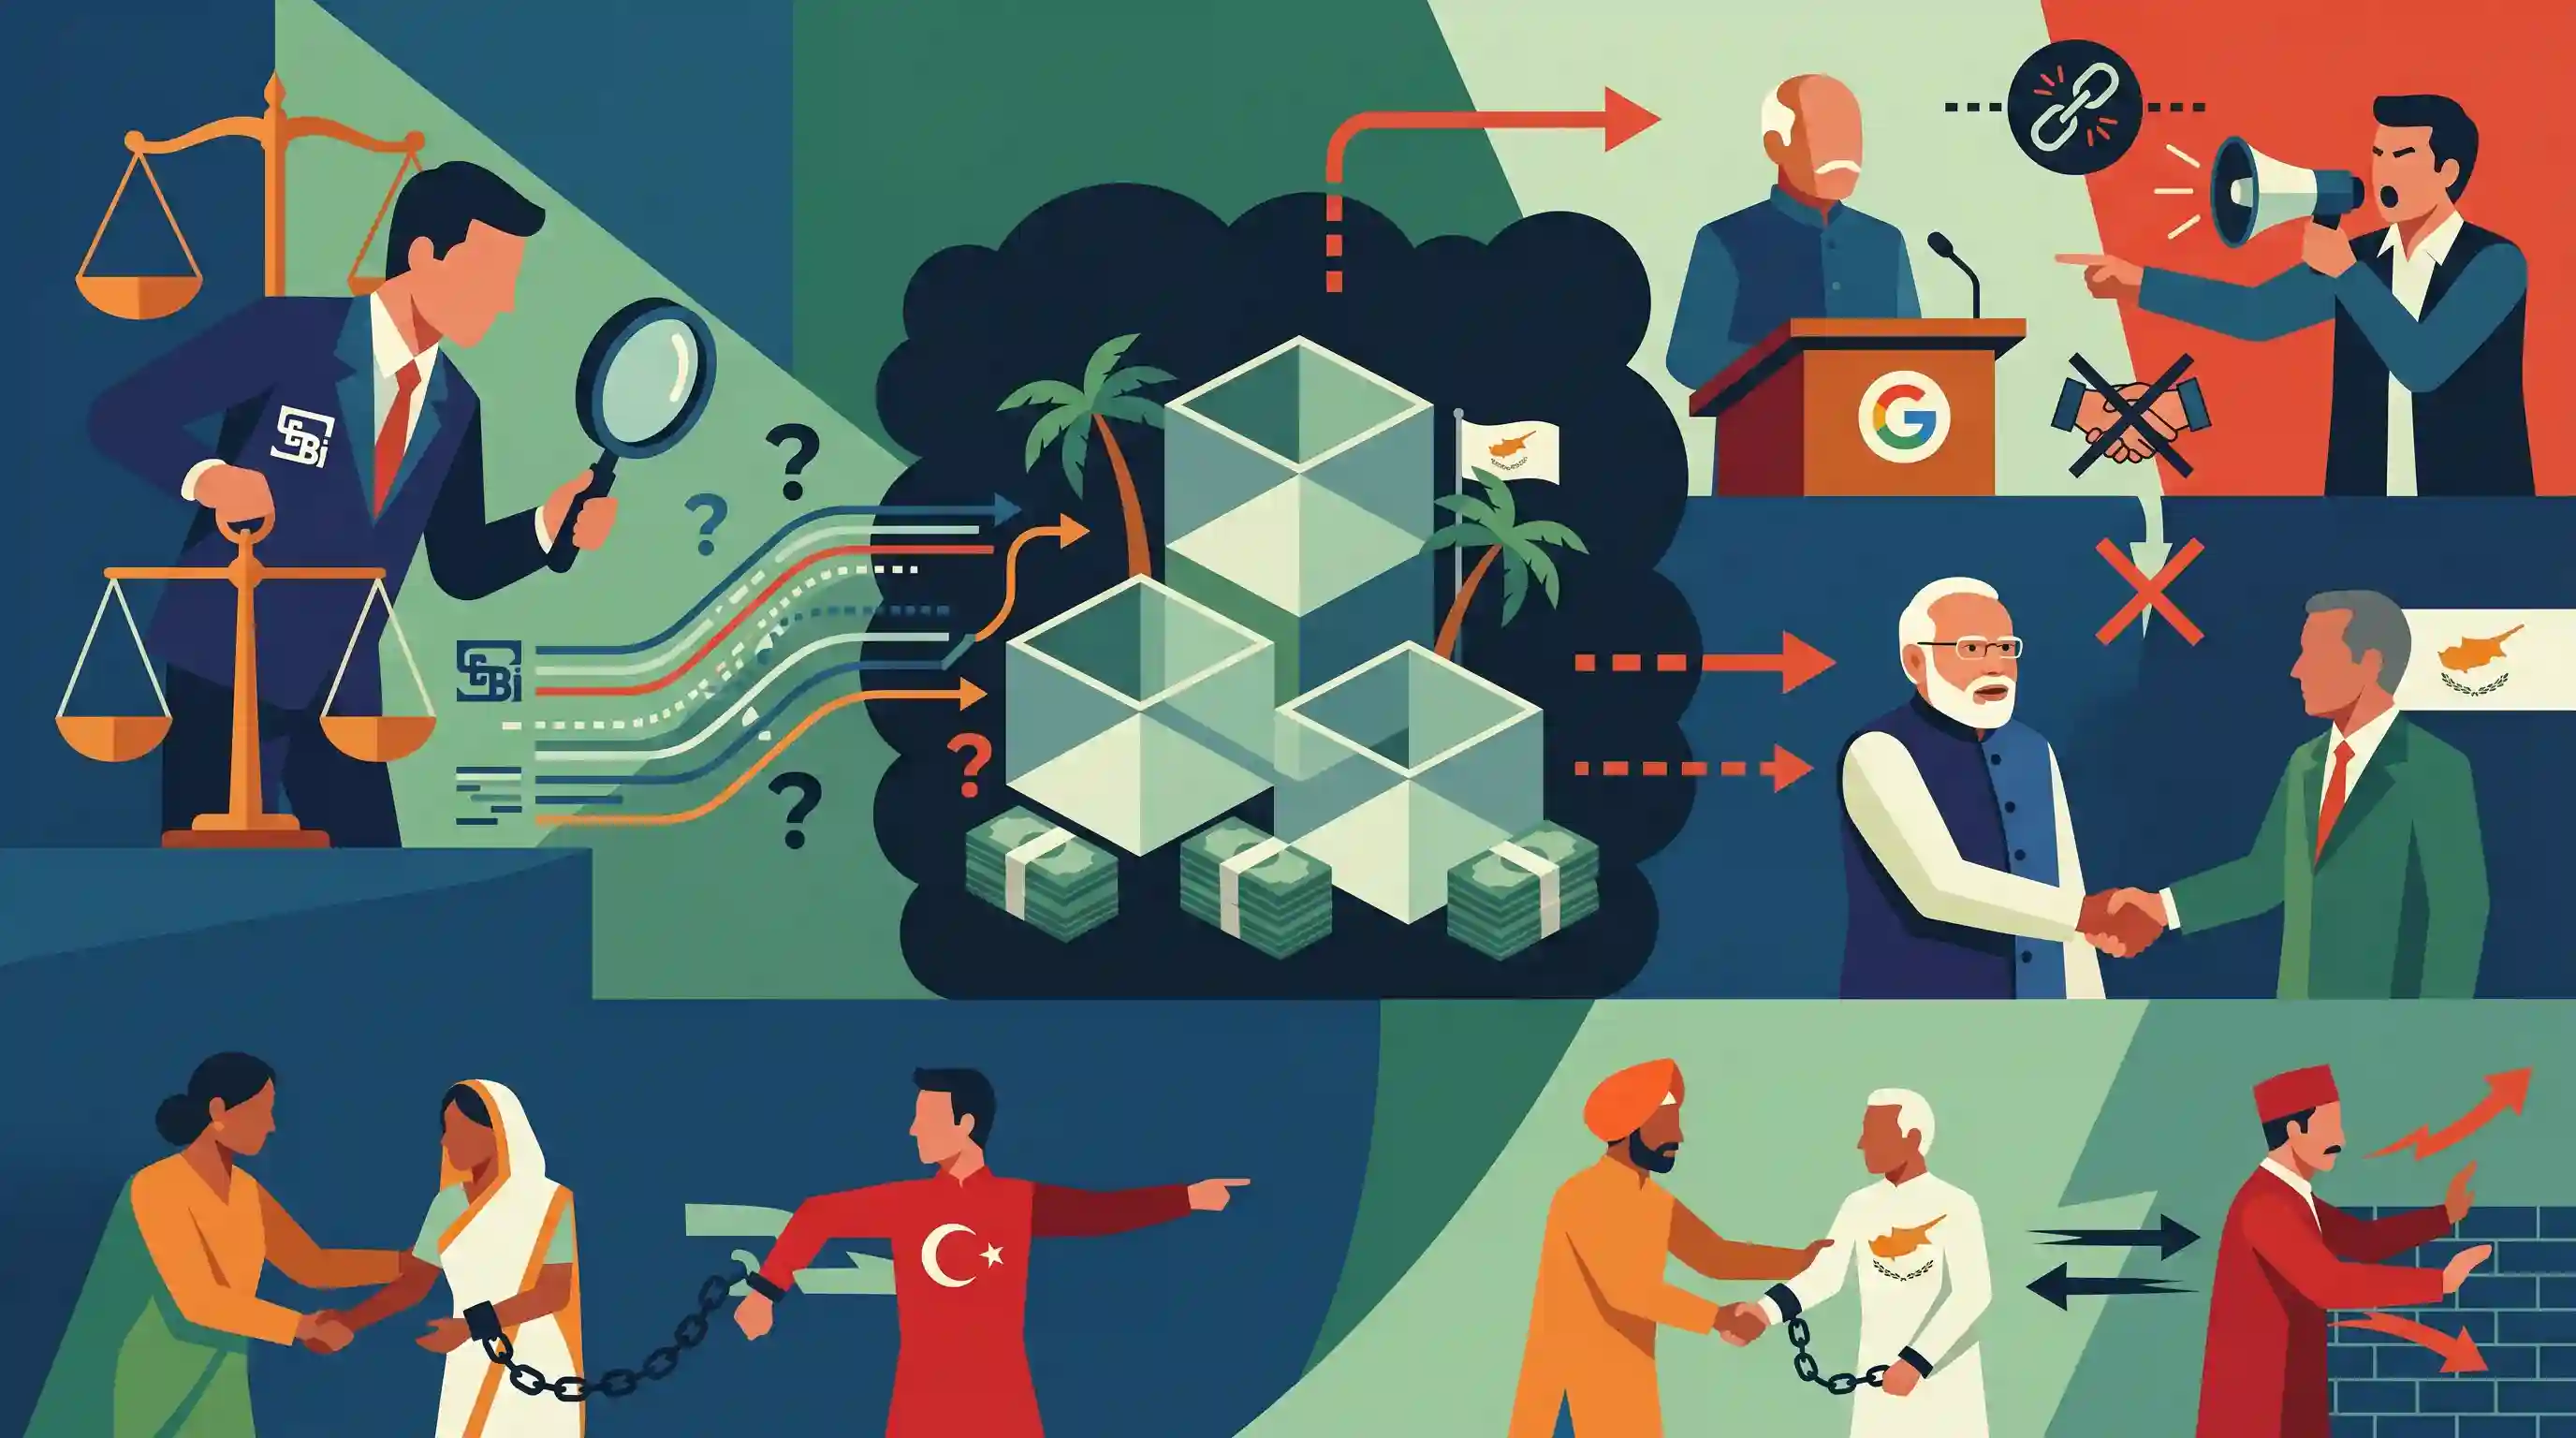
Why It Matters
The article provides a practical case study on the intersection of domestic financial regulation, the enforcement challenges posed by international tax havens, and bilateral diplomacy. It underscores the operational difficulties regulatory bodies like SEBI face in cross-border investigations while also highlighting the historical evolution of India's foreign policy in the Mediterranean region.
Summary
The Congress party has alleged that SEBI's investigation into the Adani Group is being hampered by a lack of information-sharing from tax haven countries, notably Cyprus. Highlighting the involvement of Cyprus-based offshore entities and shell companies, the opposition accused the government of failing to exert diplomatic pressure to uncover the financial trails. The controversy coincides with PM Modi's visit to Cyprus, drawing attention to India-Cyprus bilateral ties, which have historically been robust since India supported Cypriot independence in the 1950s—a foreign policy move that had previously strained India's relations with Turkiye.
Key Points
- Congress claims SEBI's probe into the Adani Group is stalled because tax haven countries, specifically Cyprus, are withholding crucial financial information.
- Allegations highlight the role of offshore entities, such as the Cyprus-based fund New Leaina and Amicorp, in setting up shell companies to obscure financial trails.
- The opposition argues that the Indian government has failed to exert adequate diplomatic pressure on these tax havens to assist the regulatory investigation.
- The article provides historical context regarding India's support for Cypriot independence under PM Nehru, noting that this diplomatic stance historically strained India-Turkiye relations.
Important Terms
Securities and Exchange Board of India (SEBI)

A statutory body established under the SEBI Act, 1992, to regulate the Indian securities market, protect investor interests, and ensure transparent market operations.
UPSC context
GS-II (Statutory Bodies) and GS-III (Indian Economy); tests knowledge of market regulation, investor protection, and corporate governance.
Tax Haven
A jurisdiction offering low or nil tax rates and high financial secrecy, allowing foreign individuals and businesses to park assets and minimize tax liabilities in their home countries.
UPSC context
GS-III (Indian Economy & Money Laundering); tests understanding of base erosion, profit shifting (BEPS), and internal security challenges.
Shell Company
A legally incorporated entity with no active business operations or significant assets, often used to obscure beneficial ownership, facilitate tax evasion, or move illicit funds.
UPSC context
GS-III (Internal Security & Corporate Governance); relevant for topics on black money, PMLA, and regulatory transparency.
India-Cyprus Relations
Strategic bilateral ties rooted in India's 1950s support for Cypriot independence; today, Cyprus serves as a key Mediterranean partner and a major source of FDI into India.
UPSC context
GS-II (International Relations); involves Mediterranean geopolitics, India-EU ties, and the strategic balancing of relations with Turkiye.
New Leaina
A Cyprus-based investment fund holding substantial stakes in Adani companies; it is under SEBI scrutiny regarding its ultimate beneficial ownership and potential round-tripping of funds.
UPSC context
GS-III (Economic Development); serves as a case study for offshore financial structures and regulatory hurdles in tracking foreign portfolio investments.
Amicorp
A global financial services intermediary alleged to have facilitated the creation of offshore shell companies and promoter entities for the purpose of masking financial trails.
UPSC context
GS-III (Internal Security); highlights the role of financial intermediaries in complex money laundering and tax avoidance schemes.
Double Taxation Avoidance Agreement (DTAA)
A bilateral treaty aimed at preventing the same income from being taxed twice, often utilized (or misused via 'Treaty Shopping') by entities in low-tax jurisdictions.
UPSC context
GS-III (Indian Economy); tests knowledge of international taxation, fiscal policy, and measures to curb revenue leakage.
Prelims Trap
"The India-Cyprus DTAA utilizes residence-based taxation for capital gains to encourage FDI inflows."
India revised its Double Taxation Avoidance Agreements with Cyprus, Mauritius, and Singapore in 2016, specifically shifting from residence-based to source-based taxation to curb tax evasion.
Static Concepts Connected
What is 'Round-tripping' in the context of Foreign Direct Investment (FDI)?
- Mechanism: Domestic money is channeled to a tax haven and disguised as foreign capital before returning to India as seemingly legitimate FDI.
- Primary Purpose: It is executed to launder illicit funds, manipulate domestic stock prices, or exploit loopholes in Double Taxation Avoidance Agreements (DTAAs).
- Regulatory Hurdle: Strict corporate secrecy laws in tax havens obscure the Ultimate Beneficial Owner (UBO), severely limiting investigations by market regulators.
How does the India-Cyprus relationship act as a geopolitical counterweight?
- Turkiye's Stance: Turkiye consistently aligns with Pakistan on the Kashmir dispute across multilateral forums like the UN and OIC.
- India's Counter: India counters this by steadfastly supporting the unified Republic of Cyprus against the unrecognized, Turkiye-backed Northern Cyprus.
Cross-Topic Patterns
SEBI's FPI Disclosure Rules
The inability to trace offshore shell company owners highlights the necessity of SEBI's recent regulatory mandates requiring granular Ultimate Beneficial Ownership (UBO) disclosures for high-risk Foreign Portfolio Investors (FPIs).
Cyprus in IMEC Logistics
Beyond its tax haven status, Cyprus's Eastern Mediterranean location allows it to pitch itself as a European maritime gateway and logistics node for the India-Middle East-Europe Economic Corridor (IMEC).

Expect a prelims question interlinking round-tripping, UBO disclosure norms, and the 2016 shift to source-based DTAA taxation.
Linked PYQs · 2
Linked PYQs · 2
- 2021MainsGS3
Discuss how emerging technologies and globalisation contribute to money laundering. Elaborate measures to tackle the problem of money laundering both at national and international levels.
- 2015MainsGS2
For achieving the desired objectives, it is necessary to ensure that the regulatory institutions remain independent and autonomous. Discuss in the light of the experiences in recent past.
