Commercial Insurance Rates Decline Across Key Segments in India
Source:Indian Express ↗
Why It Matters
Understanding the dynamics of the commercial insurance sector is vital for topics related to financial markets, corporate risk mitigation, and economic resilience. The evolving landscape of cyber insurance links directly to internal security challenges, while the role of insurance in buffering against climate events connects to disaster management.
Summary
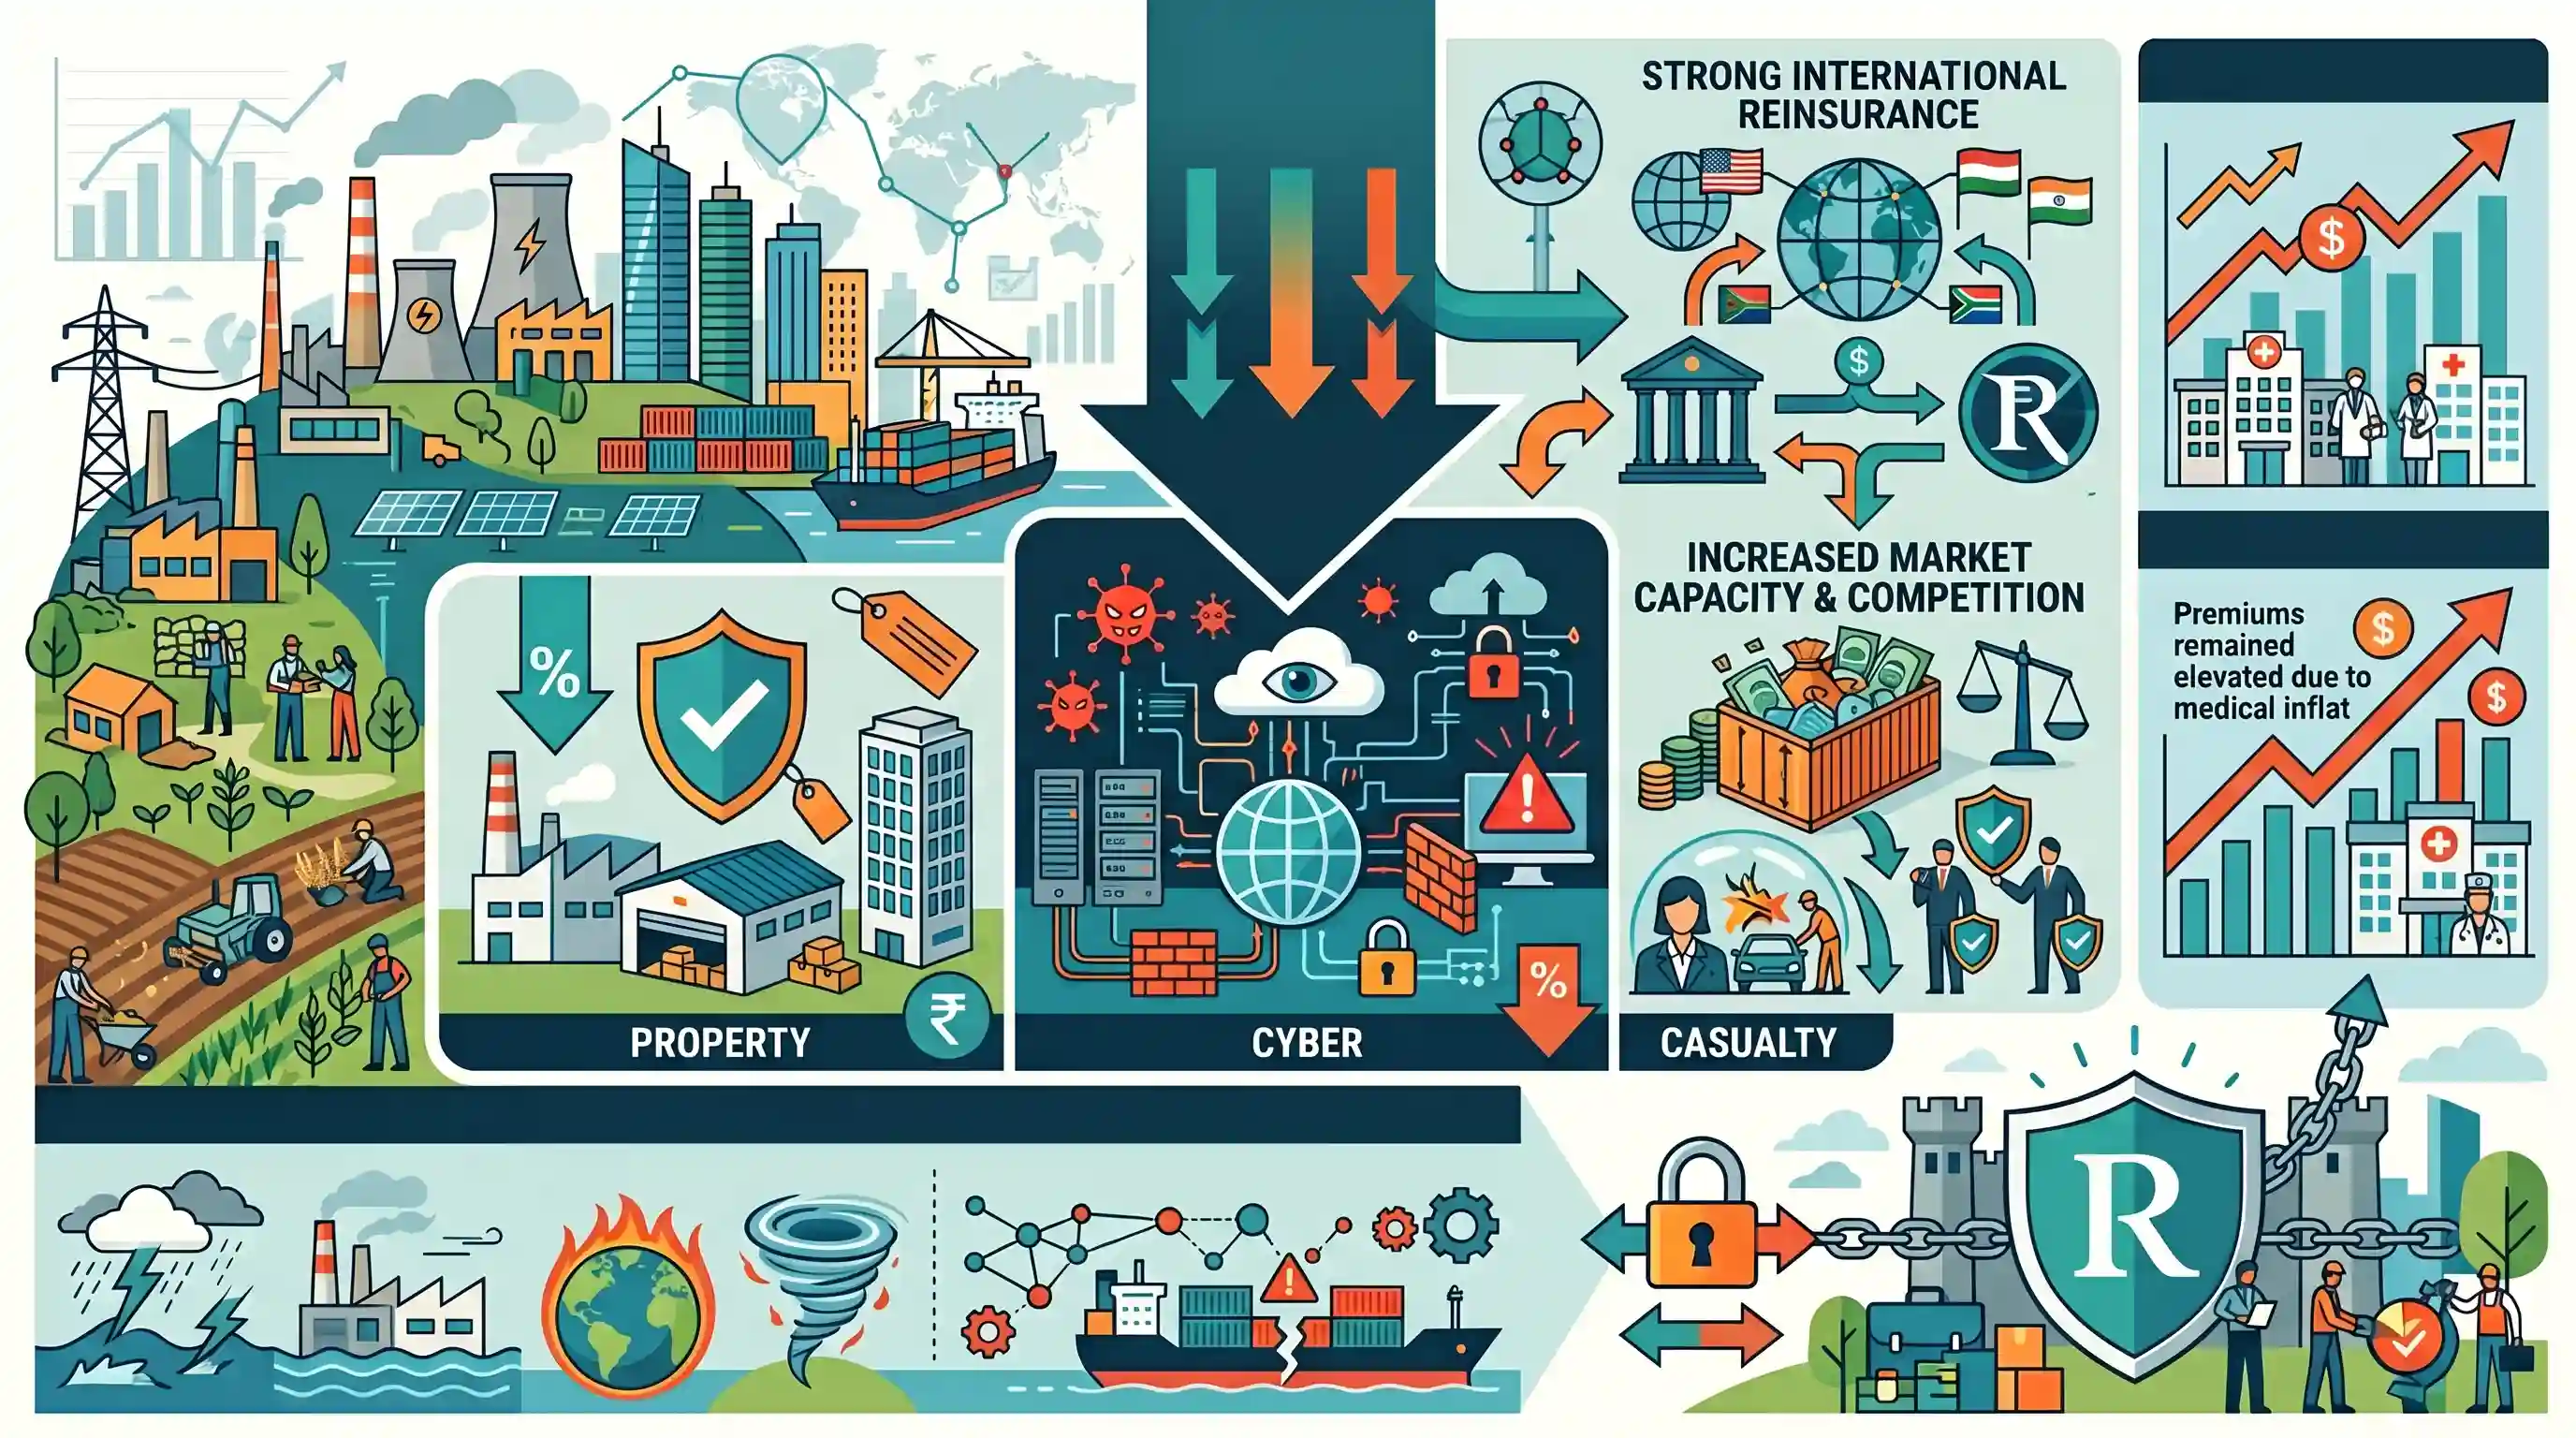
Commercial insurance rates in India dropped by up to 25% in the fourth quarter of 2025 across segments like property, cyber, and casualty lines. This reduction was primarily driven by strong international reinsurance backing, increased market capacity, and intense competition among insurers. Notably, cyber insurance rates decreased by 10-15% despite a surge in global cyber fraud cases. However, health insurance premiums remained elevated due to persistent medical inflation. The gross premium underwritten by non-life insurers in India stood at Rs 2.50 lakh crore for 2025. Experts emphasize that as India's risk profile evolves with climate-related events and supply chain vulnerabilities, strategic risk transfer mechanisms like insurance will be critical for long-term corporate resilience.
Key Points
- Commercial insurance rates in India witnessed a drop of up to 25% in the last quarter of 2025, covering lines such as property, casualty, and financial risks.
- Despite a global increase in cyber frauds and attacks, cyber insurance rates paradoxically fell by 10-15% due to heightened market competition and available capacity.
- Health insurance remained an exception to this trend, keeping high premium rates driven by persistent medical inflation.
- The gross premium underwritten by non-life insurers in India reached Rs 2.50 lakh crore during calendar year 2025.
- The decline in commercial insurance rates is attributed to strong international reinsurance support, increased domestic capacity, and robust competition.
- India's changing corporate risk profile, influenced by extreme weather events and supply chain vulnerabilities, highlights the need for long-term risk transfer and resilience strategies.
Important Terms
Reinsurance

A mechanism where an insurance company transfers a portion of its risk portfolio to another insurer (the reinsurer) to protect against large-scale financial losses.
UPSC context
GS Paper III (Economy); tests knowledge of financial stability, resource mobilization, and the regulatory role of IRDAI.
Cyber Insurance
A specialized insurance product covering financial losses, legal liabilities, and recovery costs arising from cyberattacks, data breaches, or digital disruptions.
UPSC context
GS Paper III (IT & Cyber Security); relevant to digital resilience and the Digital Personal Data Protection (DPDP) Act compliance.
Marsh Risk
The insurance broking and risk management arm of Marsh McLennan, which publishes the Global Insurance Market Index tracking commercial premium trends.
UPSC context
GS Paper III (Economy); understanding global market indicators that impact the cost of risk and capital for Indian industries.
Gross Direct Premium Underwritten (GDPU)
The total premium amount collected by an insurance company from policyholders during a specific period before accounting for reinsurance expenses.
UPSC context
GS Paper III (Economy); a core metric for measuring the insurance sector's growth and financial depth.
Medical Inflation
The annual percentage increase in the cost of healthcare services and medical supplies, typically outpacing the general inflation rate.
UPSC context
GS Paper II (Social Justice/Health); tests understanding of healthcare affordability and its impact on social safety nets.
Risk Transfer
A strategic risk management process involving the contractual shifting of a specific risk from one party to another, often via insurance.
UPSC context
GS Paper III (Disaster Management); essential for corporate and national resilience against catastrophic events and economic shocks.
Prelims Trap
"A general decline across all insurance premium segments occurred in India in 2025 due to increased domestic underwriting capacity."
Health insurance remained a structural exception. While commercial lines dropped, health premiums stayed highly elevated due to persistent double-digit medical inflation in India.
Static Concepts Connected
How are Insurance Penetration and Insurance Density measured in the Indian economy?
- Insurance Penetration: Measured as the ratio of total insurance premiums underwritten in a given year to the Gross Domestic Product (GDP).
- Insurance Density: Calculated as the ratio of total insurance premiums to the total population, representing the per capita premium in US Dollars.
- India's Status: India's penetration hovers around 4%, significantly lagging behind the global average, highlighting structural gaps in financial inclusion.
What is Reinsurance and how is it regulated in India?
- Core Concept: It is essentially 'insurance for insurers,' where companies transfer portions of their risk portfolios to other entities to reduce payout vulnerabilities.
- Indian Reinsurer: General Insurance Corporation of India (GIC Re) historically acts as the primary domestic reinsurer, though foreign reinsurers are now permitted to open branches.
- FDI & Regulation: The sector is regulated by IRDAI, and Foreign Direct Investment (FDI) in insurance companies (including reinsurers) is permitted up to 74% under the automatic route.
Cross-Topic Patterns
Climate risk & Parametric Insurance
Rising extreme weather events link GS3 Disaster Management to Economy. Strategic risk transfer tools like Catastrophe (CAT) bonds and parametric insurance are evolving to cover these climate-induced corporate liabilities.
Medical inflation and OOPE burden
While commercial rates fall, persistent 12-14% medical inflation keeps health premiums high. This directly undermines national public health efforts to reduce India's chronically high Out-of-Pocket Expenditure (OOPE).
Cyber frauds vs. Underwriting capacity
Despite a surge in global cyber attacks (GS3 Security), cyber insurance premiums dropped due to market overcapacity, showing how financial market dynamics can temporarily decouple from actual ground-level risks.

Expect a 2026 GS3 question evaluating how climate-induced corporate risks require novel financial transfer mechanisms like CAT bonds.
Linked PYQs · 4
Linked PYQs · 4
- 2022MainsGS3
Is inclusive growth possible under market economy ? State the significance of financial inclusion in achieving economic growth in India.
- 2024MainsGS3
What is disaster resilience? How is it determined? Describe various elements of a resilience framework. Also mention the global targets of Sendai Framework for Disaster Risk Reduction (2015–2030).
- 2017MainsGS3
Discuss the potential threats of Cyber attack and the security framework to prevent it.
- 2020PrelimsGS1
In India, under cyber insurance for individuals, which of the following benefits are generally covered, in addition to payment for the loss of funds and other benefits? 1. Cost of restoration of the computer system in case of malware disrupting access to one's computer 2. Cost of a new computer if some miscreant wilfully damages it, if proved so 3. Cost of hiring a specialized consultant to minimize the loss in case of cyber extortion 4. Cost of defence in the Court of Law if any third party files a suit Select the correct answer using the code given below:
