CAG ने चुनावों से पहले राजस्थान के स्थानीय निकायों में अप्रयुक्त फंड पर चिंता जताई
स्रोत:the-times-of-india ↗
क्यों मायने रखता है
The audit highlights critical gaps in fiscal decentralisation and fund utilisation within rural and urban local bodies in Rajasthan. For civil services aspirants, understanding the statutory provisions (such as Section 64 of the Rajasthan Panchayati Raj Act and Section 79 of the Rajasthan Municipal Act) and the role of the CAG in assessing propriety and efficiency of expenditure is crucial for polity, governance, and public administration.
सारांश
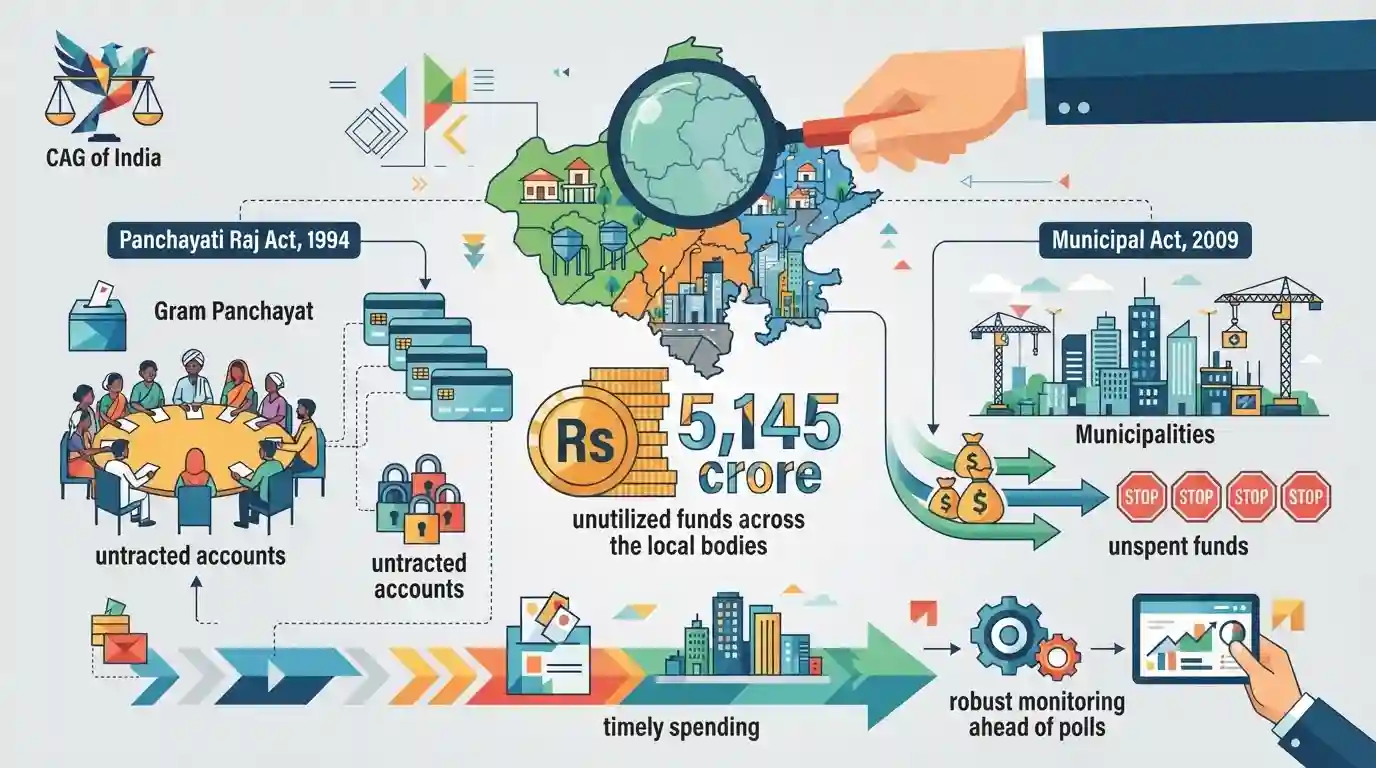
The Comptroller and Auditor General (CAG) of India has flagged significant fiscal planning issues in Rajasthan, noting unutilised local body funds exceeding Rs 5,145 crore across municipal and rural local bodies at the end of FY 2024-25. The audit highlighted a lack of systematic tracking for Gram Panchayat bank accounts and urged the state to implement robust monitoring to ensure that Finance Commission grants and local revenues are spent timely on civic development ahead of the upcoming urban local body polls.
मुख्य बिंदु
- Unutilised Funds in FY 2024-25: The CAG flagged massive idle balances at the end of 2024-25, including Rs 1,514.4 crore in Municipal Funds, Rs 1,718.34 crore in Zila Parishad (ZP) Funds, and Rs 1,912.68 crore in Panchayat Samiti (PS) Funds.
- प्रणालीगत प्रतिधारण: 2020-21 से 2024-25 तक की पांच वर्षों की अवधि में लगातार बड़ी शेष राशि रोकी रखी गई, जो स्थानीय विकास कार्यों के लिए व्यय नियोजन में कमियों को दर्शाती है।
- Gram Panchayat Tracking Deficits: The audit noted that the status of unutilised funds in Gram Panchayat (GP) bank accounts was not being properly maintained at the PS or ZP level, as GPs maintain accounts locally in scheduled banks.
- Statutory Provisions: Section 64 of the Rajasthan Panchayati Raj Act, 1994, governs the maintenance of GP, PS, and ZP Funds. Section 79 of the Rajasthan Municipal Act, 2009, governs the creation and maintenance of the Municipal Fund.
- Government Response: The Local Self Government Department attributed year-end balances to long tendering processes, project-linked payment schedules, and the receipt of scheme funds towards the end of the financial year.
- CAG की सिफारिशें: स्थानीय फंड के समय पर उपयोग के लिए एक तंत्र स्थापित करना, बंद हो चुकी योजनाओं की अप्रयुक्त शेष राशि को राजस्व मद (revenue head) में स्थानांतरित करना, और GP बैंक खातों की निगरानी को मजबूत करना।
महत्वपूर्ण शब्द
राजस्थान पंचायती राज अधिनियम, 1994

73वें संवैधानिक संशोधन के तहत राजस्थान में त्रि-स्तरीय ग्रामीण स्थानीय स्वशासन प्रणाली (ग्राम पंचायत, पंचायत समिति, जिला परिषद) को स्थापित और समेकित करने वाला प्राथमिक विधान।
UPSC context
RPSC RAS GS पेपर III: स्थानीय शासन, शक्तियों और ग्रामीण संस्थानों की अनुसूचियों का परीक्षण करता है।
राजस्थान नगरपालिका अधिनियम, 2009
राजस्थान में शहरी स्थानीय निकायों को विनियमित करने वाला एक व्यापक कानून, जो उनके संगठन, प्रत्यक्ष निर्वाचन प्रक्रियाओं, वित्तीय प्रशासन और 74वें संविधान संशोधन के तहत उनके कर्तव्यों को रेखांकित करता है।
UPSC context
RPSC EO/RO और RAS GS Paper III: शहरी स्थानीय स्वशासन ढांचे और प्रावधानों का परीक्षण करता है।
भारत के नियंत्रक और महालेखापरीक्षक
A constitutional office under Article 148 responsible for auditing receipts and expenditures of the Central and State governments, acting as the guardian of the public purse.
UPSC context
RPSC RAS GS Paper III: Tests constitutional bodies, financial accountability, and auditing of local resources.
राज्य वित्त आयोग
अनुच्छेद 243I और 243Y के तहत राज्यपाल द्वारा प्रत्येक पाँच वर्ष में स्थानीय वित्तीय स्थिति की समीक्षा करने और वित्तीय हस्तांतरण की सिफारिश करने के लिए गठित एक संवैधानिक निकाय।
UPSC context
RPSC RAS GS Paper III: ग्रामीण और शहरी स्थानीय निकायों को राजस्व के हस्तांतरण का परीक्षण करता है।
Local Self Government Department, Rajasthan
The administrative department overseeing urban local bodies (Municipal Corporations, Councils, Municipalities), executing state developmental policies, and managing urban sanitation and infrastructure.
UPSC context
RPSC RAS GS पेपर III: शहरों के लिए प्रशासनिक तंत्र और लोक नीति कार्यान्वयन का परीक्षण करता है।
Zila Parishad
जिला स्तर पर ग्रामीण स्थानीय स्वशासन का शीर्ष स्तर, जिसकी अध्यक्षता एक निर्वाचित जिला प्रमुख द्वारा की जाती है, जो ग्रामीण ब्लॉकों में विकास योजना की निगरानी करता है।
UPSC context
RPSC RAS GS Paper III: Tests the composition, powers, and structural hierarchy of Panchayati Raj.
पंचायत समिति
The intermediate tier of rural self-governance at the block level, coordinating development activities and administering resources across multiple Gram Panchayats.
UPSC context
RPSC RAS GS Paper III: Tests block-level administrative setup and rural project implementation.
Gram Panchayat
ग्रामीण स्थानीय स्वशासन का ग्राम-स्तरीय, प्राथमिक स्तर, जिसमें स्थानीय प्रशासन के प्रबंधन के लिए सरपंच के नेतृत्व में निर्वाचित वार्ड सदस्य शामिल होते हैं।
UPSC context
RPSC RAS GS Paper III: जमीनी स्तर के लोकतांत्रिक संस्थानों और ग्राम-स्तरीय नीति कार्यान्वयन का परीक्षण करता है।
संबद्ध PYQ · 3
संबद्ध PYQ · 3
- 2021RPSC_PRELIMSGS1
Statement (A): The duty of the Comptroller and Auditor General is not only to ensure the validity but also the propriety of expenditure. Reason (R): He is to maintain the Constitution and laws of Parliament in the field of financial administration.
- 2024RPSC_PRELIMSGS1
Which of the following is a matter on which the Finance Committee on 31st December considers? (i) The recommendation between the Union and the States of the net proceeds of the taxes which are to be, or may be, divided between them under Chapter I of Part XII of the Constitution. (ii) The Finance Commission shall govern the grants-in-aid of the revenues of the States. (iii) The resources needed to supplement the Consolidated Fund of a State to supplement the resources of the Panchayats. (iv) Review the present Climate Management Solutions.
- 2018RPSC_PRELIMSGS1
Which of the following Act/Rule provides for joint meetings of Gram Sabhas in Rajasthan?
