CAG रिपोर्ट ने NPS फंड ट्रांसफर में चूक और राजकोषीय देनदारी का खुलासा किया
स्रोत:the-times-of-india ↗
क्यों मायने रखता है
The transition of states from NPS back to OPS has substantial financial implications. This CAG audit highlights the fiscal reality of such policy reversals, including deferred liabilities and interest burdens, which are central to discussions on public financial management, state budgeting, and fiscal transparency.
सारांश
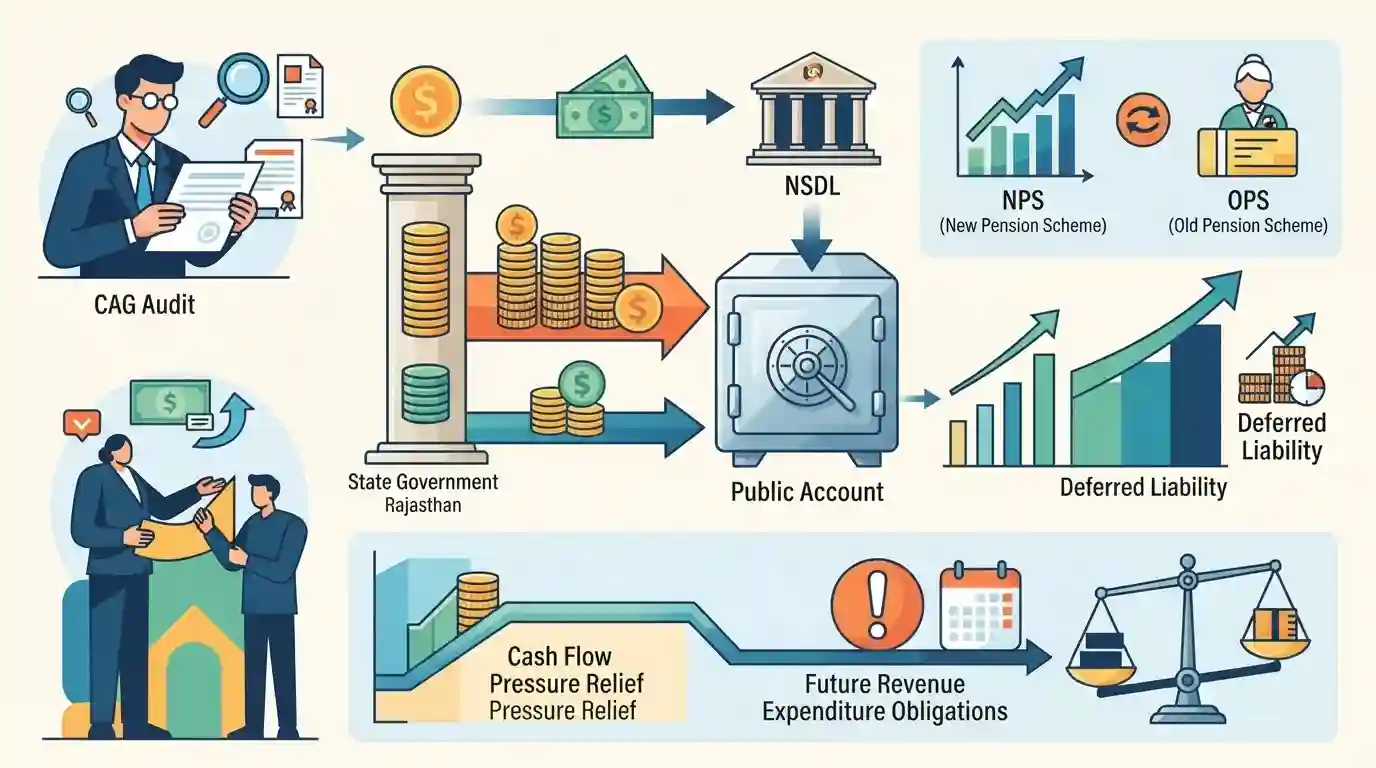
भारत के नियंत्रक और महालेखा परीक्षक (CAG) ने अपनी ऑडिट रिपोर्ट में खुलासा किया है कि राजस्थान सरकार पुरानी पेंशन योजना (OPS) पर वापस लौटने के तीन साल बाद भी नई पेंशन योजना (NPS) के लिए राज्य के कर्मचारियों से काटे गए ₹684.47 करोड़ नेशनल सिक्योरिटीज डिपॉजिटरी लिमिटेड (NSDL) में स्थानांतरित करने में विफल रही। राज्य के ₹684.47 करोड़ के समान योगदान और ₹49.16 करोड़ के परिहार्य ब्याज भार को मिलाकर, इस चूक के परिणामस्वरूप कुल ₹1,418.10 करोड़ की आस्थगित देनदारी (deferred liability) उत्पन्न हुई है। CAG ने चेतावनी दी है कि नकदी प्रवाह के दबाव को कम करने के लिए लोक खाते (Public Account) में प्रत्ययी सेवानिवृत्ति कोष (fiduciary retirement funds) को रखना कोई वास्तविक राजकोषीय बचत नहीं है, क्योंकि यह भविष्य में राजस्व व्यय के दायित्वों को सृजित करता है।
मुख्य बिंदु
- राजस्थान 1 अप्रैल, 2022 को नई पेंशन योजना (NPS) से पुरानी पेंशन योजना (OPS) में वापस लौट आया, जिससे 5,25,713 राज्य कर्मचारी (अखिल भारतीय सेवा के अधिकारियों को छोड़कर) प्रभावित हुए।
- During the transition, employee contributions of ₹684.47 crore (deducted for Jan–March 2022) were not transferred to NSDL and remained in the state's Public Account till March 2025.
- The state government was also required to make a matching contribution of ₹684.47 crore, bringing the principal deferred liability to ₹1,368.94 crore.
- इस देरी के कारण वर्ष 2024-25 के दौरान ₹49.16 करोड़ का परिहार्य ब्याज बोझ पड़ा, जिसने राज्य सरकार की कुल आस्थगित देनदारी को बढ़ाकर ₹1,418.10 करोड़ कर दिया और कर्मचारियों के रिटर्न को नुकसान पहुँचाया।
- The CAG observed that pension deductions have a fiduciary character. Parking these funds in the Public Account to ease short-term cash flow is not a genuine fiscal saving as it creates implicit future revenue obligations.
प्रारंभिक ट्रैप
The PFRDA Act allows state governments to legally reclaim accumulated NPS corpuses to fund their transition back to the Old Pension Scheme.
The PFRDA Act, 2013 has no legal provision for returning accumulated NPS corpuses to states; the funds belong solely to subscribers.
संबंधित अवधारणाएँ
What are the core targets of the Rajasthan FRBM Act, 2005?
- अधिनियमन वर्ष: राजकोषीय अनुशासन को संस्थागत करने, राजकोषीय घाटे को कम करने और राजस्थान के सार्वजनिक ऋण-से-GSDP अनुपात को प्रबंधित करने के लिए 2005 में अधिनियमित किया गया।
- राजकोषीय घाटे की सीमा: Prescribes keeping the fiscal deficit within 3% of GSDP, subject to conditional relaxations allowed by the Finance Commission.
- Mandatory disclosures: Requires presenting Medium-Term Fiscal Policy and Fiscal Policy Strategy Statements annually before the State Legislative Assembly.
संविधान CAG द्वारा ऑडिट किए जाने वाले राज्य के खातों को किस प्रकार वर्गीकृत करता है?
- संचित निधि: Under Article 266(1), contains all revenues, loans raised, and receipts of the State; requires legislative appropriation for withdrawals.
- लोक खाता: Under Article 266(2), holds public money other than consolidated funds (e.g., PF, deposits); transactions do not require legislative approval.
- Contingency Fund: Under Article 267(2), placed at the disposal of the Governor to meet unforeseen expenditure pending legislative authorization.
अंतर-विषय पैटर्न
NPS-OPS शिफ्ट और राज्य का कर्ज
OPS पर वापस लौटने से 'परिभाषित योगदान' (defined contributions) के स्थान पर 'परिभाषित लाभ' (defined benefits) की व्यवस्था आ जाती है, जिससे राज्यों का अल्पकालिक वित्तीय बहिर्वाह (outflows) तो कम हो जाता है, लेकिन दीर्घकालिक प्रतिबद्ध राजस्व व्यय (long-term committed revenue expenditure) उत्तरोत्तर बढ़ जाता है और ऋण-से-GSDP अनुपात में वृद्धि होती है।
CAG ऑडिट और राजकोषीय पारदर्शिता
Parking employee deductions in Public Accounts to artificially depress fiscal deficits is caught by CAG’s off-budget liability disclosures, ensuring transparency under FRBM.

राजस्थान के FRBM लक्ष्यों और लोक लेखा देनदारियों पर CAG के निष्कर्षों से जुड़े कथनों के राज्य की अर्थव्यवस्था के प्रश्नपत्रों में पूछे जाने की अत्यधिक संभावना है।
संबद्ध PYQ · 4
संबद्ध PYQ · 4
- 2021RPSC_PRELIMSGS1
Statement (A): The duty of the Comptroller and Auditor General is not only to ensure the validity but also the propriety of expenditure. Reason (R): He is to maintain the Constitution and laws of Parliament in the field of financial administration.
- 2018RPSC_PRELIMSGS1
The process of removing the Comptroller and Auditor General of India from his office is similar to that of which one of the following?
- 2025RPSC_PRELIMSGS1
Consider the following statements regarding Rajasthan’s fiscal deficit: A. The actual fiscal deficit in 2022-23 was 3.76 percent of the state’s Gross Domestic Product. B. This is less than the limit approved by the F.R.B.M. Act, 2005. C. The fiscal deficit in 2022-23 was higher than in 2021-22. Choose the correct option:
- 2023RPSC_PRELIMSGS1
In which year did the Rajasthan government enact the Rajasthan Fiscal Responsibility and Budget Management Act?
