Cloud Computing Tax Incentives and Data Centre Infrastructure
Source:Indian Express ↗
Why It Matters
Understanding taxation incentives for digital infrastructure is crucial for analyzing India's economic policies aimed at fostering tech growth, ensuring data localization, and competing globally in the digital economy.
Summary
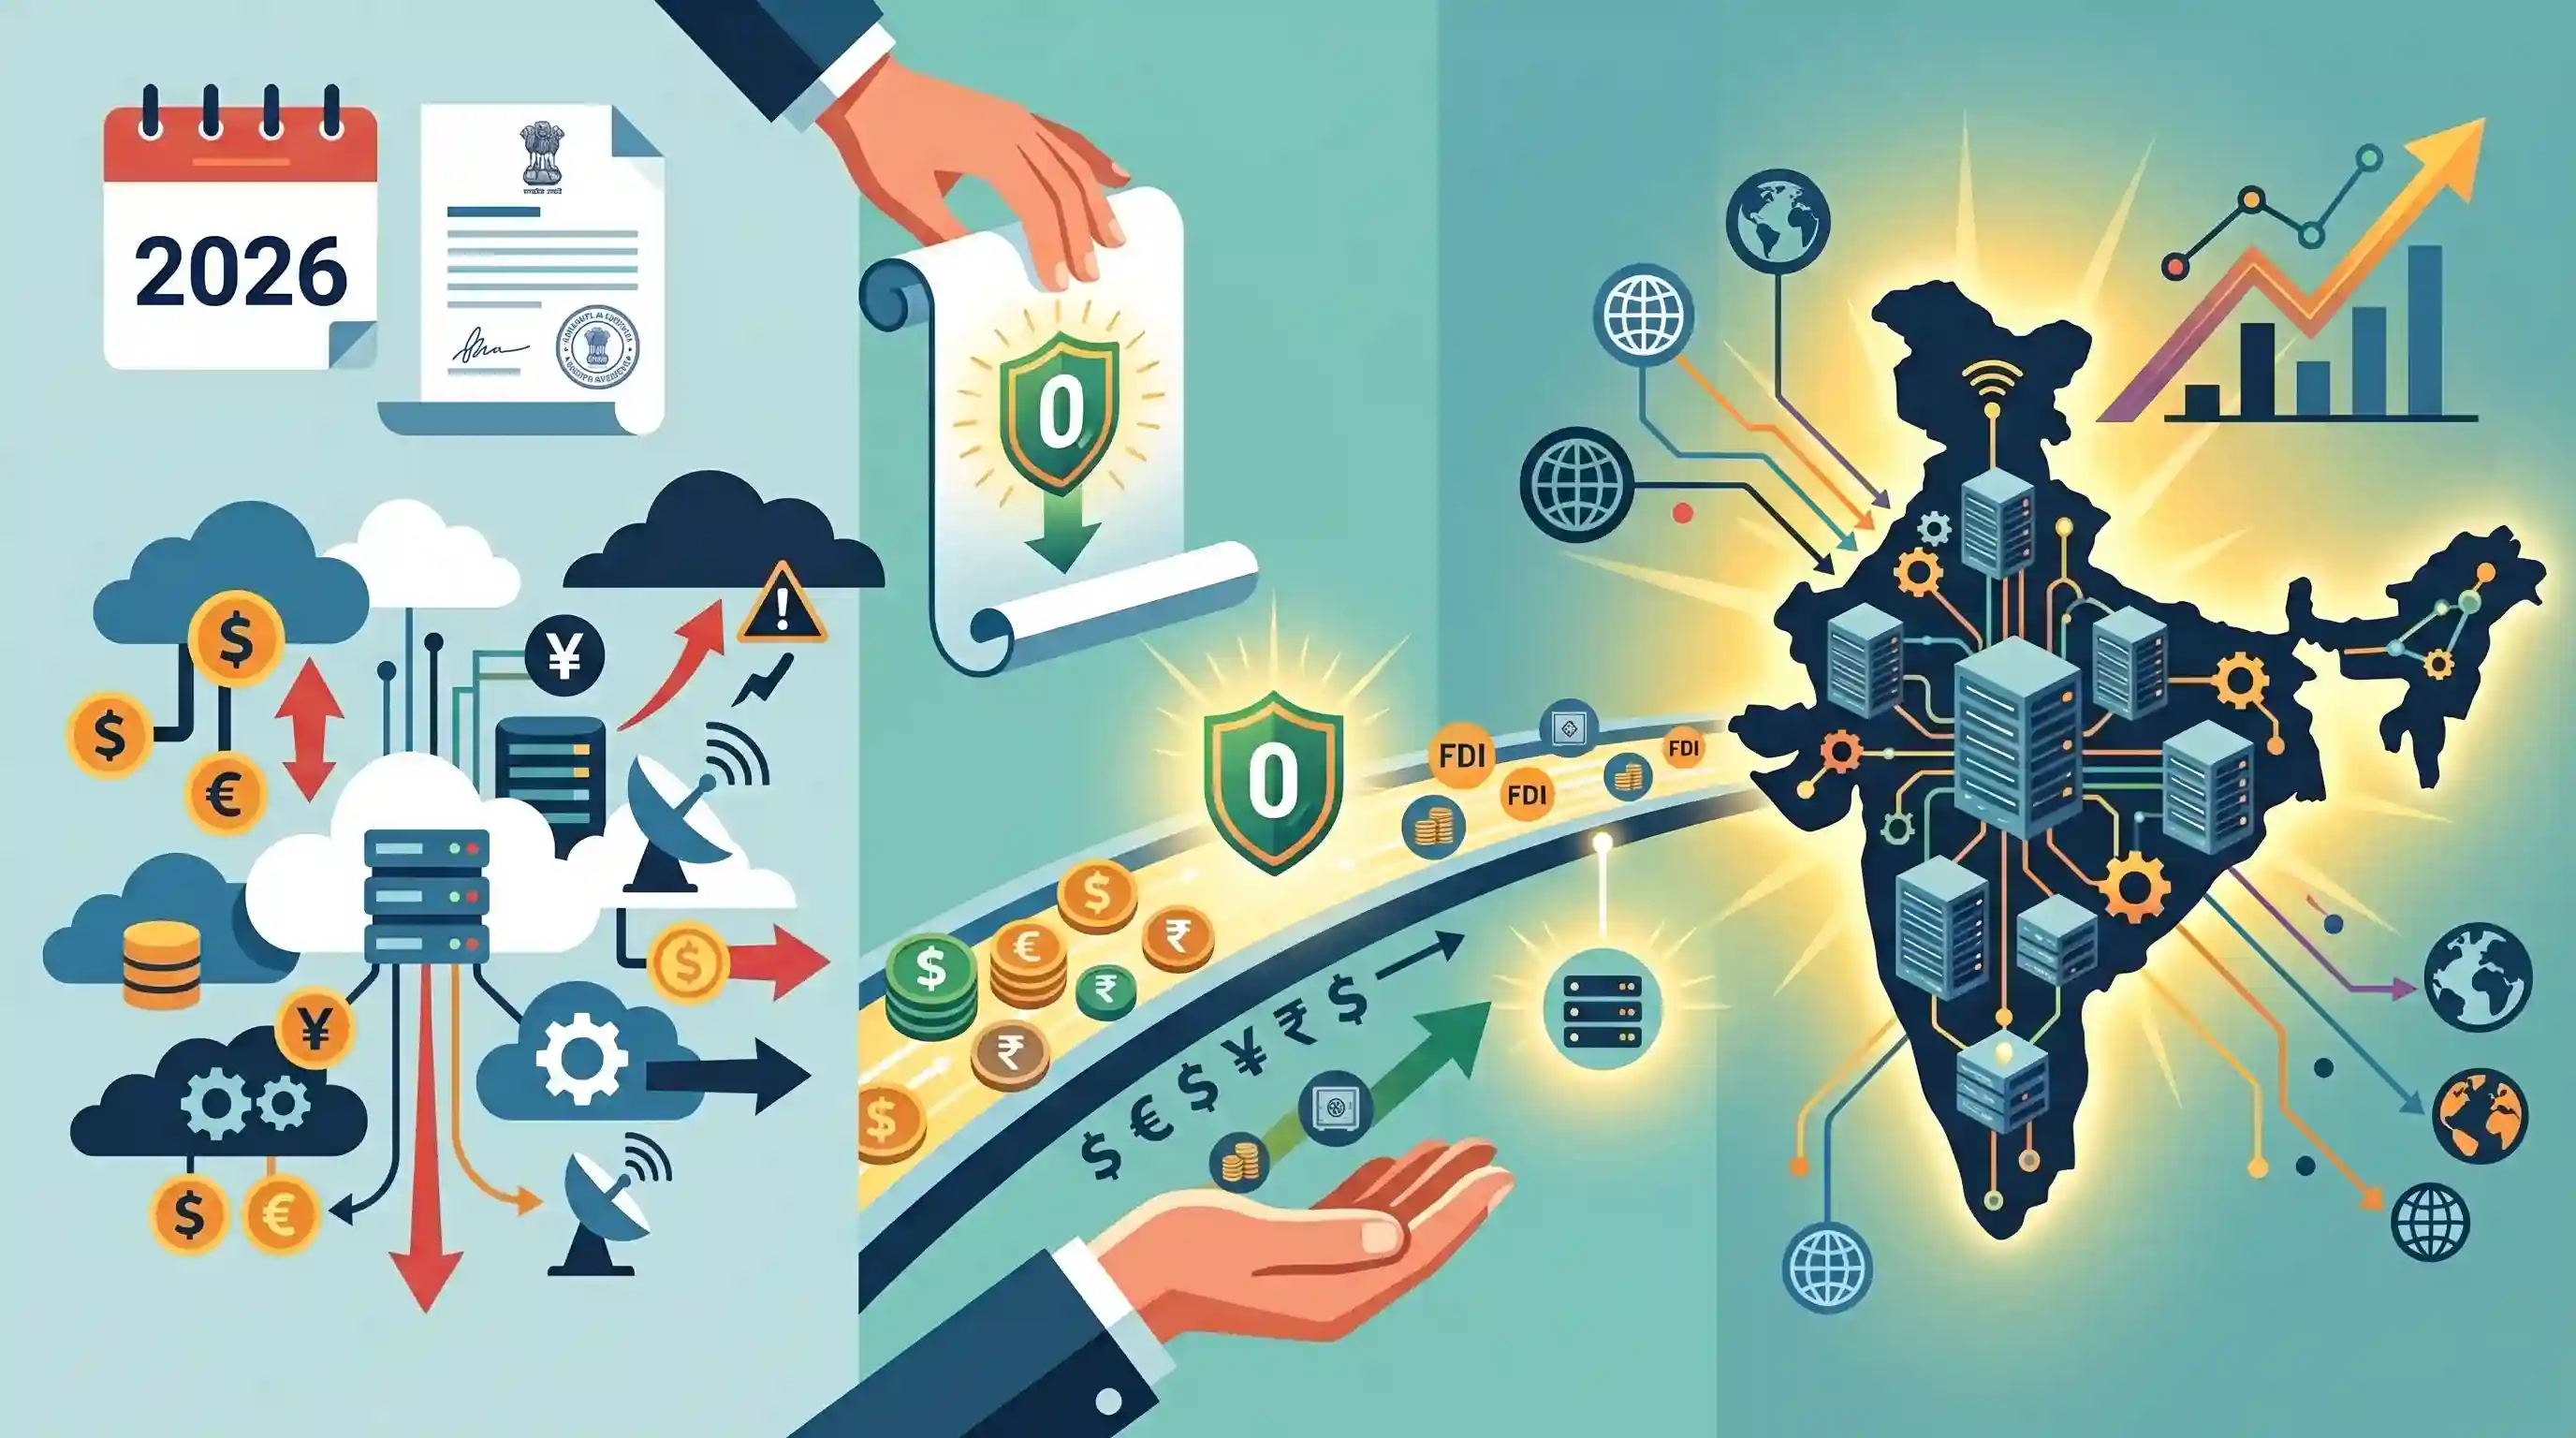
The Union Budget 2026 has proposed a tax exemption for global cloud companies and tech giants that use data centres in India. This significant policy measure aims to reduce operational costs for foreign service providers and incentivize local data hosting. By offering a "tax-free ride," the government seeks to attract substantial foreign investments, expand the domestic digital infrastructure, and position India as a leading global hub for data centres and cloud computing.
Key Points
- The Union Budget 2026 proposes tax exemptions for foreign cloud companies and tech giants utilizing data centres located in India.
- The tax relief is designed to lower operational costs for global cloud service providers, encouraging them to host and process data locally.
- The move supports India's strategic goal of becoming a prominent global hub for data centres and digital infrastructure.
- The policy is expected to drive foreign direct investment (FDI) into the technology sector and bolster cloud computing infrastructure in the country.
Important Terms
Union Budget

The annual financial statement (Article 112) of the Indian government's receipts and expenditure. Budget 2026 introduced long-term tax incentives for the digital economy to attract global cloud hyperscalers.
UPSC context
GS Paper III (Government Budgeting); tests understanding of fiscal policy and resource allocation for strategic growth sectors.
Data Centre
A centralized facility housing IT infrastructure like servers and storage to process data. In India, facilities with over 5MW capacity have 'Infrastructure Status,' facilitating easier access to credit and low-cost financing.
UPSC context
GS Paper III (Infrastructure); crucial for data sovereignty, the DPDP Act 2023, and the Digital India mission.
Cloud Computing
On-demand delivery of IT resources (servers, storage, etc.) over the internet. India utilizes cloud technology through the 'MeghRaj' initiative to expand e-governance and ensure efficient public service delivery.
UPSC context
GS Paper III (Science & Technology); relevant for understanding emerging tech and digital governance frameworks.
Tax Holiday
A temporary reduction or elimination of taxes for a specific sector to encourage investment. Budget 2026 proposed a tax holiday until 2047 for global cloud firms utilizing Indian data centres.
UPSC context
GS Paper III (Indian Economy); tests knowledge of fiscal incentives used to attract global capital and boost capacity.
Safe Harbor
A legal provision that reduces taxpayer risk by providing a fixed profit markup (e.g., 15%) for transactions between related global entities, thereby minimizing transfer pricing disputes and audits.
UPSC context
GS Paper III (Economy/Taxation); relevant for 'Ease of Doing Business' and multinational corporate taxation.
Digital Infrastructure
Foundational technology components—including high-speed internet, data centres, and digital public platforms (DPI)—that enable digital services. It is essential for inclusive development and India's global AI ambitions.
UPSC context
GS Paper III (Infrastructure); essential for inclusive development, Smart Cities, and India's transformation into a digital hub.
Foreign Direct Investment (FDI)
Investment made by a foreign entity into a domestic company or sector to gain a lasting interest. It is a critical driver for financing capital-intensive digital and AI infrastructure projects.
UPSC context
GS Paper III (Investment Models); central to India's balance of payments and financing of large-scale projects.
Prelims Trap
"Data centres were first granted 'Infrastructure Status' in Budget 2026 to attract foreign cloud companies."
Trap! Infrastructure status was already granted to data centres in 2022. Budget 2026 specifically introduces tax exemptions to bypass 'Permanent Establishment' hurdles for foreign companies.
Static Concepts Connected
What is 'Permanent Establishment' (PE) in international taxation?
- Definition: A fixed place of business (like an office or server) through which a foreign enterprise operates, making it liable for corporate taxes in the host country.
- Digital Dilemma: Digital companies often operate without physical presence. However, maintaining servers or data centres locally can trigger PE status, leading to tax liabilities.
- BEPS Framework: The OECD's Base Erosion and Profit Shifting (BEPS) framework seeks to modernize PE definitions to tax digital mega-corporations fairly where value is created.
What are the benefits of granting a sector 'Infrastructure Status'?
- Credit Access: Enables the sector to access long-term financing from banks and dedicated institutions at concessional interest rates.
- ECB Limits: Allows easier access to External Commercial Borrowings (ECBs), helping companies raise funds from foreign markets at lower costs.
- FDI Attraction: Signals high government prioritization, which boosts investor confidence and helps attract 100% automatic route Foreign Direct Investment (FDI).
Cross-Topic Patterns
Data Localization + Tax Incentives
The DPDP Act 2023 necessitates data localization for sensitive data. Budget 2026's tax exemptions ensure that sufficient domestic data center infrastructure exists to meet this statutory demand without inflating costs.
Sovereign AI Compute + Cloud Infrastructure
The India AI Mission's goal of establishing a 10,000 GPU sovereign compute capacity synergizes with attracting foreign mega-data centres, ensuring foundational hardware for local AI models.

Expect a multi-statement question linking Permanent Establishment (PE) taxation, OECD's Pillar One, and DPDP Act localization mandates.
Linked PYQs · 2
Linked PYQs · 2
- 2015MainsGS3
Discuss the advantages and security implications of cloud hosting of servers vis-a-vis in-house machine-based hosting for government businesses.
- 2018MainsGS3
Comment on the important changes introduced in respect of the Long-term Capital Gains Tax (LCGT) and Dividend Distribution Tax (DDT) in the Union Budget for 2018-2019.
