Bihar Financial Inclusion Progress and RuPay Card Usage
Source:The Hindu ↗
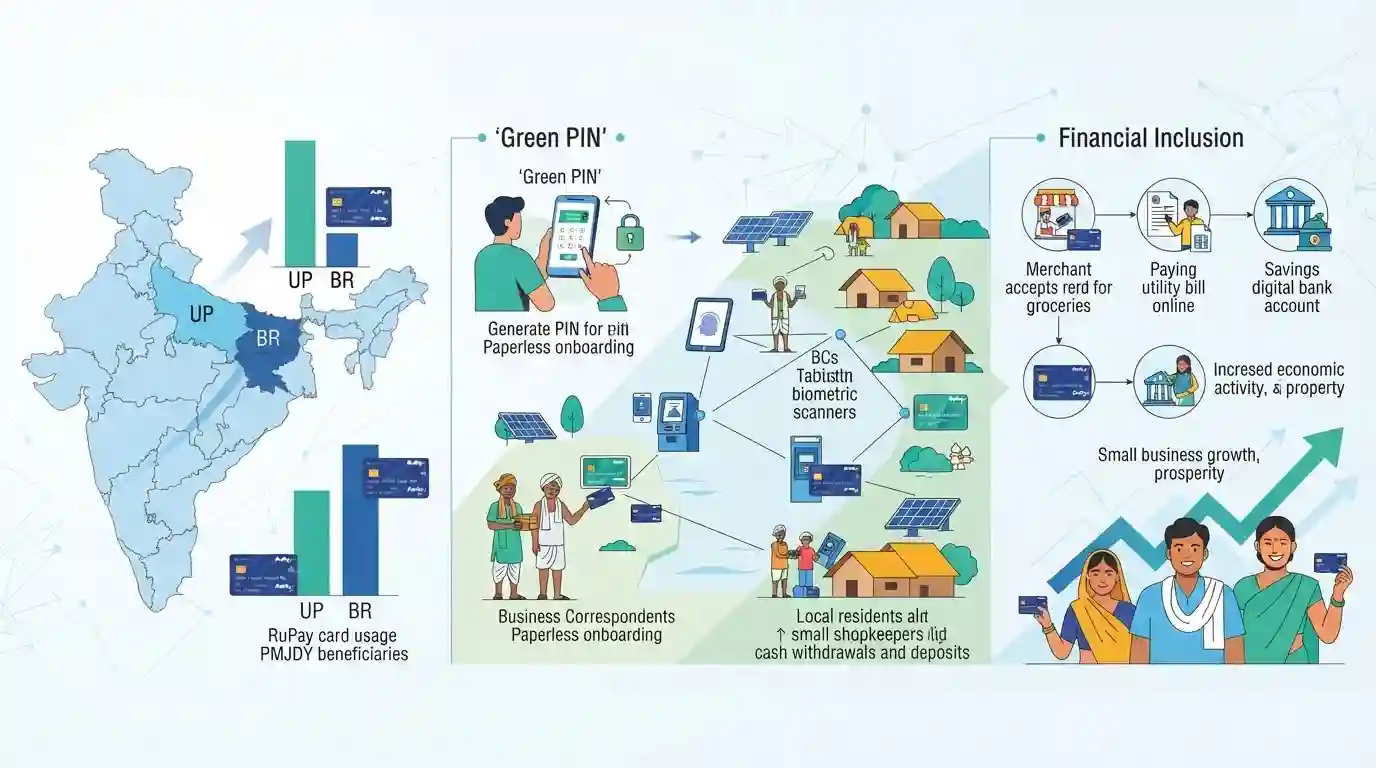
কেন এটি গুরুত্বপূর্ণ
Demonstrates the practical impact of PMJDY, RuPay, and Business Correspondents in achieving last-mile financial inclusion. It serves as a vital case study for evaluating the success of digital banking adoption and inclusive growth strategies in rural India.
সারসংক্ষেপ
Bihar has emerged as the second-highest state in RuPay card usage among Pradhan Mantri Jan Dhan Yojana (PMJDY) beneficiaries, following Uttar Pradesh. The surge in active card usage is largely driven by the 'Green PIN' feature and the deployment of micro-ATMs through the Business Correspondent (BC) network, which have facilitated paperless onboarding and expanded banking access in rural and remote areas.
মূল বিষয়
- Bihar ranks second nationally with 4.98 crore RuPay cardholders under PMJDY, trailing only Uttar Pradesh (7.16 crore).
- India has a total of 58.06 crore Jan Dhan accounts and 40.6 crore RuPay cardholders, reflecting deep penetration of formal banking.
- The 'Green PIN' feature enables instant, paperless PIN generation, overcoming the logistical hurdles of physical PIN mailers in rural areas.
- The extensive deployment of micro-ATMs via the Business Correspondent (BC) network has allowed rural populations to easily access banking services and government benefits.
- Total deposits in Bihar's 6.87 crore Jan Dhan accounts stand at approximately ₹30,000 crore, indicating active utilization rather than just dormant account opening.
গুরুত্বপূর্ণ শব্দ
Pradhan Mantri Jan Dhan Yojana (PMJDY)

A national financial inclusion mission launched in 2014 to ensure affordable access to financial services like basic savings accounts, remittance, credit, insurance, and pensions for every unbanked adult.
UPSC context
GS Paper III (Inclusive Growth); vital for questions on financial literacy, poverty reduction, and direct benefit transfer (DBT).
RuPay
An indigenously developed card payment system launched by the National Payments Corporation of India (NPCI) in 2012, offering low-cost debit, credit, and prepaid card alternatives.
UPSC context
GS Paper III (Banking & Tech); tested in prelims regarding India's domestic payments and digital infrastructure.
Business Correspondent (BC) network
A system of bank-authorized local agents who act as intermediaries to deliver basic banking and digital financial services in unbanked or remote rural areas.
UPSC context
GS Paper III (Inclusive Growth); crucial for analyzing rural banking, last-mile DBT distribution, and technology-driven development.
প্রিলিমস ফাঁদ
The ₹10,000 overdraft facility under PMJDY is an unconditional entitlement for all active account holders aged 18 to 65.
The overdraft is limited to only one member per household (preferably the female head) and is conditional upon 6 months of satisfactory account conduct for amounts exceeding ₹2,000.
সংযুক্ত স্থির ধারণা
What is the Business Correspondent (BC) model, and who can act as one?
- Definition: They are retail agents engaged by banks to provide basic banking services in remote, branchless areas.
- Eligible Entities: Includes retired teachers, ex-servicemen, individual Kirana/medical store owners, Self-Help Groups (SHGs), and NGOs.
- Key Functions: Enables cash deposits, withdrawals, small-value remittances, and paperless onboarding via e-KYC.
What is the RBI's composite Financial Inclusion Index (FI-Index)?
- Definition: A single value ranging from 0 to 100, designed to capture the extent of financial inclusion across the country.
- No Base Year: Uniquely, the index is built from scratch without any base year, reflecting cumulative historical achievements.
- Three Pillars: Comprises three weighted parameters: Access (35%), Usage (45%), and Quality (20%).
আন্তঃবিষয় প্যাটার্ন
Financial Inclusion + Gender Empowerment
PMJDY's female-first overdraft priority, paired with local BC networks, acts as a primary institutional catalyst for rural women-led micro-enterprises and Self-Help Group (SHG) credit integration.
JAM Trinity + Fiscal Leakage Mitigation
The transition to micro-ATMs and Green PINs reduces last-mile transaction costs, directly curbing administrative leakages in MGNREGS and PM-KISAN welfare payouts.

PMJDY's structural changes (age limits, OD parameters) combined with RBI's FI-Index weightages will likely feature in Prelims 2026.
সংযুক্ত PYQ · 5
সংযুক্ত PYQ · 5
- 2024PrelimsGS1
With reference to the Pradhan Mantri Jan Dhan Yojana (PMJDY), which of the following statements is/are correct? 1. The scheme aims to open bank accounts for unbanked households. 2. There is a minimum balance requirement for accounts opened under this scheme. 3. Beneficiaries get a Rupay Debit Card with an inbuilt accident insurance cover. Select the correct answer using the code given below.
- 2015PrelimsGS1
'Pradhan Mantri Jan-Dhan Yojana' has been launched for
- 2026PrelimsGS1
Which one of the following correctly represents the three key sub-indices of the Financial Inclusion Index (FI-Index) of the Reserve Bank of India (RBI) ?
- 2016MainsGS3
Pradhan Mantri Jan-Dhan Yojana (PMJDY) is necessary for bringing unbanked to the institutional finance fold. Do you agree with this for financial inclusion of the poorer section of the Indian society? Give arguments to justify your opinion.
- 2022MainsGS3
Is inclusive growth possible under market economy ? State the significance of financial inclusion in achieving economic growth in India.
