Fitch Highlights Need for Improved Bank Deposit Mobilisation
Source:The Hindu ↗
Why It Matters
This article provides crucial data points on the transmission of RBI's monetary policy (repo rate cuts) to bank credit growth and deposit rates. It illustrates the operational challenges banks face (managing the Loan-to-Deposit Ratio and Net Interest Margins) and highlights a significant shift in the banking landscape where Public Sector Banks are currently outpacing private banks in credit growth, all of which are highly relevant for GS3 Economy and Prelims.
Summary
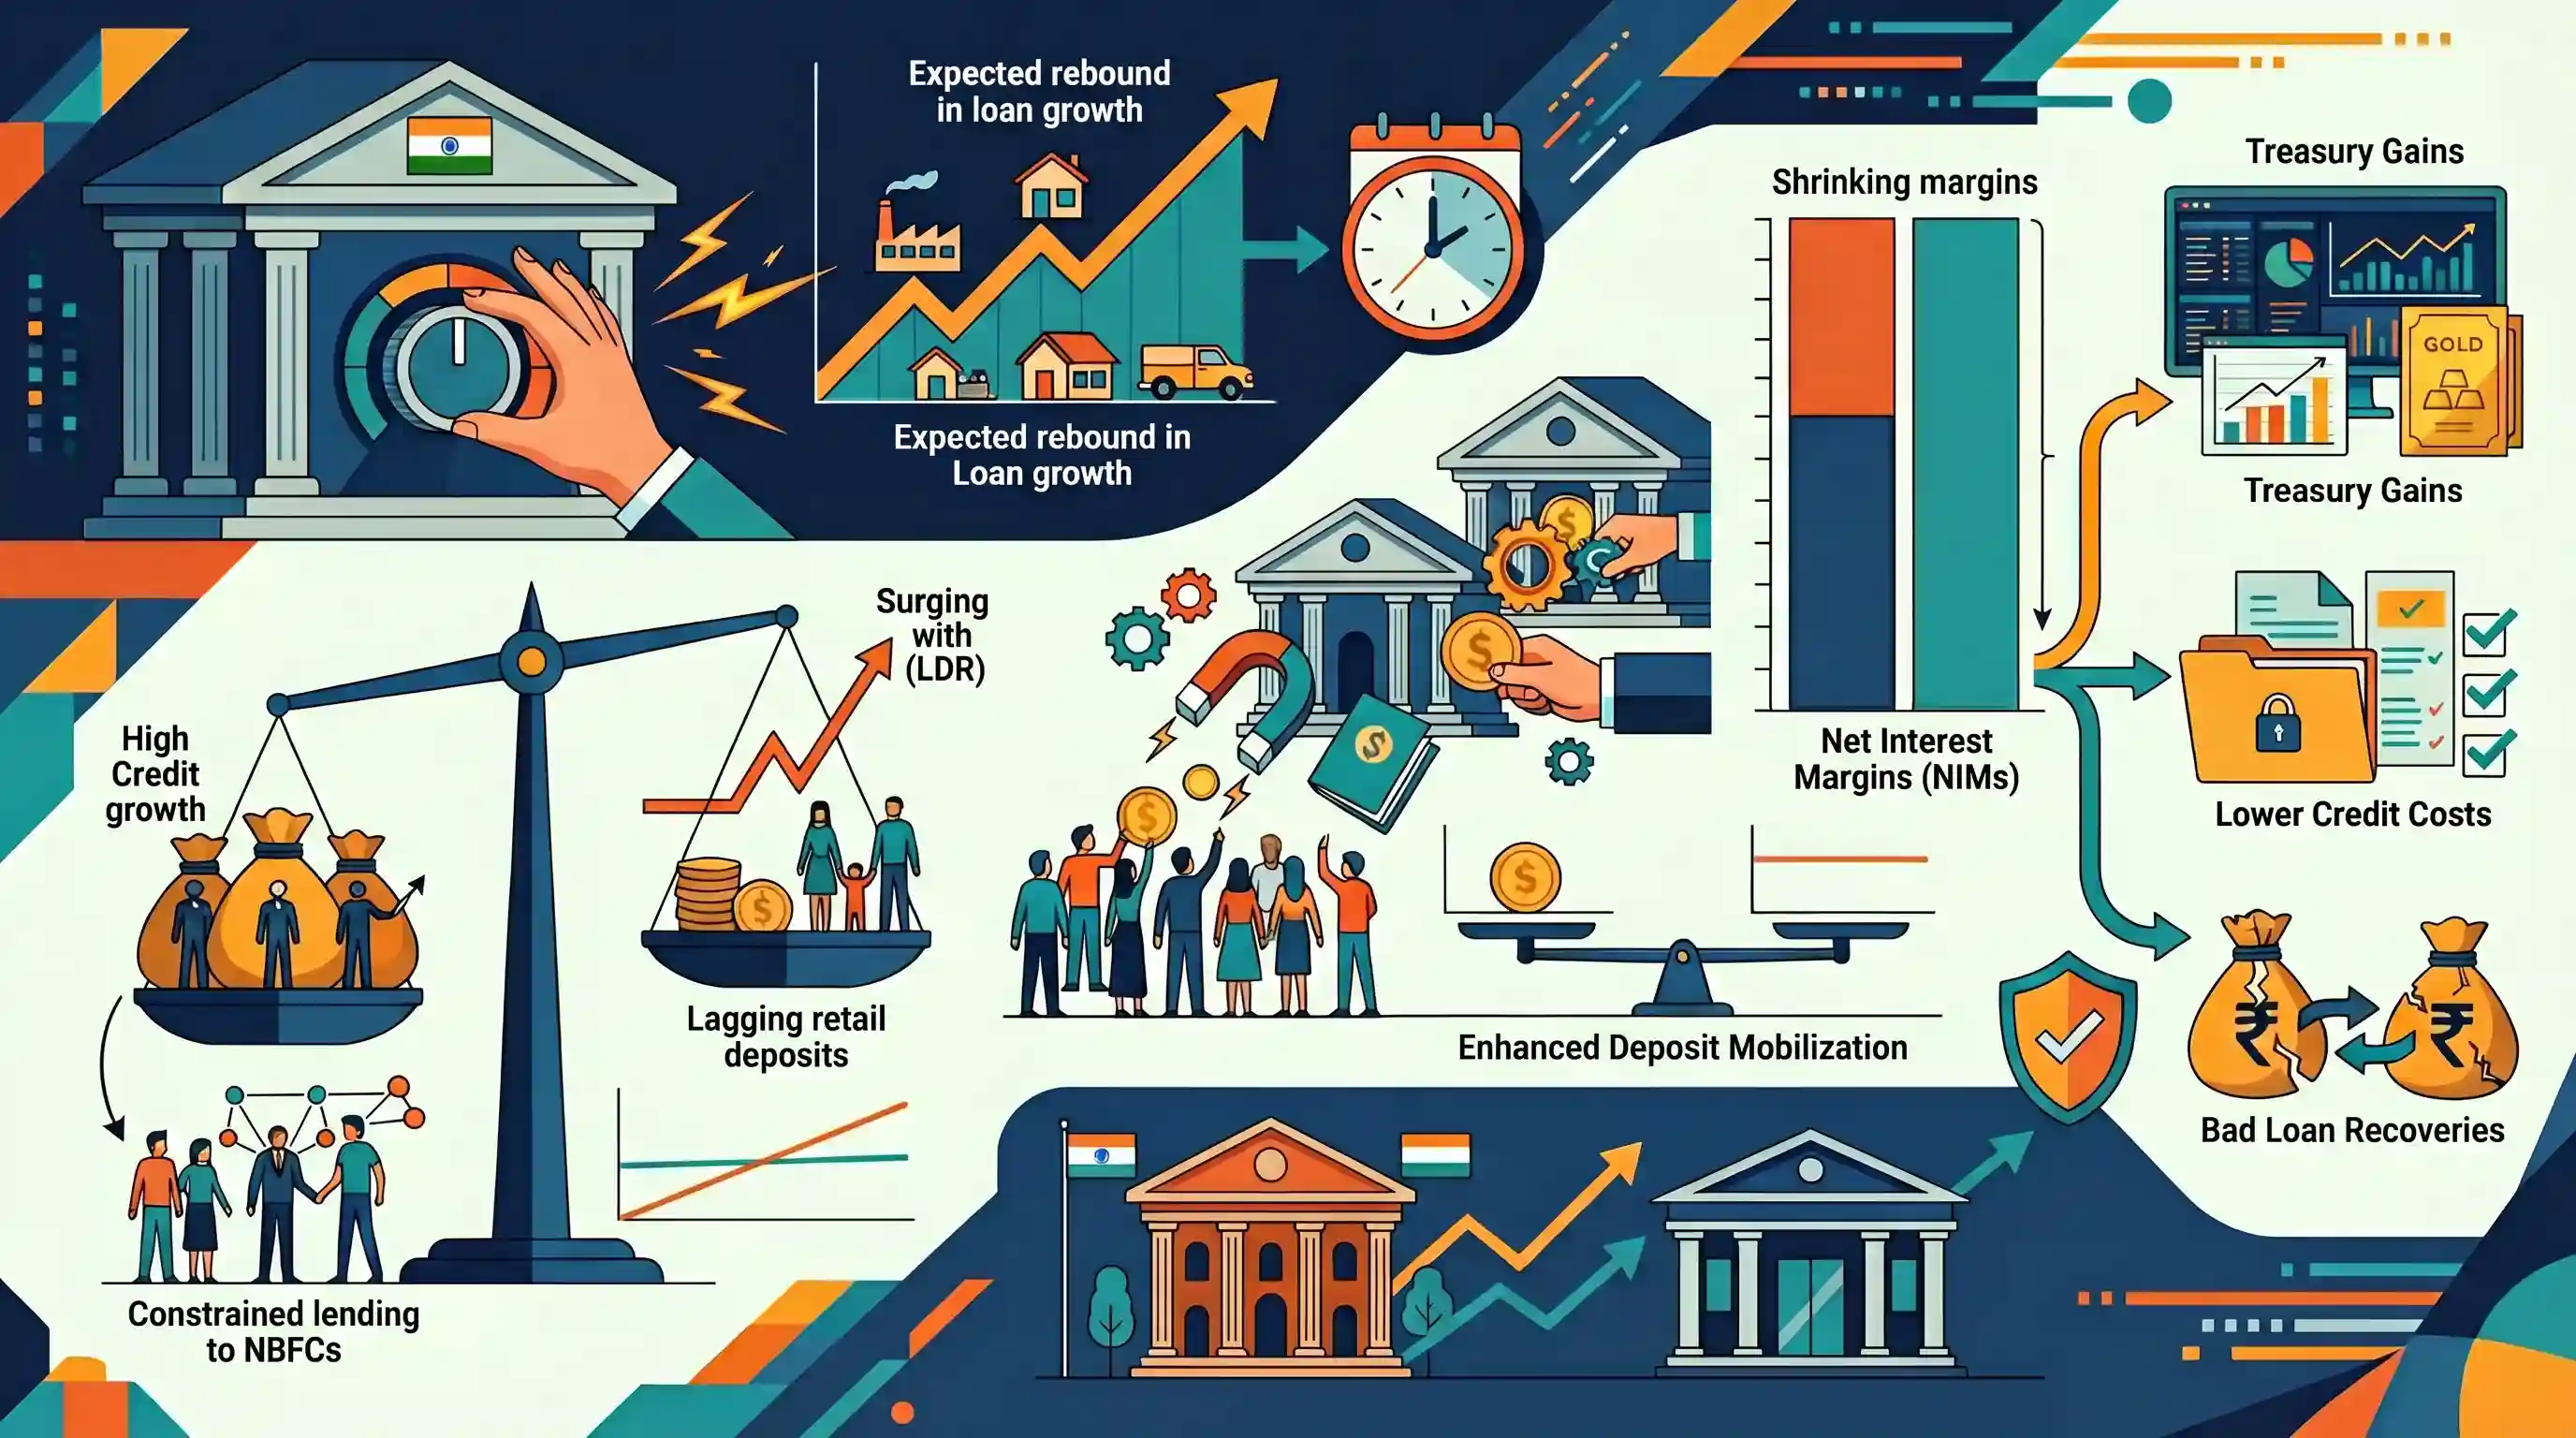
According to Fitch Ratings, Indian banks will likely need to enhance their deposit mobilisation efforts to keep their Loan-to-Deposit Ratios (LDR) stable, as loan growth is expected to rebound to 12%-13% following a 50 basis point rate cut by the Reserve Bank of India (RBI). In FY25, LDRs surged as retail deposit growth lagged behind credit growth, while overall sectoral loan growth hit a four-year low of 10% due to constrained lending to Non-Banking Financial Companies (NBFCs). Notably, Public Sector Banks lent at a faster rate than their private peers for the first time in nearly a decade. Even as Net Interest Margins shrank due to costlier deposits, banks preserved their earnings through robust treasury gains, lower credit costs, and bad loan recoveries, pointing to a resilient asset quality environment.
Key Points
- Fitch Ratings suggests Indian banks need to improve deposit mobilisation to maintain a buoyant Loan-to-Deposit Ratio (LDR) following the RBI's 50 basis point rate cut.
- The RBI's rate cut is expected to boost loan growth to 12%-13%, but retail deposit growth needs to match this to prevent LDR pressures, which already rose by 120 bps in FY25.
- Overall sectoral loan growth fell to a four-year low of 10%, largely due to a significant reduction in bank lending to NBFCs in response to RBI's regulatory actions.
- For the first time in nearly a decade, Public Sector Banks (PSBs) outpaced private banks in lending growth, expanding credit by 12.4%.
- Despite Net Interest Margins (NIM) dropping by 20 bps due to higher deposit costs, banks maintained earnings through lower credit costs, bad loan recoveries, and treasury gains, signaling strong underlying asset quality.
Important Terms
Loan-to-Deposit Ratio (LDR)

The ratio of a bank's total loans to its total deposits, indicating its liquidity position. A high ratio suggests aggressive lending; a low one implies underutilized resources.
UPSC context
GS-III Economy; tests understanding of banking liquidity, credit-to-deposit balance, and financial stability indicators.
Deposit Mobilisation
The process of attracting and collecting savings from the public into bank accounts. This is essential for capital formation and providing banks with capital to lend.
UPSC context
GS-III Mobilization of Resources; tests concepts of savings-investment channelization and banking resource management.
Non-Banking Financial Companies (NBFCs)
Financial institutions offering bank-like services (loans, investments) without a banking license. They cannot accept demand deposits and are regulated by the RBI's Scale-Based Regulation (SBR) framework.
UPSC context
GS-III Economy/Banking; tests knowledge of shadow banking and regulatory frameworks like Scale-Based Regulation (SBR).
Net Interest Margin (NIM)
A profitability metric measuring the difference between interest income earned from loans and interest paid to depositors, expressed as a percentage of interest-earning assets.
UPSC context
GS-III Economy; evaluates knowledge of banking profitability and the impact of interest rate cycles.
Reserve Bank of India (RBI)
India's central bank and regulatory body. It manages monetary policy, supervises banks/NBFCs, and maintains price stability through tools like the repo rate.
UPSC context
GS-III Monetary Policy; tests central bank functions, inflation targeting, and regulatory roles.
Public Sector Banks (PSBs)
Banks where the Central or State governments hold a majority stake (>50%). They are key to financial inclusion and executing government credit-led development schemes.
UPSC context
GS-III Banking; covers bank recapitalization, sectoral credit trends, and public-private banking distinctions.
Repo Rate
The rate at which the RBI lends money to commercial banks against government securities. It is the primary tool for controlling inflation and market liquidity.
UPSC context
GS-III Monetary Policy; core tool for managing money supply and inflation targeting (4% +/- 2%).
Prelims Trap
"Private sector banks have continuously outpaced Public Sector Banks in lending growth over the last decade."
PSBs actually outpaced private banks in credit expansion in FY25 for the first time in nearly a decade, breaking the historical trend.
Static Concepts Connected
What is the Loan-to-Deposit Ratio (LDR) and its significance?
- Definition: It measures the proportion of a bank's total customer deposits that have been utilized for lending.
- Liquidity indicator: A persistently high LDR signals aggressive lending, heightening liquidity stress and reducing a bank's ability to absorb sudden economic shocks.
- Reserve constraints: Because of mandatory reserve requirements (CRR/SLR), an excessively high LDR implies banks are relying on costlier wholesale funding to finance credit.
How does the RBI use 'risk weights' to control sectoral credit growth?
- Capital adequacy: Higher risk weights force banks to set aside a larger chunk of their own capital as a buffer for specific, riskier loan categories.
- Targeted tightening: RBI hiked risk weights on bank loans to NBFCs, effectively making such lending costlier for banks without having to hike the overarching benchmark repo rate.
Cross-Topic Patterns
Deposit lag vs Monetary Transmission
Sluggish deposit mobilization forces banks to keep deposit rates elevated to attract funds, structurally impeding the downward transmission of RBI's repo rate cuts to retail lending rates.
Shadow Banking and systemic risks
RBI's macroprudential curbs on bank lending to NBFCs highlight the interconnectedness of India's financial system, aiming to prevent spillover risks from shadow banks to scheduled commercial banks.

Expect a multi-statement Prelims question linking high Loan-to-Deposit Ratios (LDR), NBFC risk weights, and monetary transmission.
Linked PYQs · 3
Linked PYQs · 3
- 2020PrelimsGS1
If the RBI decides to adopt an expansionist monetary policy, which of the following would it not do ? 1. Cut and optimize the Statutory Liquidity Ratio 2. Increase the Marginal Standing Facility Rate 3. Cut the Bank Rate and Repo Rate Select the correct answer using the code given below:
- 2015PrelimsGS1
When the Reserve Bank of India reduces the Statutory Liquidity Ratio by 50 basis points, which of the following is likely to happen?
- 2024PrelimsGS1
Consider the following statements : 1. In India, Non-Banking Financial Companies can access the Liquidity Adjustment Facility window of the Reserve Bank of India. 2. In India, Foreign Institutional Investors can hold the Government Securities (G-Secs). 3. In India, Stock Exchanges can offer separate trading platforms for debts. Which of the statements given above is/are correct?
