Tax department cites ineligible claims amid rising refund complaints
Source:Indian Express ↗
Why It Matters
Direct taxation and resource mobilization are critical components of the Indian Economy syllabus. The article highlights practical challenges in tax administration, tax evasion through false claims, and how technology (AIS, e-governance) is being leveraged to enforce compliance and accountability.
Summary
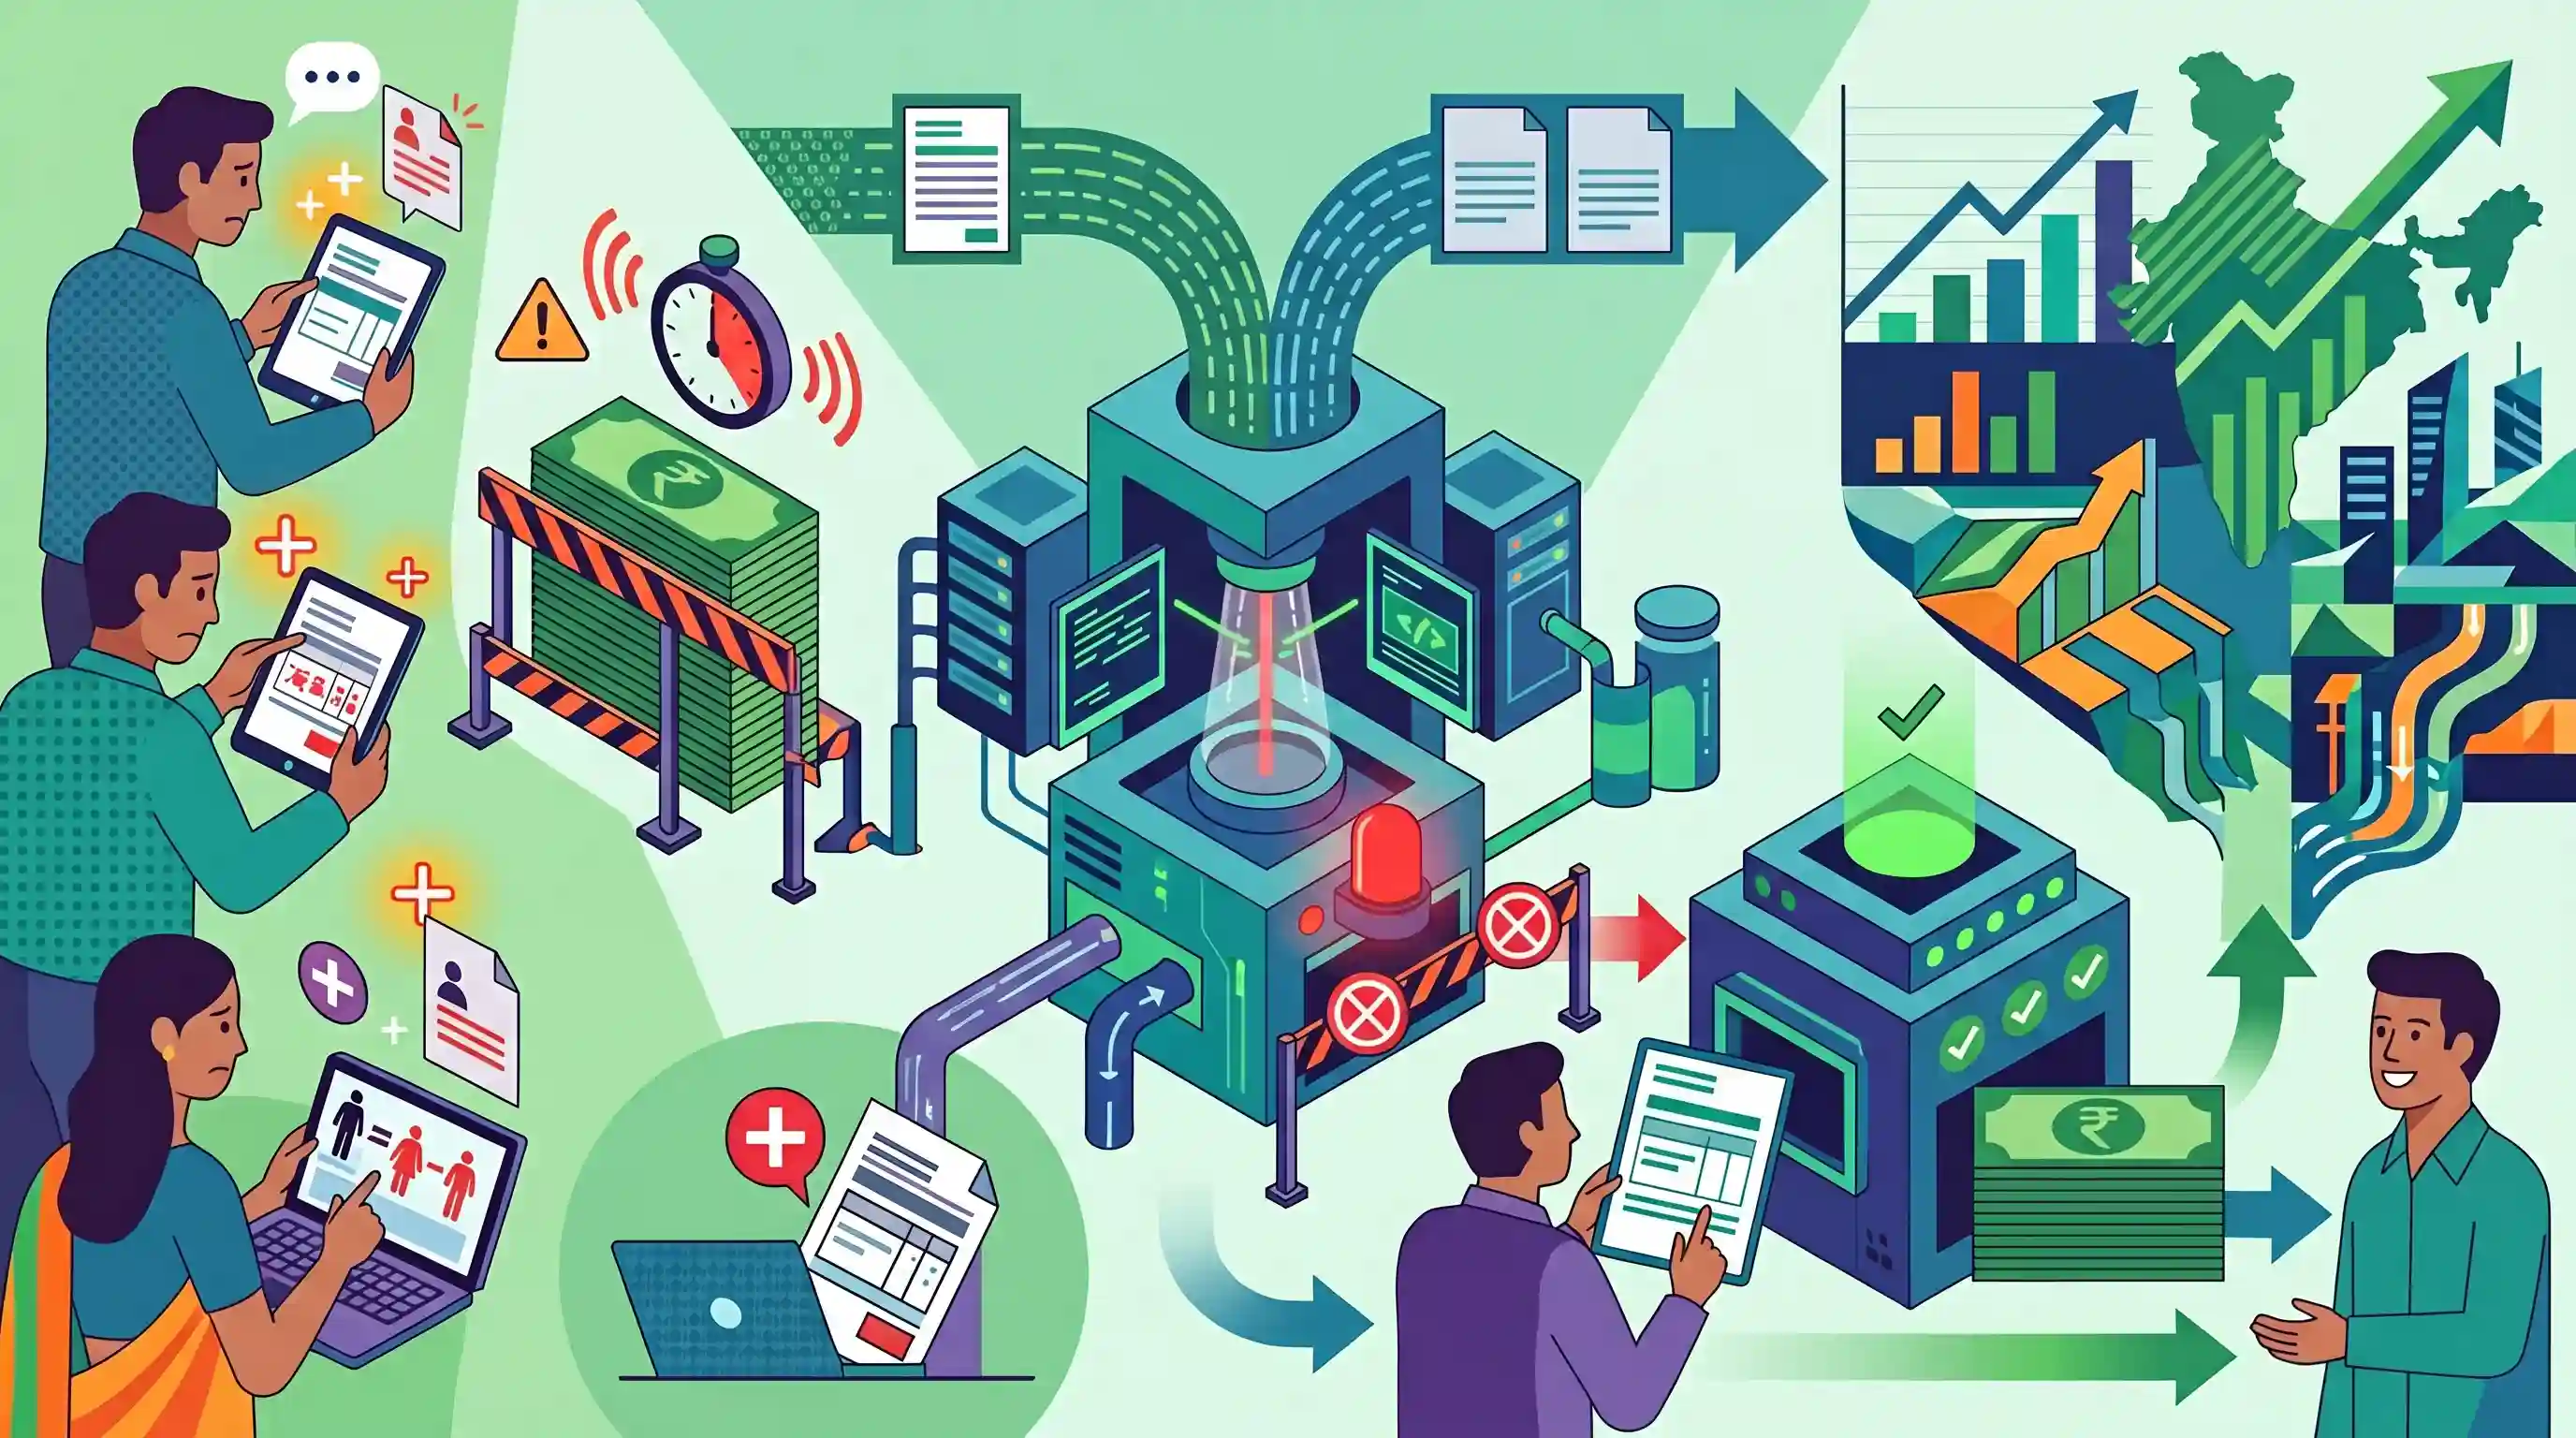
Amid rising complaints of delayed income tax refunds, the Income Tax Department has identified a significant increase in ineligible claims for deductions and exemptions as the primary cause. Automated tax systems now cross-verify taxpayer declarations with the Annual Information Statement (AIS) and Form 26AS, stalling refunds when discrepancies arise. To resolve these issues, the department has urged taxpayers to file revised Income Tax Returns (ITRs) to correct unjustified claims. This development highlights the challenges in tax compliance and the increasing role of digital data verification in modernizing India's tax administration.
Key Points
- The Income Tax Department is facing numerous complaints regarding delayed tax refunds.
- The delays are primarily attributed to a high number of ineligible or unjustified claims for deductions and exemptions filed by taxpayers.
- Automated refund systems halt processing when they detect discrepancies between the tax returns and official records like the Annual Information Statement (AIS) and Form 26AS.
- The department has urged affected taxpayers to file revised Income Tax Returns (ITRs) to correct these discrepancies and enable the release of their refunds.
Important Terms
Central Board of Direct Taxes (CBDT)

The statutory apex body under the Ministry of Finance responsible for formulating direct tax policies and overseeing the Income Tax Department.
UPSC context
GS Paper II (Statutory Bodies) & GS Paper III (Economy/Taxation); tests knowledge of administrative structures in resource mobilization.
Annual Information Statement (AIS)
A comprehensive digital statement available to taxpayers that summarizes all financial transactions linked to their PAN, such as interest, dividends, and stock market trades.
UPSC context
GS Paper III (Taxation) & GS Paper II (E-governance); focuses on transparency and digital transformation in tax administration.
Form 26AS
A consolidated annual tax credit statement that reflects details of tax deducted at source (TDS), tax collected at source (TCS), and self-assessment tax paid.
UPSC context
GS Paper III (Indian Economy); relevant for understanding tax compliance mechanisms and individual financial documentation.
Revised Return (Section 139(5))
A provision under the Income Tax Act allowing taxpayers to fix errors, omissions, or wrong statements in their original return before the assessment is completed.
UPSC context
GS Paper III (Tax Administration); tests awareness of legal recourses available to taxpayers to maintain compliance.
Income Tax Act, 1961
The primary law in India governing the calculation, levy, collection, and recovery of income tax for individuals, firms, and companies.
UPSC context
GS Paper III (Indian Economy/Fiscal Policy); foundational knowledge for questions on direct tax reforms and legislation.
Income Tax Department
The executive arm of the CBDT responsible for enforcing direct tax laws and facilitating revenue collection for the Central Government.
UPSC context
GS Paper III (Economic Development/Resource Mobilization); tests understanding of government machinery in fiscal management.
Prelims Trap
"The Annual Information Statement (AIS) exclusively reflects Tax Deducted at Source (TDS) and Tax Collected at Source (TCS) records of a taxpayer."
AIS is far more comprehensive than the older Form 26AS. It includes interest, dividends, mutual fund transactions, and foreign remittances, acting as a complete financial profile rather than just a TDS ledger.
Static Concepts Connected
How does 'Project Insight' modernize India's direct tax administration?
- AI and Analytics: Utilizes the Income Tax Transaction Analysis Centre (INTRAC) to analyze data, detect evasion, and automatically flag discrepancies.
- 360-Degree Profiling: Integrates multi-source financial data to build a comprehensive taxpayer profile, vastly expanding upon traditional return filings.
- Behavioral Nudges: Replaces immediate penal action with non-intrusive alerts, encouraging voluntary compliance and self-correction.
What are the statutory provisions for filing a Revised Income Tax Return?
- Section 139(5): Section 139(5) of the Income Tax Act allows taxpayers to rectify omissions or wrong statements in their original return.
- Time Limit: Must be filed before the end of the relevant assessment year or before the completion of the assessment, whichever is earlier.
- No Immediate Penalties: Serves as a voluntary corrective measure to resolve automated discrepancy flags without automatically attracting immediate evasion penalties.
Cross-Topic Patterns
Algorithmic bias in E-Governance
The rigid automated stalling of tax refunds highlights a Mains theme: how back-end data integration and algorithmic governance can override user-centric service delivery, inconveniencing genuine citizens.
Nudge Theory in Tax Administration
The IT department's use of non-intrusive SMS/email alerts to prompt revised returns is a classic application of 'Nudge Theory' (highlighted in Economic Survey 2018-19) to boost voluntary compliance.

Expect a 2026 Prelims statement differentiating AIS from Form 26AS, or a Mains question on the limitations of algorithmic tax governance.
Linked PYQs · 4
Linked PYQs · 4
- 2019MainsGS3
Enumerate the indirect taxes which have been subsumed in the Goods and Services Tax (GST) in India. Also, comment on the revenue implications of the GST introduced in India since July 2017.
- 2025PrelimsGS1
With reference to the Government of India, consider the following information: Organization Some of its functions It works under I. Directorate of Enforcement Enforcement of the Fugitive Economic Offenders Act, 2018 Internal Security Division-I, Ministry of Home Affairs II. Directorate of Revenue Intelligence Enforces the Provisions of the Customs Act, 1962 Department of Revenue, Ministry of Finance III. Directorate General of Systems and Data Management Carrying out big data analytics to assist tax officers for better policy and nabbing tax evaders Department of Revenue, Ministry of Finance In how many of the above rows is the information correctly matched?
- 2024MainsGS2
e-governance is not just about the routine application of digital technology in service delivery process. It is as much about multifarious interactions for ensuring transparency and accountability. In this context evaluate the role of the 'Interactive Service Model' of e-governance.
- 2023MainsGS2
e-governance, as a critical tool of governance, has ushered in effectiveness, transparency and accountability in governments. What inadequacies hamper the enhancement of these features ?
