Insurance Sector FDI Liberalisation and Welfare Economy
Source:The Hindu ↗
Why It Matters
The move to allow 100% FDI in the insurance sector is a landmark reform in India's financial sector. It highlights the ongoing debate between liberalization/privatization and state-controlled welfare economics, particularly regarding the control of national savings and capital formation for domestic growth.
Summary
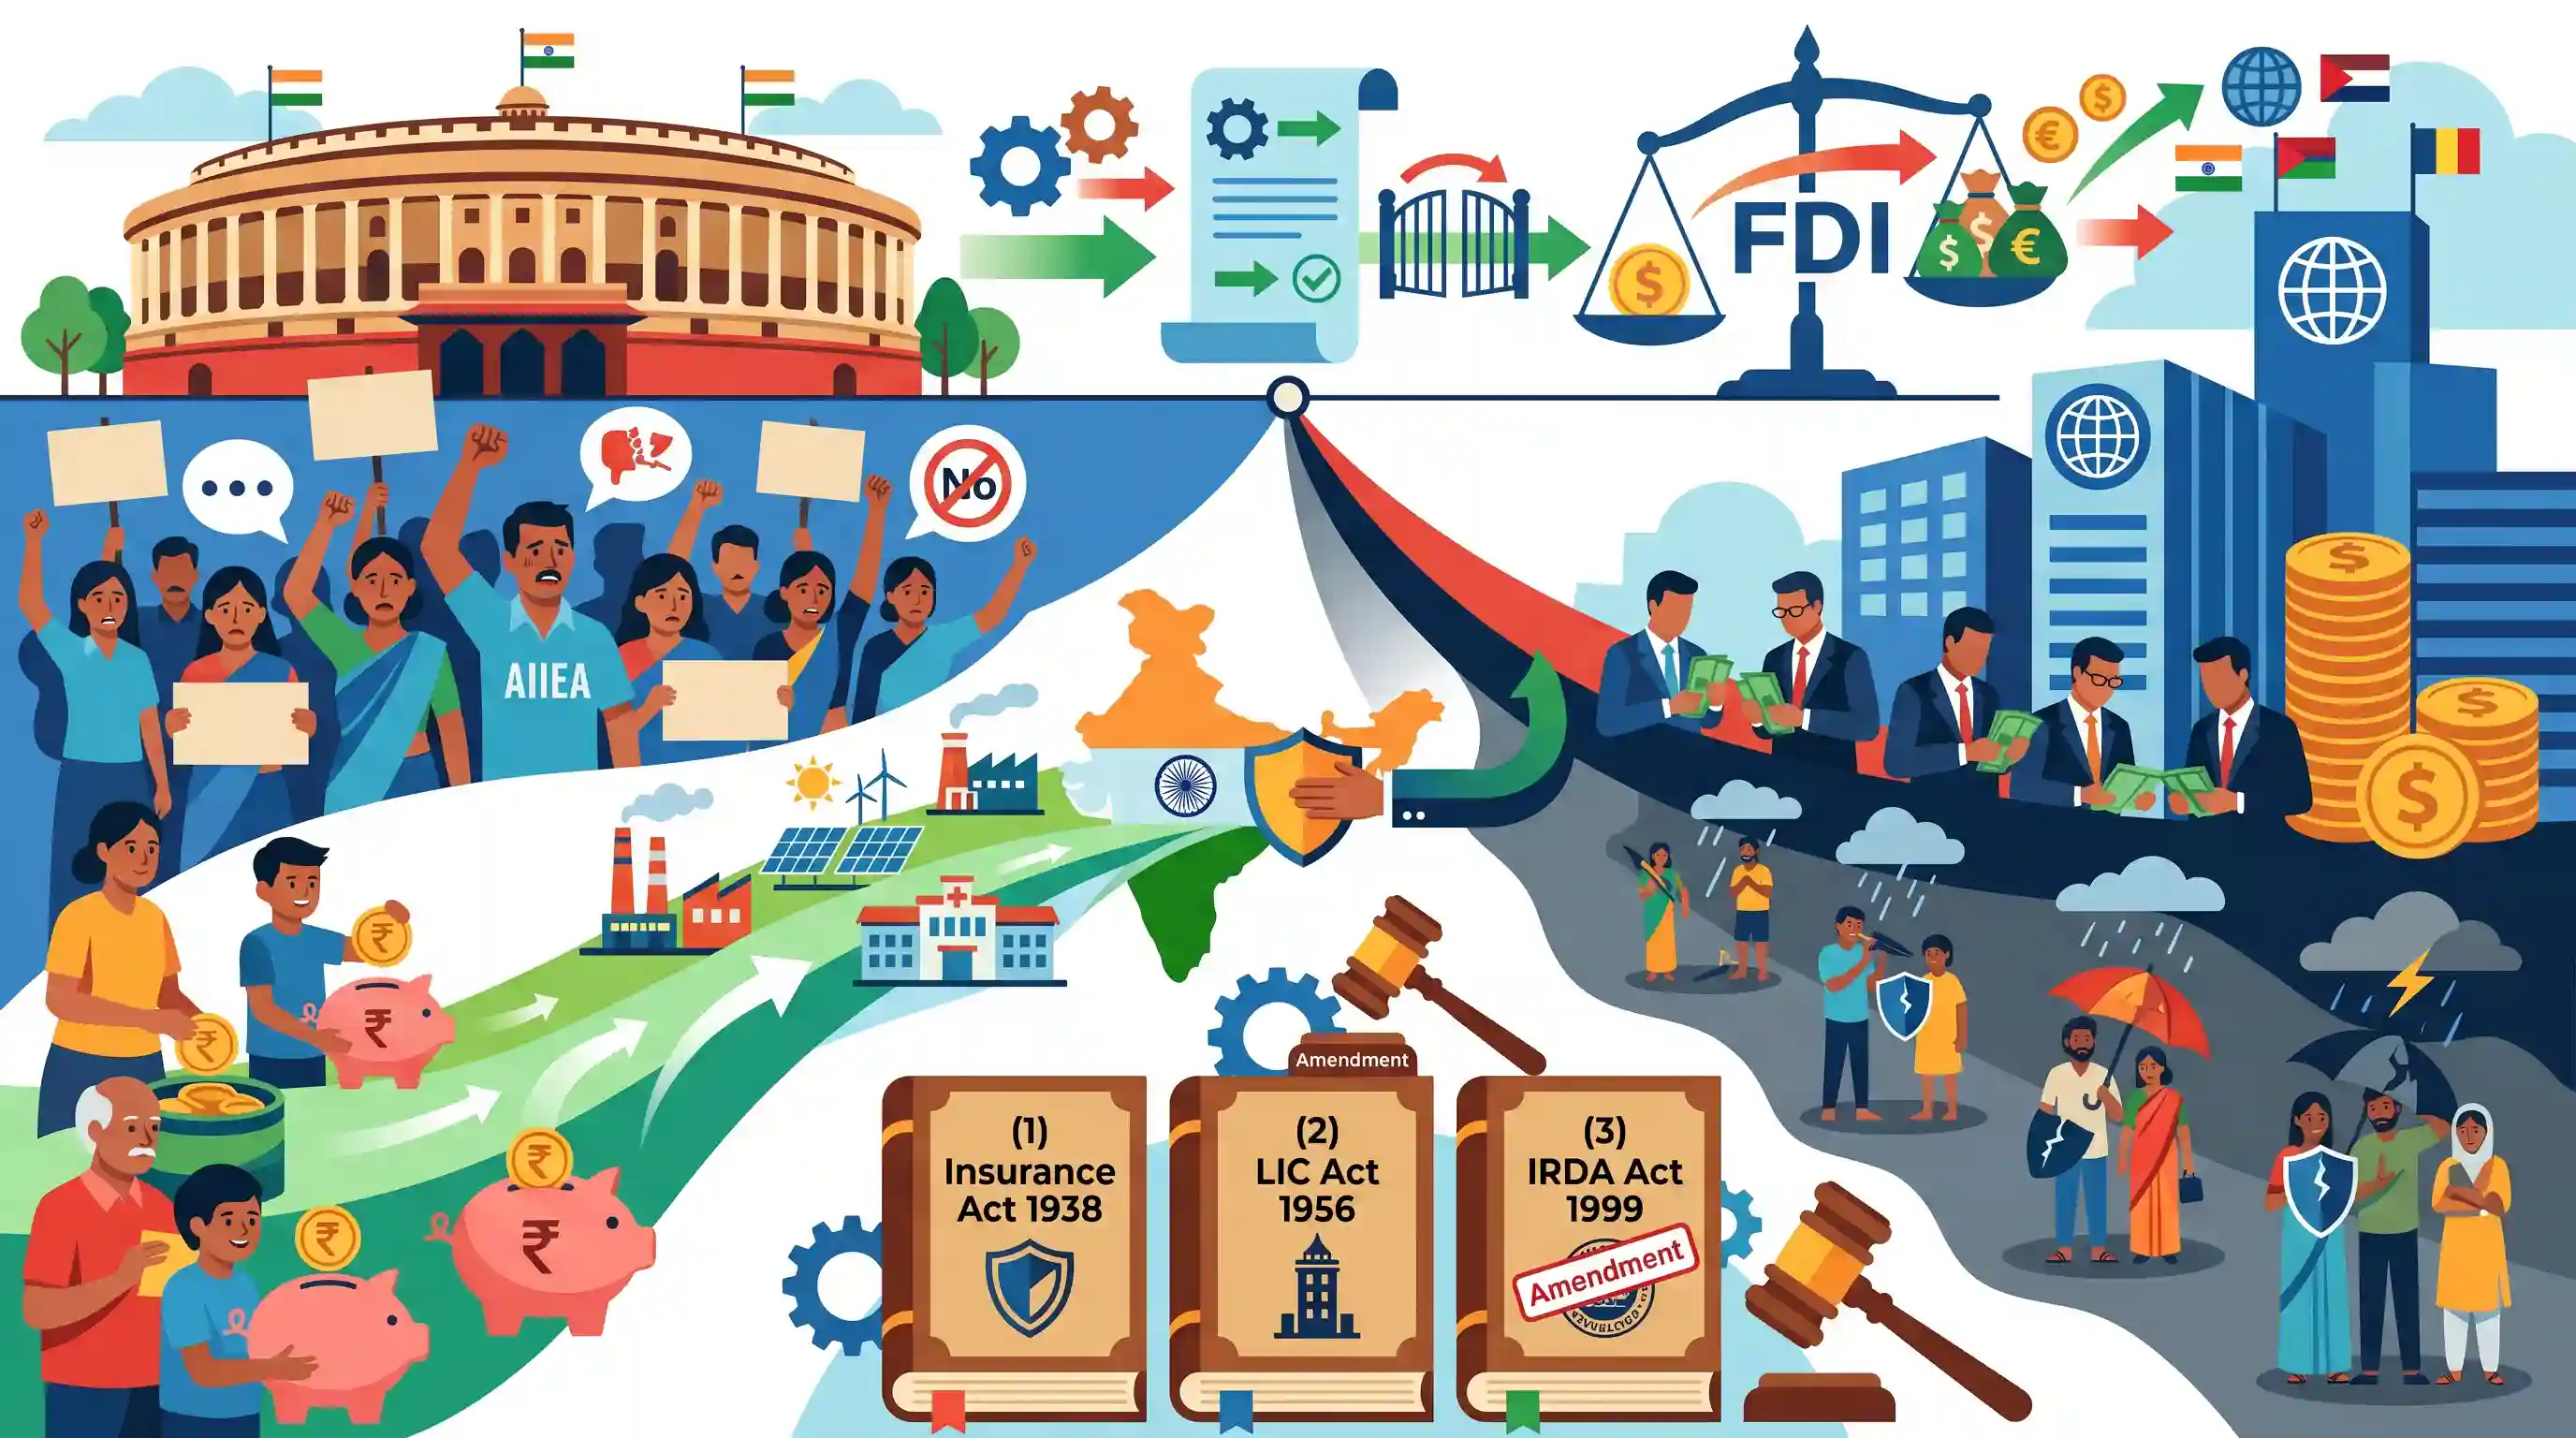
The Central government's recent decision to raise the Foreign Direct Investment (FDI) cap in the insurance sector to 100% via the Insurance Laws (Amendment) Bill has drawn severe criticism from the All India Insurance Employees Association (AIIEA). The association warns that total foreign control over the sector will prioritize profit maximization over the welfare and security of marginalized sections. Furthermore, the AIIEA highlights a macroeconomic concern: relying heavily on foreign capital instead of mobilizing domestic savings undermines a welfare state's ability to direct national resources towards essential economic development. The move will require amending the Insurance Act of 1938, the LIC Act of 1956, and the IRDA Act of 1999.
Key Points
- The Union Cabinet has reportedly approved raising the Foreign Direct Investment (FDI) limit in the insurance sector to 100%.
- The All India Insurance Employees Association (AIIEA) opposes this decision, cautioning it would negatively impact the Indian economy and domestic insurance companies by shifting focus entirely to profit.
- Critics argue that foreign capital cannot substitute for domestic savings, and a welfare state requires significant control over national savings for broader economic development.
- The changes will require amendments to three key legislations: the Insurance Act 1938, the LIC Act 1956, and the IRDA Act 1999.
Important Terms
Insurance Laws (Amendment) Bill, 2025

2025 legislation that raised the Foreign Direct Investment (FDI) cap in the insurance sector to 100%, introduced composite licenses, and eased capital requirements for insurers.
UPSC context
GS Paper III: Financial sector reforms and mobilization of resources through FDI and market liberalization.
Insurance Act, 1938
The parent legislation of 1938 that provides the legal framework for the insurance industry in India, including rules for registration, capital, and investment.
UPSC context
GS Paper III: Core legislative framework for financial market regulation and its historical evolution.
LIC Act, 1956
Statute that nationalized the life insurance business in 1956, merging 245 entities into the Life Insurance Corporation (LIC) to prioritize public welfare and social security.
UPSC context
GS Paper III: Nationalization history and the role of public sector undertakings in the economy.
IRDA Act, 1999
Key reform legislation that ended public sector monopolies and created a statutory regulator, opening the insurance market to private and foreign participation.
UPSC context
GS Paper II & III: Creation of statutory bodies and the history of Indian financial liberalisation.
Insurance Regulatory and Development Authority of India (IRDAI)
The statutory body under the Ministry of Finance responsible for protecting policyholders and overseeing the orderly development of the insurance and re-insurance industries.
UPSC context
GS Paper II: Statutory and regulatory bodies; their functions in market oversight and consumer protection.
Life Insurance Corporation (LIC)
India’s largest state-owned insurer and institutional investor, established to mobilize domestic savings for long-term national development and social security.
UPSC context
GS Paper III: Public sector’s role in resource mobilization and financial stability.
All India Insurance Employees Association (AIIEA)
A major trade union representing public sector insurance workers that advocates for state control and opposes privatization and excessive foreign dominance.
UPSC context
GS Paper II: Role of pressure groups and formal/informal associations in the policy-making process.
Prelims Trap
"Raising the FDI cap in the insurance sector is an executive decision under FEMA and does not require parliamentary approval."
FDI limits in India's insurance sector are statutory. Changing the cap requires parliamentary amendments to the Insurance Act (1938), not just executive FEMA tweaks.
Static Concepts Connected
What is 'Patient Capital' and how does the insurance sector provide it?
- Long Horizon: Patient capital involves long-term investments without the pressure for quick returns, ideal for long-gestation infrastructure projects.
- Asset-Liability Match: Insurance companies collect premiums now and pay out decades later, providing a perfect structural match for the funding needs of national infrastructure.
How has India's insurance sector liberalized since the 1991 reforms?
- Malhotra Committee: Set up in 1993, it recommended the entry of private players and foreign promoter participation to increase insurance penetration.
- Progressive FDI Caps: FDI limits evolved from 26% (2000) to 49% (2015), 74% (2021 with foreign management control), and now a proposed 100%.
- Statutory Regulation: The IRDAI was created via the IRDA Act, 1999, to regulate and develop the newly opened multi-player insurance market.
Cross-Topic Patterns
Insurance + Infrastructure Pipeline (NIP)
100% FDI in insurance is structurally linked to the National Infrastructure Pipeline, which heavily depends on long-term 'patient capital' generated by life and general insurance funds.
FDI vs Domestic Savings Gap
AIIEA’s critique touches on the macroeconomic Savings-Investment gap. Over-reliance on foreign capital risks higher dividend repatriation, potentially impacting India's long-term Current Account balance.

Expect a 2026 multi-statement Prelims question linking statutory FDI caps in insurance to 'patient capital' for infrastructure financing.
Linked PYQs · 5
Linked PYQs · 5
- 2016MainsGS3
Justify the need for FDI for the development of the Indian economy. Why there is gap between MOUs signed and actual FDIs? Suggest remedial steps to be taken for increasing actual FDIs in India.
- 2020MainsGS3
Explain the meaning of investment in an economy in terms of capital formation. Discuss the factors to be considered while designing a concession agreement between a public entity and a private entity.
- 2017MainsGS3
Among several factors for India's potential growth, savings rate is the most effective one. Do you agree? What are the other factors available for growth potential?
- 2021PrelimsGS1
Consider the following : 1. Foreign currency convertible bonds 2. Foreign institutional investment with certain conditions 3. Global depository receipts 4. Non-resident external deposits Which of the above can be included in Foreign Direct Investments?
- 2024PrelimsGS1
In India, which of the following can trade in Corporate Bonds and Government Securities? 1. Insurance Companies 2. Pension Funds 3. Retail Investors Select the correct answer using the code given below:
