RBI UCB Licensing Revival and Banking Regulation Reforms
Source:The Hindu ↗
Why It Matters
Understanding RBI's policy shifts on cooperative banking is critical for UPSC aspirants studying banking sector stability, financial inclusion, and monetary regulation frameworks.
Summary
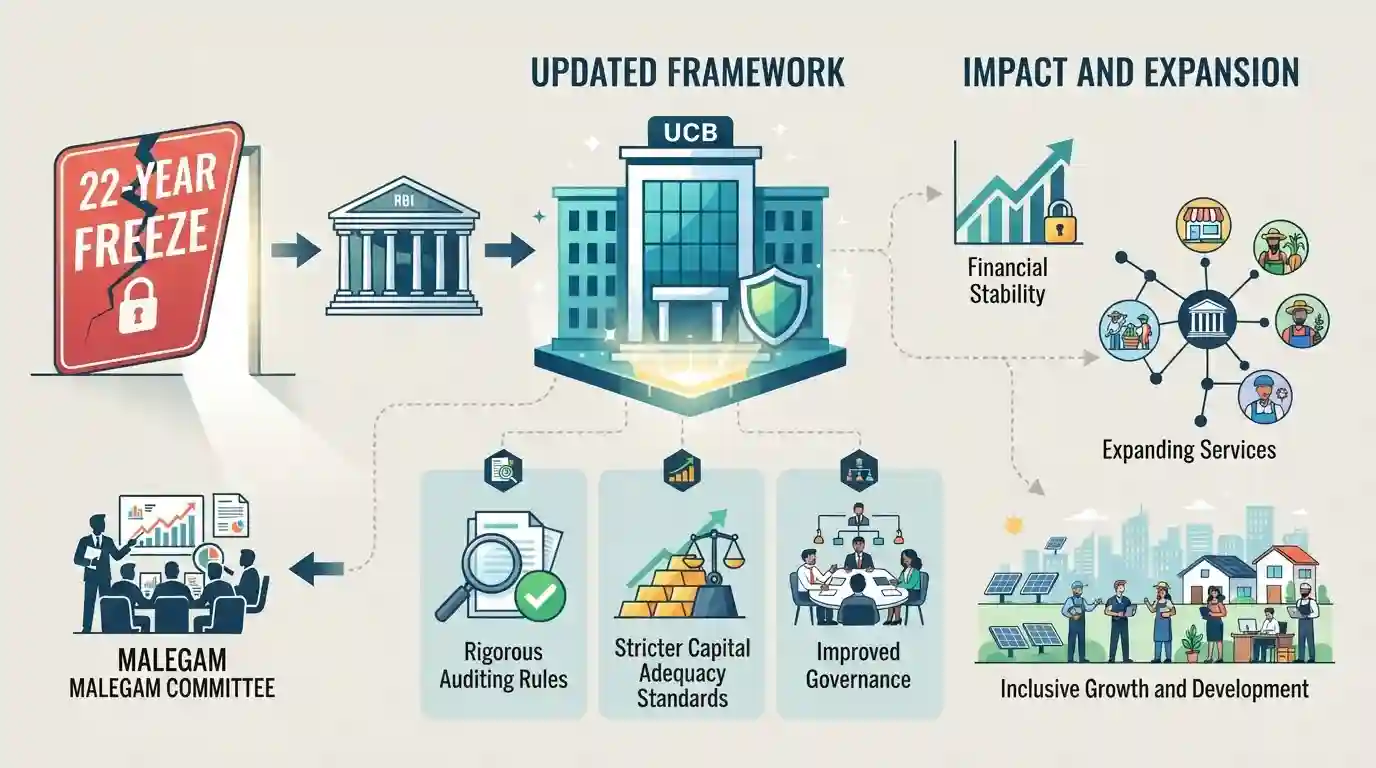
The Reserve Bank of India has reopened licensing for Urban Cooperative Banks (UCBs) after a 22-year freeze, following the Malegam Committee recommendations. The updated framework introduces rigorous auditing rules, stricter capital adequacy standards, and improved governance to ensure financial stability while expanding cooperative banking services.
Key Points
- The Reserve Bank of India (RBI) has resumed licensing for Urban Cooperative Banks (UCBs) after a 22-year hiatus following recommendations of the Malegam Committee.
- New guidelines allow financially sound tier-3 and tier-4 UCBs to expand, backed by stricter audit norms, statutory structures, and enhanced supervisory frameworks.
- Dual regulatory control historically exercised by the RBI and State Registrars of Cooperative Societies under the cooperative federalism framework has faced structural evolution, especially post the 2020 Banking Regulation Amendment Act.
- The policy shift aims to balance grassroots financial inclusion with rigorous systemic stability, reducing vulnerabilities that previously led to bank failures and moratoriums.
Important Terms
Banking Regulation Act 1949

The primary statute governing banking operations and regulatory powers over commercial and cooperative banks in India, providing the RBI legal authority to license, regulate, and supervise banking institutions.
UPSC context
UPSC GS Paper III (Indian Economy - Banking Sector Reforms): Tests knowledge of legal frameworks governing banking regulation and central bank oversight.
Banking Regulation Amendment Act 2020
Legislation that expanded the Reserve Bank of India’s regulatory and supervisory powers over cooperative banks, bringing cooperative governance closer to commercial banking standards.
UPSC context
UPSC GS Paper III (Inclusive Growth and Banking Sector Reforms): Tests understanding of legislative changes addressing cooperative banking vulnerabilities.
Reserve Bank of India
India's central banking institution which controls the monetary policy of the national currency, regulates the banking system, and acts as the banker and supervisor of all commercial and cooperative banks.
UPSC context
UPSC GS Paper III (Mobilization of Resources, Growth & Development): Essential for questions on central bank autonomy, monetary policy, and financial stability.
Static Concepts Connected
How does dual regulation of Urban Cooperative Banks (UCBs) function between RBI and State Registrars?
- RBI Authority:: Banking operations, capital adequacy, and audit norms are strictly regulated by the RBI under the Banking Regulation Act, 1949.
- State Registrar:: Registration, incorporation, management structure, and liquidation are governed by the Registrar of Cooperative Societies of the respective state.
- 2020 Amendment:: The Banking Regulation Amendment Act, 2020 extended RBI powers over cooperative banks regarding board supersession and audit issuance.
Cross-Topic Patterns
Cooperative Federalism vs. RBI Regulatory Overreach
The 2020 Amendment brought UCBs under direct RBI banking supervision, testing the constitutional limits of cooperative federalism under Seventh Schedule Entry 32 (State List) versus Entry 43/45 (Union List).

Expect a statement-based prelims question on the 2020 Banking Regulation Amendment Act and dual regulation of UCBs by RBI and Registrars.
Linked PYQs · 2
Linked PYQs · 2
- 2021PrelimsGS1
With reference to Urban Cooperative Banks' in India, consider the following statements : 1. They are supervised and regulated by local boards set up by the State Governments. 2. They can issue equity shares and preference shares. 3. They were brought under the purview of the Banking Regulation Act, 1949 through an Amendment in 1966. Which of the statements given above is/are correct?
- 2024PrelimsGS1
With reference to the rule/rules imposed by the Reserve Bank of India while treating foreign banks, consider the following statements: 1. There is no minimum capital requirement for wholly owned banking subsidiaries in India. 2. For wholly owned banking subsidiaries in India, at least 50% of the board members should be Indian nationals. Which of the statements given above is/are correct?
