Women Drive Mudra Scheme Financial Inclusion Success in Rajasthan
Source:daily-pioneer ↗
Why It Matters
The Pradhan Mantri Mudra Yojana (PMMY) is a flagship scheme for financial inclusion and grassroots entrepreneurship. Its impact on women in specific states like Rajasthan is highly relevant for RPSC RAS Prelims and Mains (Economy and Social Justice sections), focusing on inclusive growth, state-level implementation of central schemes, and women's empowerment.
Summary
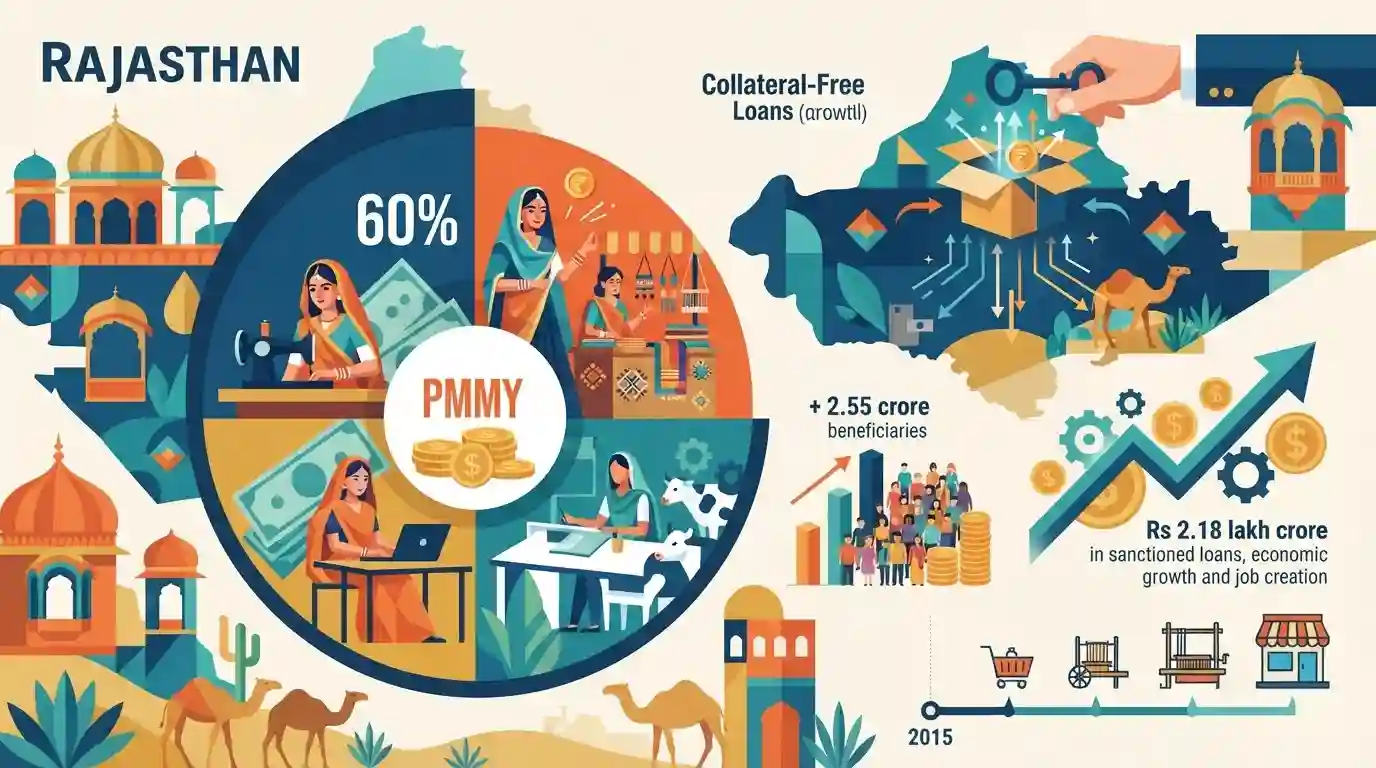
In Rajasthan, women constitute 60% of the beneficiaries under the Pradhan Mantri Mudra Yojana (PMMY), highlighting a significant stride toward female financial independence and entrepreneurship. Launched in 2015, the scheme provides collateral-free loans up to Rs 20 lakh to small and micro enterprises. In Rajasthan alone, over Rs 2.18 lakh crore in loans has been sanctioned to more than 2.55 crore beneficiaries, fostering inclusive economic growth and job creation at the grassroots level.
Key Points
- Over 60% of the beneficiaries of the Pradhan Mantri Mudra Yojana (PMMY) in Rajasthan are women.
- Loans worth Rs 2.18 lakh crore have been approved for more than 2.55 crore beneficiaries in the state.
- PMMY was launched in 2015 to provide collateral-free loans of up to Rs 20 lakh to non-corporate, non-farm small and micro enterprises.
- The scheme has significantly contributed to grassroots entrepreneurship, job creation, and the financial independence of women in the state.
Important Terms
Pradhan Mantri Mudra Yojana (PMMY)

A flagship scheme launched in 2015 to "fund the unfunded." It provides collateral-free institutional credit to non-corporate, non-farm micro and small enterprises, currently offering loans up to Rs 20 lakh.
UPSC context
GS 2 & GS 3 (Government Schemes). Tests knowledge of microfinance, MSME credit, and self-employment initiatives.
Financial Inclusion
The process of ensuring affordable and equitable access to formal financial services—such as bank accounts, credit, savings, and insurance—for disadvantaged and low-income populations.
UPSC context
GS 3 (Indian Economy). Crucial for assessing poverty alleviation, banking penetration, and government economic interventions.
Collateral-Free Loans
Credit extended to borrowers without requiring them to pledge physical assets as security. This mechanism lowers borrowing barriers for low-income entrepreneurs lacking traditional financial backing.
UPSC context
GS 3 (Economy). Important for understanding how state-backed guarantee funds (like CGFMU) enable micro-credit expansion.
Women's Economic Empowerment
The ability for women to access and control productive resources, enter markets, and gain financial independence, thereby reducing gender disparities and driving sustainable macroeconomic growth.
UPSC context
GS 1 (Role of Women) & GS 2 (Social Justice). Tests the impact of welfare schemes on gender equality.
Inclusive Economic Growth
Economic growth that is distributed fairly across society and creates opportunities for all sections, particularly the marginalized, ensuring broad-based improvements in living standards and employment.
UPSC context
GS 3 (Indian Economy). A core syllabus topic evaluating whether economic policies translate into grassroots-level development.
Prelims Trap
MUDRA Bank directly disburses collateral-free loans to rural and urban micro-entrepreneurs.
MUDRA is a refinancing agency, not a direct lender. It provides capital through Commercial Banks, RRBs, MFIs, and NBFCs, which actually disburse the funds.
Static Concepts Connected
What are the loan categories under the PMMY scheme?
- Shishu: Covers loans up to ₹50,000 for entrepreneurs starting a new business.
- Kishor & Tarun: Kishor covers ₹50,001 to ₹5 lakh. Tarun covers ₹5 lakh to ₹10 lakh.
- Tarun Plus: A new category (Budget 2024-25) for ₹10-20 lakh loans, restricted to entrepreneurs who successfully repaid previous Tarun loans.
Which enterprises are eligible for MUDRA loans?
- Sector Scope: Income-generating enterprises in manufacturing, trading, or services. Allied agriculture (dairy, beekeeping) is eligible, but direct crop cultivation is excluded.
- Entity Type: Must be non-corporate and non-farm micro or small enterprises (e.g., sole proprietorships, partnership firms, SHGs).
Cross-Topic Patterns
MUDRA + Lakhpati Didi
High female PMMY participation ties into the broader rural economy push, aligning with the Lakhpati Didi scheme to shift women from subsistence roles to MSME owners.
Refinancing agencies + PSL targets
MUDRA, NABARD, and SIDBI operate as refinancing bodies. Their role is frequently tested alongside how commercial banks and NBFCs achieve their Priority Sector Lending (PSL) quotas.

PMMY's new 'Tarun Plus' ₹20L limit and MUDRA's indirect refinancing role will likely combine into a multi-statement Prelims trap in 2026.
Linked PYQs · 1
Linked PYQs · 1
- 2013RPSC_PRELIMSGS1
The objective of the Mudra Yojana of the Government of India is
