RBI Integrates Thirty Banks With Udpam Portal for Unclaimed Funds
Source:The Hindu ↗
Why It Matters
It is highly relevant for GS-3 (Economy/Banking) and GS-2 (Governance). Understanding the management of unclaimed deposits and the challenges citizens face in navigating banking bureaucracy highlights issues of consumer protection, digital governance, and financial inclusion.
Summary
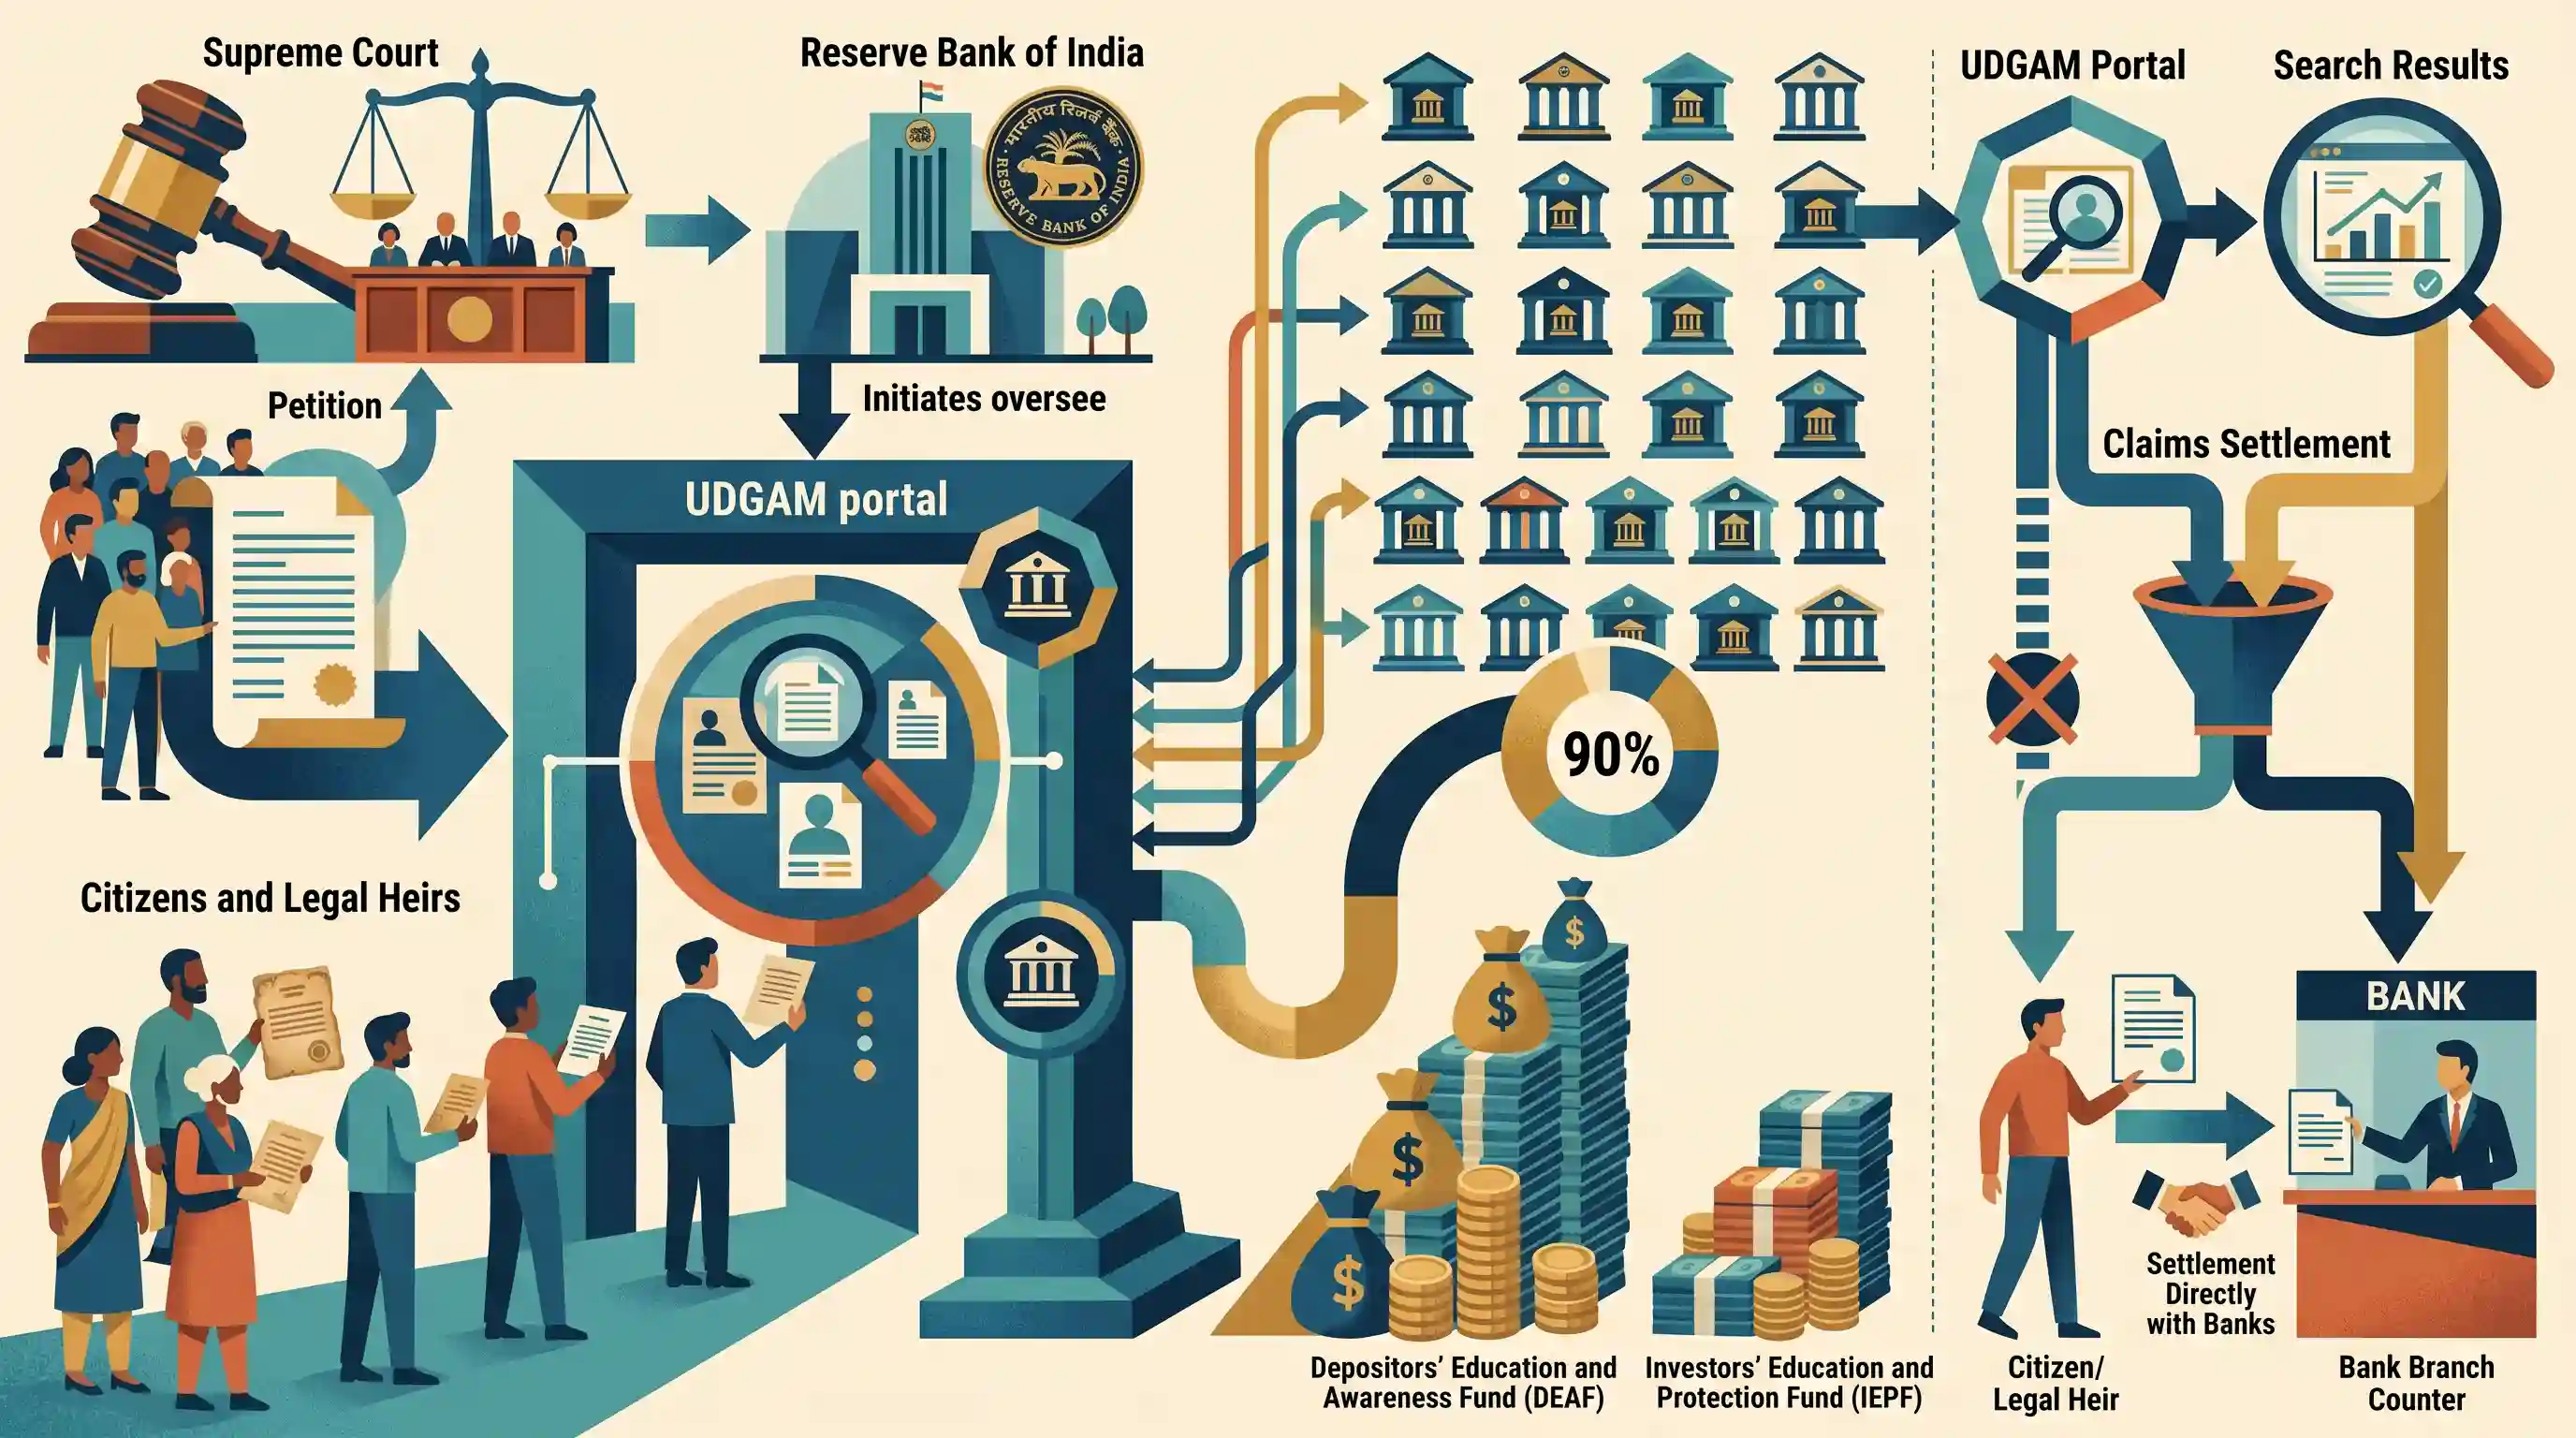
The Reserve Bank of India (RBI) apprised the Supreme Court that 30 banks have been integrated into the UDGAM portal, an initiative to help citizens and legal heirs search for unclaimed deposits across multiple banks. These integrated banks hold about 90% of the funds resting in the Depositors’ Education and Awareness Fund (DEAF). The RBI clarified that UDGAM serves purely as a search mechanism, and claims must be settled directly with the banks. The update was in response to a Public Interest Litigation seeking a centralized, hassle-free settlement process for unclaimed financial assets, pointing out that dormant funds continue to swell across government-managed pools like DEAF and the Investors' Education and Protection Fund (IEPF).
Key Points
- The RBI informed the Supreme Court that 30 banks, which account for roughly 90% of unclaimed deposits transferred to the Depositors’ Education and Awareness Fund (DEAF), are now integrated with the UDGAM portal.
- UDGAM (Unclaimed Deposits – Gateway to Access InforMation) functions solely as a centralized search facility for tracing unclaimed deposits, while the actual claim settlement must be pursued with individual banks.
- A Public Interest Litigation (PIL) pointed out the hurdles faced by legal heirs, demanding a hassle-free procedure that avoids insisting on court orders like succession certificates when a clear will or nomination exists.
- Huge sums of dormant funds are currently locked across silos like DEAF (for banks) and IEPF (for corporate investments), but UDGAM presently excludes post office deposits, provident funds, and insurance schemes.
Important Terms
UDGAM Portal

A centralized web portal launched by the RBI allowing users to search for unclaimed deposits across multiple banks in one place.
UPSC context
GS Paper 3: Digital infrastructure in banking; tests knowledge of financial inclusion and consumer-centric governance initiatives.
Depositors’ Education and Awareness Fund (DEAF)
A fund maintained by the RBI where banks transfer credit balances of accounts not operated for ten years or more.
UPSC context
GS Paper 3: Banking sector regulations; relevant for understanding the management of idle financial assets and depositor rights.
Investors' Education and Protection Fund (IEPF)
A fund established under the Companies Act to promote investor awareness and protect interests by holding unclaimed dividends and matured deposits.
UPSC context
GS Paper 2/3: Corporate governance and regulatory bodies; tests understanding of statutory funds under the Ministry of Corporate Affairs.
Reserve Bank of India (RBI)
India's central bank and regulatory body responsible for supervising the banking sector and maintaining financial stability.
UPSC context
GS Paper 3: Essential for all topics related to monetary policy, banking regulation, and financial system oversight.
Prelims Trap
"The UDGAM portal processes the direct settlement and refund of unclaimed bank deposits."
UDGAM functions purely as a centralized search gateway. It does not settle claims; actual refund processing must be initiated directly with the respective individual banks.
Static Concepts Connected
What is the Depositor Education and Awareness Fund (DEAF)?
- Statutory basis: Maintained by the RBI under Section 26A of the Banking Regulation Act, 1949.
- Eligibility criteria: Funds in bank accounts that have been inactive or unclaimed for 10 years or more are compulsorily transferred here.
- Ownership rights: Transfer does not extinguish ownership. Depositors or legal heirs can still claim funds from the original bank, which then claims a refund from the RBI.
How does the Investor Education and Protection Fund (IEPF) differ from DEAF?
- Asset Type: IEPF handles unclaimed corporate dividends, shares, and matured debentures, rather than standard bank deposits.
- Timeframe: Funds are transferred to IEPF after being unclaimed for 7 years (vs 10 for DEAF).
- Administration: Administered by an authority under the Ministry of Corporate Affairs (Companies Act, 2013), not the RBI.
Cross-Topic Patterns
DPI and Consumer Data Privacy
UDGAM's use of a unique Unclaimed Deposit Reference Number (UDRN) masks account holder identity, linking banking consumer protection directly to ongoing data privacy (DPDP Act) frameworks in India's digital architecture.
Judicial oversight on financial inclusion
PILs demanding hassle-free claim procedures highlight the complex intersection of rigid civil succession laws (like demanding court orders) and the push for frictionless digital banking reforms.

Expect a 2026 Prelims question contrasting UDGAM/DEAF (10 years, RBI) with IEPF (7 years, Corporate Affairs) in pair-matching.
Linked PYQs · 5
Linked PYQs · 5
- 2019PrelimsGS1
Which of the following is not included in the assets of a commercial bank in India?
- 2021PrelimsGS1
With reference to India, consider the following statements : 1. Retail investors through demat account can invest in 'Treasury Bills' and 'Government of India Debt Bonds' in primary market. 2. The 'Negotiated Dealing System- Order Matching' is a government securities trading platform of the Reserve Bank of India. 3. The 'Central Depository Services Ltd.' is jointly promoted by the Reserve Bank of India and the Bombay Stock Exchange. Which of the statements given above is/are correct?
- 2022MainsGS3
Is inclusive growth possible under market economy ? State the significance of financial inclusion in achieving economic growth in India.
- 2016MainsGS3
Pradhan Mantri Jan-Dhan Yojana (PMJDY) is necessary for bringing unbanked to the institutional finance fold. Do you agree with this for financial inclusion of the poorer section of the Indian society? Give arguments to justify your opinion.
- 2020MainsGS2
Judicial Legislation is antithetical to the doctrine of separation of powers as envisaged in the Indian Constitution. In this context justify the filing of large number of public interest petitions praying for issuing guidelines to executive authorities.
